
November 20, 2025
Unfounded Fears Surrounding EIDL Collection
Sound bites
Until you get a letter from a personal agent or a revenue officer, you're dealing with a computer.
It's not good to promise creditors money you don't have.
In this episode
Barry Levine talks about EIDL loan collection, what borrowers actually face, and how to handle a failing business without making panic-driven mistakes.
- Collection activity often begins with automated SBA statements and threatening letters, not immediate action from a live officer.
- Personal liability on an SBA loan can reach up to $300,000, with amounts above that tied to the business.
- A defunct closely held business can be liquidated through an assignment for the benefit of creditors in some states.
- Bankruptcy anxiety is often worse than the actual 341 meeting, and many borrowers are simply dealing with failure, illness, or lost income.
- It is better not to promise creditors money that is not available, and to deal honestly with the business’s real situation.
Transcript
ShowHide
Automatic captions of the conversation. They can contain errors and do not name who is speaking.
Welcome, welcome, welcome, everybody. Merrill Chandler here, your host of The Get Fundable Podcast. And we are back with some crazy relevant intel on EIDL loans. And kind of, as you know, in all of the trainings you receive from me, I acknowledge as power and implemented knowledge as a superpower. Well, today we're gonna be talking about the knowledge of, if you took out an EIDL loan, what is that pattern of collection, how they collect from you, and some of the solutions that are possible. My guest is going to be Barry Levine, and I am excited to introduce you to him in just a moment.
So, stay tuned. We'll be right back. In the constantly changing world of fundability, the big question is this. How are entrepreneurs and real estate investors like us, ones who want to grow our businesses and who are tired of paying for really expensive alternative lending, how do we tap in to the most inexpensive money available and do it without the hassle of typical borrowing? That is the question. And this podcast will give you the answers. Welcome to the Get Fundable Podcast with your host, Merrill Chandler. Wonderful.
Wonderful. Welcome back. Merrill Chandler here, your host of the Get Fundable Podcast and our guest today, Barry Levine, attorney at law and specializing in mitigating EIDL losses and what your toolbox looks like in order to protect yourself from unwarranted collections as well as ways to mitigate the loss against your personal assets and resources. So welcome, Barry. Glad to have you with us. Nice to be here, Merrill. It's a beautiful day in New England today, a crisp fall day. Beautiful. Congratulations. It's drizzly and dreary out here in Utah.
So I'm glad you have a much beautiful vista. Okay. EIDL, the whole game plan for this podcast. And the reason why I was interested in getting you on here is your extensive experience in how the EIDL is being built, collected, the mitigation of the collection process, and bankruptcy or other alternative solutions to making sure that you are not devastated by the failure or collapse of your business, while EIDL loans are still owed and due. So Barry, first of all, give me an introduction of you and why my tribe should be listening to everything that you are saying.
I tell people that I'm just an old hippie who practices law. I've been representing debtors for, it's going to be 45 years in December. And I got on board representing people who owe money, businesses, small businesses, individuals, back before it was popular. And it's that rare case where I represent a creditor and I say, I want my money now. I mean, when you represent people who owe money, we constantly sort of taking a step back and moving to the side and coming up with a good story so we can take another step back.
But getting back to those loans, the collection process is almost non-existing nowadays. And I will tell people I use a lot of Yiddish so bear with me. They tend to send you nudging letters, nagging you and threatening you. And they don't necessarily do anything. This is still the SBA letters, not even the collection letters yet, right? SBA just sends a monthly statement. I have a gentleman who, it's an unfortunate situation, he filed a bankruptcy. And two years after he filed a bankruptcy, he went into the trucking business.
And he took out one of these loans, an SBA loan, and he became disabled. And he can't file a bankruptcy again for eight years. And what we're doing, we're waiting eight years, you'd be surprised at how quickly time passes. Oh, isn't that the truth, right? And but the thing is, the only correspondence, laypeople go into a panic, but he gets an automated notice that says, you owe a payment and make a payment. And to me, that's nothing to concern yourself with. You know, when I deal with government agencies, when be it the IRS, the SBA, or something like that, I tell clients, until you get a letter from a personal agent or a revenue officer, you're dealing with a computer.
So why call into the 800 number, you'll be on hold for an hour. Right. See, in my experience, I work with a number of, we're business advisors, right? And we help get them funding and protect them from loss, right? And so what we've found is I've got a couple of dozen clients who all had EIDL loans. And one way or the other, the business did not, to quote you in our pre-show interview, they were able to use the money to stumble along through Covid and a little bit post Covid. But then all of a sudden, the business isn't any bigger or better than it was before.
They used the capital to limp along, not grow, right? Exactly. Not to scale. As my mother would say, sometimes it's not meant to be. That's what it is. They were able to get through Covid. And now, one thing you pointed out about how to avoid these situations. One of the things I always suggest is it always pays to prepare in advance. If you have to do a sort of a liquidation analysis of yourself to see what your credit is, what your exposure is. Right. And if you take the time to clean that up years in advance, rather than, oh, hitting the fan now, let me put a mortgage on the house to eat up all the equity for love and affection, that doesn't work.
But if dad lent you a half a million dollars to buy your house and you put a mortgage on after the bank's mortgage when dad lent it five years ago, well, that's copacetic and passes muster. Yeah, it doesn't bankruptcy have a seven year, three year look back period? Well, the thing is a trustee in a bankruptcy, it depends, like in Massachusetts, they have two statutes. They could use the federal fraudulent conveyance statute, which I think is about two years. And then the in Massachusetts, the state statute is for you.
Got it. But again, if one thing like a client say, well, why can't we put a mortgage on a house? Well, I could put a thousand mortgages on the house, but somebody is going to want to see the checks that go along with that mortgage. Yeah. Where did the money go? Well, no, that there was in fact money. I can give you a mortgage on my house. Where's your check that secures the mortgage? And if the dad actually lends the money, why should he be different from a bank? Why should he take the loss? Correct. But you're not.
It benefits you to the extent that now, if you have a friendly, secured creditor on your business, or you have a friendly mortgage on your house and things are getting desperate, you can always contemplate a friendly foreclosure or a secured party. Yep. Sales. First in time, first in line. Well, and like I said, the IRS is recording a lien against my house tomorrow. Oh, maybe I should put the house into a realty trust today. That doesn't work. Not going to work, right? We need to do this. Your point is the message is that plan in advance for worst case scenarios, hence those friendly mortgages, friendly mechanics, liens, friendly judgements.
Friendly, but there has to be consideration behind it. Absolutely. That's the key thing. If I'm looking to, for lack of a better word, eat up equity, I will ask clients, has anybody lent you money for the business, for your house? This way, it becomes a legitimate mortgage. You may have a different preference issue because you're not putting it on. And I hope I'm not bogging people down with all this legal, but you're not putting it on when the loan was granted. You're doing it so that it would be a preferential, could be a preference.
But then, you know, like we said before, for somebody who's not a family member, an insider, that's 90 days. And for an insider, it's a year. And you'd be surprised how quickly time passes. Absolutely. So to that point, so we've got SBA loans. And so everything we're talking about guys applies to SBA loans. In particular, the EIDA loan was a special brand of SBA loan where many times the collateral was not required. They built it on your gross profits of the business and they paid whatever that gross profit. They look at the last year's tax returns and they gave it a hundred grand, 200 grand, 500 grand, a million, whatever it was to be able to make it through the tough times where we didn't want to shutter every business in America, right?
Like they did all the restaurants and all the high traffic public businesses that literally shuttered for months or years. So in this process, step one that we need to be aware of is that you're going to for your EIDL, you're probably getting this right now. Every month, they send a new statement saying, by the way, here's your new statement. Every 60 to 90 days, they'll say you owe X amount and that amount does accrue that because they keep giving you a what we call a dunning letter or a letter that is accumulating the number of payments that were missed.
And so since I represent numbers of businesses, we would prepare emails to send to their customer service. And they literally said, this is credit bureaus are this way, lenders are this way, mortgages are this way. They say, you can't ask for a hardship loan until you're 90 days behind. But then SBA would say, we can't honor this request for hardship because you're 90 days late. You need to be brought up to date. And so the right hand didn't know what the left hand was doing. So Barry, in your experience, what happens when the right hand doesn't know what the left hand is doing?
Or what have you found in the collection process? It works to the benefit of the debtor. I mean, because right now, to give you, for instance, I'm dealing with a number of cases where I'm dealing with the Justice Department. I have some student loans that I'm, actually, you can possibly get student loans that discharge in a bankruptcy nowadays, but that's a story for a different day. But I've got in touch with people working for the government and the email responses were furloughed. We'll be back sometime in 2026.
And it's like, one in particular, it went on to say, if you need immediate service, it gave me another person to email. Well, I emailed that person. I got the same response. They were furloughed too. So it's like when you dealt with the IRS during Covid, there were no revenue offices, there were no collection activities. You know, my experience has been is that the only time, you know, if you're dealing with the government with these loans, they're not particularly aggressive. The only time you experience aggressiveness is when it was a bank that orchestrated the SBA loan, because the banks tend to be, I've had cases where the banks have refiled their finance statements and the businesses have been out of business for two years, so they pay attention.
But the banks can be more aggressive. Yeah, as an individual, you know, it's a question of whether you have the intestinal fortitude to deal with these notices. Yeah, let's speak to that because there is an emotional component. My coaching has always been, hey, you can do bankruptcy, which you specialize in, Barry, you can do bankruptcy, or the alternative is, if you've got this intestinal fortitude, if you've got a thick skin to handle threatening letters, many times it will die out and end up at a collection, which will die out and will end up, but rarely do they go to judgment when there are as many loans as there were for EIDL, when there's just vast numbers.
It takes a long time for them. I mean, like I said, the government sort of suffers from a constipation of action. They don't do anything. Great way to say it. The banks, they will be more aggressive. They will nudge you more. They will finally get a lawyer to file suit, maybe. Whether they'll go try to collect collateral if they have collateral, that remains to be seen. To me, it's very weird that they'll give out these loans in the SBA, because historically, if you were a guarantor of an SBA loan, your house was on the line too.
Yeah, traditionally, that's required, right? EIDL, it was the P&L that you sent them, army tax return. I have people with half a million dollar loans, homes, no second mortgage on the house to the SBA, which, you know, stands in your favor. You can walk away from it. But the collection activity, like I said, is from the feds. You have to wait till you get a person, somebody you can talk to, which to me would be not so much concern. It's a question of now I have somebody to talk to. There's a point of accountability on their end.
And the current administration is chopping staff out of every single department, which is just exacerbating how many files the remaining personnel would be able to deal with. Right. And what remind us, Barry, what is the personal on an SBA loan? What is the principal, the business owner responsible for personally? I think the business owner is responsible for up to $300,000 of loans. Up to 300 grand. And then anything above that is on the business. And, you know, interesting, I always have lots of stories. I have a gentleman who took out one of these loans.
He has a recording company. During Covid, there was nobody having conventions to record. And he now has a very significant amount of his loan money left over. And he can't get the SBA to take it back. See, that's another example of, they were not prepared to do the kind of lending that they, like, where you can pay off the principal of the loan. And there's nobody actually to pay back, right? There isn't a revenue department in the... There's nobody, I know from my own experience, you know, when I'll call them up and I'll say, you know, liquidated this business, you have a security interest on the assets, who should I speak to about liquidating or doing something with the stuff that's in this?
Nobody calls back. Nobody does anything. You know, from the collection process, if you're dealing with some pissed off local merchant, that's going to cause somebody more aggravation than the Fed. And the Fed, unfortunately, there is so much... They were trying to do something good. The administration at the time was trying to do something good to keep the wheels turning in the economy. And at the same time, anything is free is not valued, right? And so everybody says, if it's free, I'm happy to take it. But if something goes sideways, meh.
Well, even the people who gave out the money are kind of like, meh. Well, they, you know, it's constant. And the people who were fortunate to get the money, I guess, had kept their businesses alive. But no matter, ultimately, it was a good or bad thing. Because now, like I've been saying, they're all coming home to roost and being liquidated. What would stop, long before bankruptcy, what happens if a business goes defunct? Because I helped clients write letters, prepare letters that were truth, the whole truth, nothing but the truth.
But their businesses had crashed and burned. There's $500 in the check account. The business itself had been renewed, so it's still active, but it was defunct. There is no business transacting in the name of that business. How does that does that? If so, how does it mitigate the collection activities or their interest in that particular business? I, if the business is, I don't know if you know what a prayer for the dead is. We say, Kaddish, right? If it's time to say Kaddish for the business, there is no point in having it open another minute.
And what I do, and I don't know, again, I can only speak to Massachusetts, but for closely, and most of these corporations and LLCs are closely held businesses. Rather than put them through a chapter seven where they have a trustee and a 341 meeting and all sorts of mishegas, in Massachusetts, there is a state remedy. It's called an assignment for the benefit of creditors, which other states I know have. Some involve courts, some don't. And here, in that situation, what I do is we liquidate the defunct company through the assignment.
We send notices out to all the creditors that, hey, they had a long run, and make a nice schmaltzy letter that I send them. And that's the end of it. And, generally, these companies, I have a good friend who I work with on these cases, he refers to them as communication assignments. We just let people know, because when people with clothes, they figure they'll ignore it, and the company's gone, so why do anything? So the next thing you know is some creditor decides to sue them at their house because, well, I looked it up at the Secretary of State's office, and this is where the president lives.
This sort of thing sort of does away with all that. And then, the newment is because usually the principle of the company is stuck with all the personal guarantees. We file a personal bankruptcy, and everything goes away, and life goes on. The only thing I will tell the listeners now, if you do have these loans with the SBA, if you file bankruptcy, at least here in Massachusetts, they have sort of deputized the office of the United States trustee to look into how you use the proceeds from your SBA loans. So be prepared, you know, you don't want to, I once had a client who got an SBA loan, he bought a limited edition cuvette.
He went to jail. You don't want to do that sort of stuff, you know. A recent couple, they had a high-flying film production publicity company. During Covid, they got, they had 15 employees, got $600,000. By the time I liquidated the company, they had no employees and no assets. But when we filed their personal bankruptcy, the trustee asked for how they spent the money. It actually showed that they spent more money than the loans, which went very well. But you need to be prepared for all that. They're now, you know, government after the fact is looking that maybe we shouldn't give in all these people's loans, but it's too late, the money is generally gone.
Yeah, absolutely. So step one, we talk about the statements are coming out, then they'll do collections. And some of my clients have been referred to the Department of Treasury for collection purposes. Are you familiar with that process? And what can you weigh in on that? That's the only concerning process because under certain circumstances, if you are getting government benefit, like the gentleman I spoke about who has to wait, we have another two years to go, he's collecting Social Security, and he's concerned that they may start tapping into his Social Security.
Well, they can tap into tax return. Well, absolutely. You get a very nice letter from the IRS that says you thought you were getting a refund. Guess what? You're not. But again, you don't see that happening. They really have to hate you. They don't have the manpower, the ability to go chasing people like that. Like I said, it's more concerning when you're dealing with a private creditor because they have banks, they send collection agencies. When the government sends it out to a private collector, what better than that?
What's a private collector going to do to you? Yeah. One of our clients actually ran into, so there was Covid in the family, deaths in the family, all these things that had happened. And what I instructed them to do is literally, if it's a three piece of email, every single time you went to the doctor, every single, I mean, literally prove up how you spent your time trying to save the business, but what the circumstances that you found yourself in. And this is just a guess now, but the more detailed that is, they're gonna go after not people who have a legitimate reason for this whole thing failing, right?
They're gonna go after people that they never hear from, there's tons of assets in the business, et cetera. Right, you have to, you know, and everything comes to having a good Schmalz story, you know, it all works out in a certain way. It's like I mentioned briefly about student loans, you know, historically, somebody would come to me when they made the change in the late 90s about discharging a student loan, I'd say either walk in front of a bus or walk in front of a train. I mean, you have to die. But lately, they look at good faith, how they've been handling the loans, and they are dischargeable sometimes.
So you have to sort of go over the story. Again, the story behind it, because they're looking for ROI on their time and resources. And if there is, like in this case, family deaths and Covid, all this mess, there is not a chance you're going to get blood from this turn up. They are likely not to spend a lot of time trying. They try to be like real collectors. It's like the offering compromise with the IRS. They can bill you half a million dollars, but if you have zilch, what are they ever going to get from you? And you know, maybe you can make it go away for short dollars once you satisfy whatever you have to do for them.
And even the sending it off to a collection agency is a judgment call on the SBA's part to say, is this a chance of getting a dime from these guys? Because this case, this three people died in the family, the business crashed and burned, and it's a family business, right? Horrible tragedy. But what are we going to get for even referring it to collections? So it ends up getting a statement. I'm assuming this is just a guess in the back end, but they get the monthly statement letter saying, here's how much you owe, but nothing else has happened for them.
Well, and where are most of these people? You know, if you don't have the money to pay them, what are you going to do? I mean, you can't pay money you don't have. Personal guarantee was 300, because they got over 300, but there was no collateral associated, no assets, no nothing. It was literally based on their previous shares taxes. America is a wonderful place. That's all you can say. Well, okay. So what would you say then is something that people who are facing this, they're at the statement level, they're at the collection level on the SBA, they're at the Treasury collection level, they're at the third party collection level, which none of my clients even hasn't even made it to third party collections.
So it's not ending up on personal credit reports yet. What would you tell somebody to do? Kind of your coding words. I say to you, you write it out. There's nobody, until you have somebody who knows your name and is calling you and is leaving a card at the door or sending you a letter, dealing with these automated notices is just that. It's an automated notice. And I've had clients want me to call, they got a notice from the IRS, they want me to call the 800 number. Yeah, I'll stay on hold for two hours. I mean, you can't do it.
The thing is, it's getting back to what we touched on, it's intestinal fortitude. From my perspective, and probably you can send me notices from today until tomorrow. I don't really care. Send me a lawsuit, send me this. Okay, it's a different story. If there's a lawsuit, or if there is a collection. A threat of something. A threat of something. But now, people may receive phone calls from somebody. In fact, my assistant got one in the office here yesterday. Somebody called and wanted to know if I would accept service for a complaint.
They were suing me. And it's like, what are they talking about? First off, I've never accepted service in my whole career, but that's another story. I haven't heard from them since. It's just they try to get you to do something. And get low-hanging fruit, right? Well, you know, somebody calls up and says, well, you know, from this, that, the other thing, and if you pay us this now, well, there are a lot of people out there who pay them. Yeah, because they're afraid they don't know the system. Hey, it's like the IRS calls.
They'll always give you their badge number. They don't just call you with a name or anything like that, that of the clear blue sky. Yeah. You know, but there are a lot of people that will take advantage of people. And getting back to the collection activities, you know, of any of those collection activities, give you an opportunity to dispute the balance due. By all means, doesn't cost you a cent. And what happens is now they would have to send you all the loan documents. Yeah, the Fair Debt Collection Practice Act has a great deal.
For those of you who are part of our Funding Hackers member area, all those disputes are in the members area, you guys. So if you're not a member of Funding Hacker member, then send an e-mail to support at getfundable.com so that we can make sure that you have the tools you need to ask for all the documentation you have a legal right to before even collection procedures even begin. Barry, final words and contact information for people who want to have a consultation with you or what's your offer? Well, I tell you, I've been doing this for a long time.
You know, somebody I do some of my own podcasts, you know, I've done a book on bankruptcy and somebody came up to me and said, the one thing that convinced him that I sort of knew what I was talking about is, I tell people it's only money, you know, thank God it's not your health. The credit card companies, the government, they'll all survive. And what I find unfortunate is people who spend all their time, if you have a family or you're married, you know, the most important things are putting food on the table, paying the rent and living, not paying your credit cards and they'll survive.
And I'm a very practical guy, like with the SBA. I don't believe in, and this comes from Reddit, representing people who owe money. I don't believe in being proactive necessarily when your client owes money, because there's nothing proactive to do. Many decades ago, I learned, you know, I'll have people come in to me, they'll have a business that being sued for $30,000. And they'll say, cut a deal. I said, so what's the deal? I'll pay them off within 30 days. And I'll say, Schmuck, you know that's never gonna happen.
Let me give you a two-year payout. If you walk in like a big hero in 30 days, fine. But after 30 days, I don't hear from the guy wanting to know where the payments are. Right. So you really have to, everybody, you have to know, you have to deal with your reality. It's not good to promise creditors money you don't have. That you don't have. And to be honest and upfront. Yeah, absolutely. And, you know, as a sign off, you can find me at the levineslaw.com. That's levineslaw.com. My podcasts are on YouTube. Barry Levine bankruptcy through the looking glass.
Wonderful. We'll put those in the show notes to make sure everybody has access to those. You know, I enjoy this podcast stuff. I am a frustrated comedian. Yeah, we're thrilled to have you here bringing your expertise and kind of, I like giving people shining a light on the path because then there's nothing scary. Well, you know, the best part I find is when people go through a bankruptcy, there's a 341 meeting and when I tell them the anxiety of the 341 meeting is a lot worse than the reality of the 341 meeting, they go through it and I'm schmoozing with the trustees who I know for almost 45 years.
And they're done and they say, that's it? I said, yeah, that's it. It's not that big. You know, most people nowadays are straight shooters who are up against it for one reason or another. Business failed, medical problems, lost a cushy job. When I had a lot more hair many years ago, there were the games players, you know, that would go out, could file a bankruptcy, take a trip. No, they didn't have to pay for it, go on a cruise. But it's been a long time, and most people are just up against the wall nowadays. Yeah, it really is so.
Barry, thank you for being here. Thank you for creating this clarity on my group. Everybody, Merrill Chandler, your host of The Get Fundable Podcast, we'd like to thank Barry for being here. Stay well, everybody. And check his YouTube out, Beyond the Looking Glass. Behind the Looking Glass. Behind the Looking Glass. And make sure that you guys check out his website for any further intel. If you have situations that he can help remedy, we're all about it. Thank you guys. Be well and have a spectacular rest of your day.
Thank you, Merrill. You too. Thank you for listening to the Get Fundable Podcast. Please leave comments because Merrill would love to read about your aha moments from this episode. And be sure to visit getfundable.com to read our blog, get important links, join our community, and much, much more, like ordering Merrill's tell-all book that is changing the world, The New F Word. And you've got to tell your friends about this podcast because we want them to get fundable too.
About Barry Levine
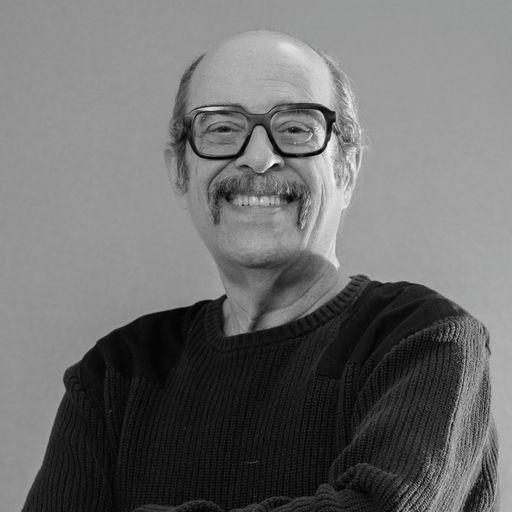
Bankruptcy Attorney and Debt Strategist for Everyday Americans in Crisis
45 years Representing people in financial difficulty1 book Author, Personal Bankruptcy Through The Looking Glass322 videos On his own bankruptcy YouTube channelBankruptcy attorney Massachusetts
The calls often come late: someone has ignored letters from the IRS, missed too many loan payments, or watched their small business slowly bleed out. They don’t open with legal questions. They ask if there’s any way out.
For almost 45 years, Barry Levine has answered that question with calm, practical guidance. A Massachusetts-based bankruptcy attorney, he works with individuals and small business owners navigating serious financial strain, people who are scared, out of options, and unsure what the next step even looks like. His work isn’t about judgement or quick fixes. It’s about helping people understand what tools are available, how the system works, and what choices they can still make.
What Barry sees again and again is that fear, not just debt, is what traps people. The legal process has structure, options, and predictable outcomes; what derails most clients is the panic that keeps them frozen in place. Barry’s role is to bring order to the chaos. With each case, he applies decades of legal experience to help clients understand what’s happening, what’s possible, and how to move forward with a strategy that restores both stability and control.
He first started practicing bankruptcy law in a hands-on Boston office while still in law school, learning case by case how to navigate both paperwork and people.
More from Barry Levine
All episodes → The Agent of WealthFinancial Crisis, Bankruptcy and Starting Over With Barry LevineOct 2026Play episode →
 School for Startups RadioOctober 5, 2026 – EdTech Find Your Grind Nick Gross and Bankruptcy Attorney Barry LevineOct 2026Play episode →
 Financial Mastery SimplifiedHow Bankruptcy Really Affects Your Credit and Home LoanSep 2026Play episode →
 Money Talk With TiffWhat Bankruptcy Actually Does with Attorney Barry LevineAug 2026Play episode →
 Wealth B-HersFear, not Debt with Barry LevineJul 2026Play episode →
 Us People PodcastThe Law We Decide To Practice - Barry Levine - Attorney At Law #314Apr 2026Play episode →
 Chrisman Commentary - Daily Mortgage News4.14.26 Fines Versus Taxes; Attorney Barry Levine on Delinquencies and Foreclosures; Agency MBS PerformanceApr 2026Play episode →
 JUSTIN AND THE [FOOD] ENTREPRENEURSEpisode 520: Barry Levine of The Law Offices of Barry R. Levine - Beverly, MA. Shielding Your Personal Assets. Avoid Bankruptcy Before It Hits. Legal Lifelines for Food Entrepreneurs. Cost Accounting.Apr 2026Play episode →
 How Much Can I Make? — Real Jobs. Real People. Real Money.Bankruptcy Lawyer Explains Chapter 7, Chapter 13 & Getting a Fresh StartMar 2026Play episode →