
November 11, 2025
Ep 201: Freedom Over Fear: Why Bankruptcy Can Be a New Beginning
Sound bites
The anxiety of the three forty one meeting is a hell of a lot worse than reality.
If you find yourself in that situation, it's the best way out because otherwise it's shoveling shit against the tide.
In this episode
Barry Levine joins Michelle Perkins to explain bankruptcy options, clear up common fears, and show when filing can provide a practical way forward.
- Difference between Chapter 7, Chapter 11, and Chapter 13 bankruptcy
- Chapter 7 can discharge debts while many people keep homes and cars, especially with Massachusetts homestead protection
- Chapter 13 can let people repay mortgage arrears over five years while staying current on ongoing expenses
- Foreclosure often takes time, and banks may not accept partial payments without the full arrears
- The meeting of creditors is usually less intimidating than people expect and can be over in minutes
Chapters
Pick a chapter to play the video from that point.
Transcript
Automatic captions of the conversation. They can contain errors and do not name who is speaking.
Speaker 1: Have you ever had a money or career question you Speaker 1: really wanted to ask, but didn't know who to go to, Speaker 1: or just felt uncomfortable even bringing it up. You're not alone. Speaker 1: Talking about money can feel intimidating, even scary, and that's Speaker 1: exactly what I'm trying to change. That's why I created Speaker 1: a free virtual coffee chat, a casual, no pressure, twenty Speaker 1: minute conversation where you can bring one thing you're wrestling Speaker 1: with and we'll talk it through.
No judgment, no jargon, Speaker 1: no sales pitch, just clarity, ease, and a real answer Speaker 1: from someone who gets it. If you've got something on Speaker 1: your mind, don't sit in the confusion. Book a spot Speaker 1: at limitreelife dot com and let sip and sort it out. Speaker 1: Hey there, and welcome to Money in You. I'm Michelle Perkins, Speaker 1: your host. My search for more fulfilling work led me Speaker 1: to career in business coaching, where I stumbled upon a Speaker 1: game changing discovery. Money issues often start with our mindset Speaker 1: and habits.
You see, our relationship with money is the Speaker 1: cake to overcoming those frustrating financial obstacles. As an entrepreneur, coach, Speaker 1: and problem solver, I'm passionate about helping you create a Speaker 1: great relationship with money, because turns out that's the foundation Speaker 1: for a limit free life. Each week on Money in You, Speaker 1: I speak with amazing guests about all things money, mindset, Speaker 1: practical tips, and everything in between. We're here to give Speaker 1: you new insights, education, and empowerment.
So money can be Speaker 1: one of your favorite relationships. So join us for some Speaker 1: lively conversations and let's transform your financial life together. Welcome Speaker 1: to the Money and You Show. I'm so excited about Speaker 1: today's episode. I have a really, really fun and interesting Speaker 1: guest and you from that you won't probably be able Speaker 1: to guess his specialty, but I'm going to tell you Speaker 1: he is one of the most entertaining guests I've talked to. Speaker 1: And he's also an expert in bankruptcy, not really very Speaker 1: fun sounding topic that one would, you know, find comedy in, Speaker 1: but our guest today, Barry Levine does, and so I'm Speaker 1: going to just bring him right on.
And you know, Speaker 1: I don't know about you, but if you've had and Speaker 1: I know a lot of people have had this where Speaker 1: they just feel up against a wall, you know, don't Speaker 1: know what to do with the bills or the business problems, Speaker 1: or you know, whatever is affecting their financial life at Speaker 1: particular points in life. And there's a part of many Speaker 1: people's brain that goes straight to there's there's no alternative. Speaker 1: I'm going to have to file bankruptcy. Is that true?
Speaker 1: I don't know. Our minds tell us a lot of untruths. Speaker 1: So I'm going to bring Barry on to really dispel Speaker 1: a lot of myths and to put a bit of Speaker 1: a positive light on this should it happen to you, Speaker 1: and also with all kinds of tips on how to Speaker 1: just you know, deal with this if this is an Speaker 1: aspect of your life at any point. So stay with us. Speaker 1: I'm going to give you a little background on Barry Speaker 1: and then I'll bring him right on. So, Okay, the Speaker 1: calls come late.
Someone has ignored letters from the IRS, Speaker 1: miss too many loan payments, or watch their small business Speaker 1: slowly bleed out. They don't open with legal questions. They Speaker 1: ask if there's any way out. For almost forty five years, Speaker 1: Barry Levine has answered that question with calm, practical guidance. Speaker 1: A Massachusetts based bankruptcy attorney, he works with individuals and Speaker 1: small business owners navigating serious financial strain. People who are Speaker 1: scared out of options and unsure what the next step Speaker 1: even looks like.
His work isn't about judgment or quick fixes. Speaker 1: It's about helping people understand what tools are available, how Speaker 1: the system works, and what choices they can still make. Speaker 1: What Barry sees again and again is that fear, not Speaker 1: just debt, is what traps people. The legal process has structure, options, Speaker 1: and predictable outcomes. What derails most clients is the panic Speaker 1: that keeps them frozen in place. Mary's role is to Speaker 1: bring order to the chaos. With each case, he applies Speaker 1: decades of legal experience to help clients understand what's happening, Speaker 1: what's possible, and how to move forward with a strategy Speaker 1: that restores both stability and control.
He first started practicing Speaker 1: bankruptcy law and a hands on Boston office while still Speaker 1: in law school, learning case by case how to navigate Speaker 1: both paperwork and people. That early experience still shapes his Speaker 1: work today, detail oriented, outcome focused, and human above all. Speaker 1: As a podcast guest, Barry likes to speak plainly about Speaker 1: what financial collapse actually involves, what protections exist, and how Speaker 1: people can move forward. So Barry, welcome and I can't Speaker 1: wait to get into this conversation.
Speaker 2: It's a pleasure to be here. I love to hear Speaker 2: such nice things about myself that they should only know. Speaker 2: But you know, the one thing you hit upon I Speaker 2: try to get across to people is bankruptcy isn't the Speaker 2: end of the world. It's actually, well they talk about Speaker 2: fresh thoughts, but very often it is a new beginning Speaker 2: for people. Speaker 1: Yeah, and you know that was something that I found Speaker 1: to be a really fascinating and refreshing mindset shift.
And Speaker 1: that's the show is about all things money, but I Speaker 1: always always like to include mindset and ideas about your Speaker 1: relationship with money, because as you said in the bio, Speaker 1: you know, it's the fear that is really more destructive Speaker 1: than the actual thing happening to you out there. And Speaker 1: it's it's all this, I mean, bankruptcy has just such Speaker 1: a it does feel like an ending. It it has Speaker 1: a lot of connotations to it, and it's been built Speaker 1: up into this you know kind of you know, last Speaker 1: resort action that's going to take you out for years Speaker 1: and years.
Speaker 2: So well, you know the the problem you know that Speaker 2: I have to say one you know, I do my Speaker 2: own podcast every once in a while, and somebody saw Speaker 2: one of them, and he called me to retain me. Speaker 2: And he said, what he found very refreshing was when Speaker 2: I tell people it's only about money. You know, thank god, Speaker 2: it's not your health, it's not this, that and the Speaker 2: other thing. It's only money. And the credit card companies Speaker 2: and the banks and this.
They'll all survive, you know. Speaker 2: And I find that, you know, people very often they Speaker 2: don't really realize that when they're spending all their money Speaker 2: paying their credit cards, they're an indentured servant. And slavery Speaker 2: went out in the Civil War, and you know, you're Speaker 2: working for your creditors. And to me, it's more important Speaker 2: to put food on the table, gas in the car, Speaker 2: pay the rent than you know, twenty five dollars to Speaker 2: Bank of America that you may pay off in a Speaker 2: thousand years.
Speaker 1: Right, yeah, So where are you going with that? What is? Speaker 1: What are you well? Speaker 2: You know, the thing is you have to won. You know. Speaker 2: What often happens is people decide to become proactive after Speaker 2: the fact. You know, especially you mentioned entrepreneurs. If you're Speaker 2: somebody that's going to be in business, you know, entrepreneurs, Speaker 2: this idea is great, and it goes out of business Speaker 2: a year later. You know, it's best to try to Speaker 2: look at yourself and make yourself judgment proof, you know, Speaker 2: to make sure that if the shit hits the fan, Speaker 2: you have nothing to lose.
And you know, it's like, Speaker 2: you know, the person who comes into my office, like Speaker 2: you mentioned, you know, they have a foreclosure today at Speaker 2: four o'clock. That doesn't happen. You know, everything creditor wise debts, Speaker 2: nothing happens. You know, who knows tomorrow in America. But Speaker 2: as of now, everything you have noticed, you have disclosure. Speaker 2: You know, nothing happens in a vacuum. And you know, Speaker 2: if you think about you know, you look at your assets, Speaker 2: you look at your liabilities, and you know, to start off, Speaker 2: you should see what you have at risk when you're Speaker 2: out there.
But granted that's the perfect world. You know, Speaker 2: most people, you know, they're overcome by it. You know Speaker 2: when I had you know, I tell people I had Speaker 2: a lot more hair back in nineteen eighty when I Speaker 2: started doing this stuff. You know, people were games players. Speaker 2: They could go to a department store and charge up Speaker 2: this and do that, and go on trips and figure Speaker 2: they go bankrupt and get out of it all. But Speaker 2: you know, it's been almost thirty five forty years now Speaker 2: that most of the people who file bankruptcy are either downsized.
Speaker 2: We're making a very good living and now we're making nothing, Speaker 2: or have medical expenses that they have no insurance for. Speaker 2: And what are you going to do? You know, you Speaker 2: have no choice. And granted you have these commons. You know, Speaker 2: don't get me started on debt settlement companies. But if Speaker 2: you're blind in your left eye and you're missing your Speaker 2: right leg, we have a special program for you. It's Speaker 2: all bullshit. You know, none of that stuff exists.
And Speaker 2: when you get down to it, most people, unless you Speaker 2: have like a Picasso, something that has intrinsic value, when Speaker 2: you get down to filing a bankruptcy, most people are Speaker 2: assetless cases. And in Massachusetts in most other places, if Speaker 2: I file the bankruptcy today, four months from now, I'm Speaker 2: going to get my discharge and life will go on. Speaker 2: And the interesting thing about creditors nowadays is they look Speaker 2: at a lot of these post discharge debtors as good Speaker 2: credit risks because now they're making forty to fifty or Speaker 2: more than thousands of dollars a year and they can't Speaker 2: file a bankruptcy again.
For age years. Speaker 1: See what anybody thinks about that. I mean, that's not Speaker 1: really out there. Speaker 2: So you'd be surprised. Oh, I've done bankruptcies four times, Speaker 2: five times for people over the time I've been practicing. Speaker 1: Wow, And how do you see their lives kind of Speaker 1: going when that happens. Speaker 2: They you know, something they come back there. Like I said, Speaker 2: a lot of them are entrepreneurs. They had an idea Speaker 2: that didn't work out, or they had a business that Speaker 2: was just driving them with sugar, and they they take Speaker 2: a break, you know, they file bankruptcy.
Now they're working Speaker 2: for themselves for a while, and then eventually they build Speaker 2: up to something else bails again and I'm still around. Speaker 2: So but you'd be surprised, you know. Speaker 1: I think that's a really interesting thing because I think Speaker 1: a lot of business owners start pouring their personal money Speaker 1: or you know, taking second mortgage out things like that Speaker 1: to kind of cover these things. Speaker 2: I have good stories for everything, Okay, I had. They Speaker 2: were in the plumbing business, no HVAC, but it's like Speaker 2: the same thing.
And there were three partners, two brothers Speaker 2: and an older gentleman. And the two brothers came to Speaker 2: visit me. They were having some problems they hadn't been Speaker 2: paying their withholding taxes, which if you've ever got into that, Speaker 2: for a closely held business that's having financial difficulty, the Speaker 2: money you withhold from employees is the best cash flow Speaker 2: to dip into, because nobody's standing there with a gun Speaker 2: making sure you're paying it over to the government.
I mean, Speaker 2: that's just the way of nature of the business. And Speaker 2: they owed the IRS about sixty seventy grand and unpaid Speaker 2: withholding liabilities. And I told them to file a Chapter Speaker 2: eleven because in a chapter eleven, when you have tax liabilities, Speaker 2: it's a very easy thing. You pay that. You give Speaker 2: them a deposit and you pay it out over five years, Speaker 2: and the interest rate is prime plus two and a half. Speaker 1: Okay, not bad. Speaker 2: Yeah, they spoke to their He didn't like it.
He Speaker 2: decided to use the equity in his house to pay Speaker 2: off the IRS. You know, So, I've been doing this Speaker 2: long enough that I knew they will be back. And Speaker 2: they came back a year later. They had the same Speaker 2: sixty seventy thousand dollars due to the IRS withholding. I Speaker 2: gave him the same advice. They went back to the Speaker 2: Now at this point, their partner was a schmuck as Speaker 2: far as I was concerned. But he said, no, he Speaker 2: had equity in his house. He's going to use the Speaker 2: equity to pay off the irs.
He paid off the irs, Speaker 2: and again I put them in my calendar. Back then Speaker 2: I kept the lawyer's diary in my desk. Now I Speaker 2: don't know why I still buy it. Six months later Speaker 2: they came back. Now they owe the I Rs. One Speaker 2: hundred and twenty grand, and he didn't have any more Speaker 2: equity in his house to pay them off. They had Speaker 2: to file a Chapter eleven. They lasted thirty days and Speaker 2: the business was gone. Wow. And you know, I always Speaker 2: you know, I've done this long enough that I find Speaker 2: myself telling people I told you so very often, because Speaker 2: why would anybody listen to me?
You know, I've only Speaker 2: been doing this for forty five years. What could I know? Speaker 1: So? So the advice would have been do this earlier Speaker 1: rather than later. Speaker 2: Exactly exactly. You know you don't want to, you know, Speaker 2: the tendency of especially small business owners, is that they Speaker 2: ignore the obvious. You know again, another chapter eleven story. Speaker 2: In Chapter elevens, when you are operating as a debtor Speaker 2: in possession, you have to file cash flow statements.
And Speaker 2: back when this case was being heard, there was a Speaker 2: judge out in Worcester of wonderful guy. But if you Speaker 2: ask them to submit a brief, he took things under advisement, Speaker 2: and when he retired, they brought a judge down from Speaker 2: Maine to enter the opinions on all the cases that Speaker 2: were still pending. So somebody tried to file what's called Speaker 2: emotion for a leaf from Stay. They were a secured Speaker 2: credit that they wanted their money. They hadn't been paid Speaker 2: in years.
The judge took it under advisement and I Speaker 2: go to meet the debtor, and the debtor I look Speaker 2: at his cash flows. They're going like this, but business Speaker 2: was wonderful because he didn't have to pay anybody. Speaker 1: Wow. Speaker 2: Wow. He didn't survive much longer either. But you know, Speaker 2: they live in a dream world very often, you know, Speaker 2: and unfortunately for me, I'm an inveterate cynic, and it's Speaker 2: very difficult. You know, think it's a blood from a Speaker 2: stone or water from a stone in the Bible, it Speaker 2: just doesn't happen in real life.
Speaker 1: Wow, that is really interesting to me. So so when Speaker 1: you get that feeling that you know, I'm just going Speaker 1: to have to start gutting my personal you know, investments Speaker 1: and and that kind of thing. That's when you stop Speaker 1: and ask. Speaker 2: You you have to you have to put it. You Speaker 2: have to make a decision that I'm not going to Speaker 2: start putting all my personal money in. It happens, you know, Speaker 2: it happens all too often. I see people keeping businesses Speaker 2: alive that have no business being kept alive.
Speaker 1: But yeah, I've seen it too, and so and I Speaker 1: haven't really talked about this. You know. It's all about Speaker 1: the wonderful things you can do to grow and and Speaker 1: but nobody talks about well, people do talk about it, Speaker 1: but it's this idea that people are kind of delusional. Speaker 1: I think spans the whole, you know, financial spectrum. I Speaker 1: think business owners definitely do it because you're you know, Speaker 1: when you're a business owner, you and I are business Speaker 1: owners actually, and you know you're you're kind of wrapped Speaker 1: up in serving people and your purpose and you know, Speaker 1: I mean, you've built this thing.
It's like a it's Speaker 1: like a behavy. Yeah, and so you don't want to Speaker 1: let it go. You want to do everything possible to Speaker 1: help it thrive. But we do get blind to things Speaker 1: and you know, I think pretty much every every business Speaker 1: coach out there is going to talk about, you know, Speaker 1: people focusing on revenue and not profit, and people not Speaker 1: paying attention to their cash flow, which is exactly why Speaker 1: these things occur. And uh and you know, I also Speaker 1: understand people getting to bind and the business isn't coming in, Speaker 1: so you feel like you need to spend more to Speaker 1: bring the business in.
And you know, it's it's a Speaker 1: it's definitely challenging, it can be, but I kind of Speaker 1: love the idea of noticing, stopping and really you know, Speaker 1: reworking what you're doing. Speaker 2: Well, it's you know that of course sometimes is easier Speaker 2: said than done. But you know, the one thing I'm Speaker 2: finding nowaday is just in general, and I don't know Speaker 2: if you're finding it out in your neck of the woods, Speaker 2: is you know, the SBA was very nice to businesses Speaker 2: during COVID.
They were lending money to this one and Speaker 2: lending money to that one, and especially with closely held Speaker 2: businesses that I typically represent, the loan was good for Speaker 2: a very short period of time and now the loans Speaker 2: are coming home to roost and there's no way these Speaker 2: small businesses can pay. I mean, they gave them loans Speaker 2: based on revenues which had nothing to do with anything. Speaker 2: And what I'm doing a lot of is liquidating these Speaker 2: small businesses, followed by the principles of the small businesses Speaker 2: going bankrupt too, because they don't necessarily realize that the Speaker 2: SBA can be discharged in a bankruptcy.
Speaker 1: I wasn't sure about that either, So what what can Speaker 1: and can't be discharged in a bankruptcy? And just to Speaker 1: follow up, when something is discharged, what does that even mean? Speaker 1: It just goes away that day. Speaker 2: It's well if again, I love to give examples. You know, Speaker 2: somebody gets an IRS tax line recorded against them. An Speaker 2: IRS tax line is good for ten years. And even Speaker 2: though and I hope they're no revenue officers listening and Speaker 2: don't change anybody's idea.
But even though technology being what Speaker 2: it is, the IRS in order to have their tax Speaker 2: line survive ten years, has to renew the tax line Speaker 2: before the expiration of the ten years. Now in Massachusetts, Speaker 2: you can only do a tax line search at the Speaker 2: court for obvious reasons. You can't do it online and Speaker 2: all that stuff. When you did a tax line search, Speaker 2: and this was up until about ten fifteen years ago, Speaker 2: they had a three eighty six computer with a dot Speaker 2: Maketrix printer.
Tax leans out and so you would look Speaker 2: up the tax lienes. They never renew them. So if Speaker 2: people have patients, I've had a number of clients actually Speaker 2: outweigh to ten years and much like a discharge in bankruptcy, Speaker 2: the tax lien becomes of no consequence. Wow. Interesting and Speaker 2: like I tell people, you'd be surprised that how quickly Speaker 2: ten years can pass, But in a bankruptcy it's the Speaker 2: same thing. You know, unsecured debt can be discharged. Secured Speaker 2: debt can be discharged to the extent that they try Speaker 2: to sue you beyond the value of the collateral.
Taxes Speaker 2: under certain situations can be discharged, like income taxes. Rule Speaker 2: of thumb is if they are more than three years Speaker 2: from the date the tax was tax return was filed. Speaker 2: You know, they're different provisos and stuff, but they can Speaker 2: be discharged. Trust fund taxes unpaid withholding unpaid sales tax Speaker 2: meals tax those cannot be discharged. And student loans. I've Speaker 2: had recent success with student loans and getting the discharged. Speaker 2: You know, years passed up until when they made them Speaker 2: non dischargeable.
I think in ninety eight. You know, since then, Speaker 2: I've told people, if you want to discharge student loans, Speaker 2: walk in front of a bus. But recently the FEDS Speaker 2: have started to take a look at the good faith Speaker 2: of the student loan borrow how all the loans are Speaker 2: they did they graduate and are they working in the Speaker 2: degree field that they graduated in, and what their income is. Speaker 2: And I've had two situations where student loans have been discharged, Speaker 2: and I'm working on a third right now.
So it's Speaker 2: not the end of the world. Speaker 1: Yeah, I really like that mess that this isn't the Speaker 1: end of the world. And you know, back to those Speaker 1: business owners, do you find that they go through the Speaker 1: bankruptcy and then restart their business? I mean is that Speaker 1: I mean separately? Speaker 2: Well, you know lots of times in Massachusetts we do it. Speaker 2: You know, you can liquid data business several ways. Closely Speaker 2: held businesses, I generally don't file Chapter seven's because they're Speaker 2: very intrusive, you know, three forty one meetings, preferences and Speaker 2: trustees and bankruptcy very often don't distinguish between the closely Speaker 2: held corporation and the principle.
Well, for instance, like I said, Speaker 2: I got lots of stories. These people had their cooperation, Speaker 2: and they lent money to the corporation, and they in Speaker 2: the two years they were in an office equipment. In Speaker 2: two years, they accrued a lot of unpaid sales tax. Speaker 2: And their accountant at the time said, you had lent Speaker 2: a lot of money to the business. Don't take it Speaker 2: out as income payroll, take it out as lawn repayments. Speaker 2: So and this was before they had come to me.
Speaker 2: Their local retainers said, well, instead of filing a Chapter eleven, Speaker 2: which they would probably still be around today, he filed Speaker 2: the Chapter seven. And they asked about preferential payments, and Speaker 2: all those payments that their accountant told them was an Speaker 2: ingenious thing to do, were preferences. And when I got Speaker 2: involved with the case, the trustee, who I happened to Speaker 2: know quite well, said, Barrid, your clients have ninety six Speaker 2: thousand dollars to pay us.
They wound up filing a Speaker 2: Chapter thirteen. But you know, sometimes there is justice. They Speaker 2: got an erroneous refund from the irs of forty two Speaker 2: thousand dollars that they were able to keep. America is Speaker 2: a wonderful place. Speaker 1: It's so filed. Can you do as a favor and Speaker 1: just define the chapter seven, eleven, and thirteen. Speaker 2: For US, sure, chapter seven is a straight liquidation. I Speaker 2: mean basically, you file a Chapter seven, you list all Speaker 2: your assets, you list all your liabilities, and you discharge Speaker 2: your dischargeable liabilities.
The odds are I mean, and I Speaker 2: can speak mostly for Massachusetts. In Massachusetts we probably have Speaker 2: one of the best homestead protections in the country, up Speaker 2: to a million dollars in equity. So most people go Speaker 2: through bankruptcies chapter seven's they keep their homes, they keep Speaker 2: their cars. They really don't miss it beat, okay. Chapter Speaker 2: thirteen is usually well, it's called a wager in a plan, Speaker 2: and it's There are two reasons that I find for Speaker 2: chapter thirteens.
One is because people are forced into it Speaker 2: because of their income. As I don't know if your Speaker 2: viewers know when you file bankruptcy, whether you can file Speaker 2: a Chapter seven or chapter thirteen is based on household Speaker 2: income and household size, So of course I should know Speaker 2: this off the top of my head. But you know, Speaker 2: for instance, if you're a family of four and you Speaker 2: make over one hundred and seventy two thousand dollars a year, Speaker 2: you have to file a Chapter thirteen and go through Speaker 2: the whole means test.
The other reason people file Chapter Speaker 2: thirteens is people who have mortgage areas. You know, I've Speaker 2: had some clients who have two year, three years. Don't Speaker 2: ask how many year mortgage areas. And you can file Speaker 2: a Chapter thirteen and pay your areas out over five years, Speaker 2: provided you stay current with all your current expenses. Wow, Speaker 2: which again is easier said than done. I have a Speaker 2: young j gentleman who now he has a one hundred Speaker 2: and ninety thousand dollars worth of arrears, and I'm trying Speaker 2: to explain to him that this house that you have Speaker 2: isn't worth ten thousand dollars a month.
But why listen Speaker 2: to me? Speaker 1: How is that? That's interesting to me too, after going Speaker 1: through everything in two thousand and nine, ten, whatever, that Speaker 1: they still have their house at all with that well, and. Speaker 2: You know, I don't know how it is in other states. Speaker 2: In Massachusetts, it takes a very long time to foreclose, okay, Speaker 2: generally from them sending you a notice of default to them. Actually, Speaker 2: you know, some states, the courts are here, the land Speaker 2: court is involved, but it's more mostly pro forma.
You know, Speaker 2: it's here usually a year and a half until they Speaker 2: for until they get around to foreclosing. That doesn't happen overnight. Speaker 2: And sometimes, you know, for whatever reasons, banks. Speaker 1: Won't okay, they just don't want. Speaker 2: To own and you know people why. And the other Speaker 2: the other side of it is that if the homeowner Speaker 2: is inclined to make payments and they have it arears, Speaker 2: the bank won't accept anything less than the payment and Speaker 2: full of the areas.
Speaker 1: Okay, okay, you know interesting And. Speaker 2: The last thing, Chapter eleven is usually for businesses, sole proprietors, Speaker 2: you know, people who are you know, you know they DBAs, Speaker 2: though you can be above the statutory limits for a Speaker 2: chapter thirteen and be forced into a chapter eleven as Speaker 2: an individual, which is a little ridiculous because I have Speaker 2: one now where they're treating my debtor as basically they Speaker 2: don't seem to realize she works a job nine to five.
Speaker 2: She's not running a business. You know, they're from the Speaker 2: government and they're here to help. Speaker 1: Wow. Okay, So I know we talked about, you know Speaker 1: a little bit about bankruptcy not being in being a Speaker 1: reset and so you know, can can you kind of Speaker 1: give a few thoughts around that, like, say you go Speaker 1: through this and it's post bankrupt. Speaker 2: Well, I tell you the best example I can give, Speaker 2: and I know she doesn't mind me talking about it Speaker 2: because she tells clients all the time.
Is my assistant. Okay, Speaker 2: I filed a bankruptcy for she and her husband. Has Speaker 2: to be about ten years ago, maybe long ago. They Speaker 2: still have their house, their credit scores are up in Speaker 2: the seven hundreds now even higher, and they're not missing Speaker 2: a beat. You know, you don't, you know, even though Speaker 2: bankruptcy is a matter of public record, unless you're stupid Speaker 2: enough to talk about it with your friends, nobody knows Speaker 2: about it, you know. Speaker 1: And somebody's on podcast talking about it as well.
Speaker 2: Well, I don't mention any name, but you know that's true. Speaker 2: I can. But you know it's something that you know. Speaker 2: In Massachusetts, it appears in a paper called bank Is Speaker 2: and Tradesmen. Who reads that. I haven't read it in Speaker 2: thirty years. And then when they list the bankruptcy filing, Speaker 2: it's six months after the bankruptcy. Yeah, you know, so Speaker 2: you know most most Well, it's like the same way Speaker 2: if you let's say you're having a going going to Speaker 2: arrange for a wedding, do you know that the wedding Speaker 2: venue was in a chapter eleven.
When you've given the Speaker 2: venue a deposit. Yeah, and when they go out of Speaker 2: business and you don't have their wedding, that's the first Speaker 2: time you find out. So who knows about it? Speaker 1: Yeah? Yeah, you know, I'm curious about somebody. I know Speaker 1: very little about this. I do have a lot of Speaker 1: friends who've been through bankruptcies, and you know that the Speaker 1: big stress post bankruptcy was not being able to get Speaker 1: any credit, having a terrible credit score. Those are most Speaker 1: of the things that seemed to be troubling.
Speaker 2: You'd be surprised that, you know, like I said before, Speaker 2: the credit card companies look at people as post discharge, Speaker 2: they make a decent living. They look at them a Speaker 2: good credit risk. The other thing to do is, you know, Speaker 2: I suggest, which is easier said than done, because I Speaker 2: don't think they exist nowadays, is to try to develop Speaker 2: a relationship with a small bank, maybe a credit union, Speaker 2: that could look at you more as an individual than Speaker 2: a fighter score.
You know, they can see hey, you know, Speaker 2: you know I represented people they were they did masonry Speaker 2: work during COVID, who wanted a mason at their house. Speaker 2: They filed bankrupt you know, you know, it had nothing Speaker 2: to do with what they did with their money. It Speaker 2: was just the business wasn't meant to be at the time, Speaker 2: you know. And then the other thing is there are Speaker 2: collateralized credit cards, which if your viewers, you know, you Speaker 2: can google them and you put the thousand dollars or Speaker 2: five hundred dollars into a CD or a bank account.
Speaker 2: They give you interest on it, and they give you Speaker 2: a credit card. You make the payments. Life is grand. Speaker 2: They don't make the payments, they take your money. The Speaker 2: other thing, and you know, it's an interesting process. You know, Speaker 2: lots of people go through bankruptcies. They own homes, they Speaker 2: own cars, They keep their houses, they keep their cars. Speaker 2: They keep making the payments on the mortgages and making Speaker 2: the payments on the cars. There's a process when you Speaker 2: file bankruptcy.
It's called the reaffirmation of this one of Speaker 2: the reasons I keep cough go on my desk. It's Speaker 2: called the reaffirmation of a debt. And what you're saying Speaker 2: is that I'm agreeing that this mortgage debt is going Speaker 2: to survive my bankruptcy. So if I would just go Speaker 2: through a bankruptcy and do absolutely nothing, I have a Speaker 2: mortgage on my house. I keep making the Moorish payments, Speaker 2: and well, California is a non recourse state, but Massachusetts isn't. Speaker 2: So I could walk away from my house, they could Speaker 2: foreclose and they'd have no recourse against me because the Speaker 2: debt was discharged.
Follow what I'm saying, even though I'd Speaker 2: been paying it for eight years. Speaker 1: Okay, okay. Speaker 2: A reaffirmation avoids that situation, mostly for the bank because Speaker 2: now if you reaffirm the debt, which the court has Speaker 2: to approve, it survives the discharge and you can't tell Speaker 2: the bank see you later after eight years. You'd still Speaker 2: be on the hook if there was a deficiency. And Speaker 2: how I found out that was a client of mine. Speaker 2: And when the computer businesses collapsed in the oughts, he Speaker 2: had a house that was completely underwater.
He couldn't reaffirm Speaker 2: the house. There would be no way. He wasn't worth Speaker 2: he had no income. Yeah, ten years later he calls Speaker 2: me up. He'd been paying the mortgage for all ten Speaker 2: years and he had never reaffirmed it, but the mortgage Speaker 2: rates had gone down, and he called up his bank Speaker 2: and he said, listen, I'd like to reaffirm my mortgage. Speaker 2: I've been paying you for ten years. I have a Speaker 2: good record. They said to him, well, you discharged the bank, Speaker 2: the mortgage, and your bankruptcy.
He said, I've been paying Speaker 2: you for ten years. What do you mean I discharged? Speaker 2: Technically he did. Interesting, and he wound up going to Speaker 2: another bank. But I never realized. I wound up not Speaker 2: to blow my own horn. I wound up drafting legislation Speaker 2: in Massachusetts to at least, well, the legislature has better Speaker 2: things to do than my statute, but to require creditors Speaker 2: to at least report that payments were made here. It Speaker 2: made it seem like he hadn't made it a payment Speaker 2: for ten years.
Speaker 1: So interesting. So he was still in the house making Speaker 1: the payments. Speaker 2: Living there, making the payments, but they wouldn't refinanced it Speaker 2: because according to their credit report, he discharged the banquet, Speaker 2: the dead and bankruptcy. Speaker 1: Well, I don't know what that's what says, you know, Barry, Speaker 1: this is really making me. I want to stress the Speaker 1: point that you need a good attorney. I mean, you Speaker 1: can't necessarily rely on your tax accountant or whoever to Speaker 1: advise you in this arena.
And like many things money, Speaker 1: there are a lot of options and a lot of Speaker 1: things to talk about, and we tend to limit ourselves Speaker 1: by not having enough knowledge or speaking to the right Speaker 1: person about what to do here. And somebody with a Speaker 1: lot of experience like you, who clearly is passionate about Speaker 1: this world, is just going to be able to think Speaker 1: for you. Speaker 2: And you need somebody who you know. It's like I Speaker 2: don't you know, It's like when I have to but Speaker 2: very rarely do I go into district court in Massachusetts.
Speaker 2: I'm like a foreigner, you know. And it's the same Speaker 2: thing in the bankruptcy court. There are people who were Speaker 2: there all the time. We know the players, I know Speaker 2: the trustees. You know, you know what you can do, Speaker 2: what you can't do. You have a sense of things, Speaker 2: and it works an advantage for you. You know, you Speaker 2: don't want to be the guy that you know, he's Speaker 2: doing your first bankruptcy after he did your first divorce. Speaker 2: I mean, you know it's not necessarily good.
Speaker 1: So yeah, and you know this is interesting too. The Speaker 1: time we're in right now, do you have any predictions Speaker 1: on you think they're going to be more bankruptcies. Speaker 2: I have been busier since January of twenty twenty four Speaker 2: than I have been in almost a prior twenty three years. Speaker 2: It has been insane. Wow, phones are ringing NonStop. I mean, Speaker 2: and I'm filing cases age wides for the whole gamut Speaker 2: from you know, kids in their early twenties who decades Speaker 2: ago I would say, maybe you want to think about Speaker 2: something else, but now get on with your life, to Speaker 2: people in their eighties, and you know, you know it's Speaker 2: not something I should say.
But when somebody's in their eighties, Speaker 2: you'll probably die before they'll sue you. So why you Speaker 2: want to file a bankruptcy. But on the other hand, Speaker 2: it's you know, bankruptcy for people is peace of mind. Speaker 2: You know. The best thing for my business is collection Speaker 2: agencies because they make people think. You know, lay people Speaker 2: don't necessarily realize how the system is meant to be Speaker 2: jerked around. You know, they used to be a comedian. Speaker 2: I don't know if you well, maybe you remember when Speaker 2: you used to travel in Europe.
Know when I a Speaker 2: long time ago went to Israel. If I needed money, Speaker 2: my parents could send money to the American Express office Speaker 2: and is right okay? In Europe in Paris, and what Speaker 2: he used to do with his bills, he would fote Speaker 2: them to the American Express offices around the world, and Speaker 2: by the time they made a complete circle, they went Speaker 2: back and he never dealt with his bills. Wow. But people, Speaker 2: you know, when creditors look to collect, the system is Speaker 2: built to delay because, first off, the creditor itself doesn't Speaker 2: want to let the collect case go to a collection Speaker 2: agency because now if they're going to collect, they have Speaker 2: to pay somebody, and they will nudge you.
And you Speaker 2: know people may have got those letters. If you dispute Speaker 2: this amount, it's a credit card, there's nothing to dispute. Speaker 2: Does it cost you to send a letter? I always Speaker 2: send a letter and you dispute it. They then have Speaker 2: to send you every invoice to prove the account. Now, Speaker 2: after the creditor you ignore them for months, they send Speaker 2: it to a collection agency. Collection agency, all they can Speaker 2: do is nude you some more because they'll send you Speaker 2: the same letter and what do you do You send Speaker 2: the same answer, I dispute it.
Now they have to Speaker 2: go back to the creditor, get all the bills and Speaker 2: send them to you. Eventually the collection agency will get Speaker 2: fed up and they'll send it to a lawyer. And Speaker 2: I just had a case now where they were hysterical Speaker 2: because the creditor sued them in utah Nelig in Massachusetts. Speaker 2: Who cares? So even if they sue you, the attorney Speaker 2: will send you that letter again. If you dispute the balance, Speaker 2: send us a notice writing. You send it in writing, Speaker 2: and now months down the road and then so now Speaker 2: they sue you.
You know, I used to because listen, Speaker 2: in a perfect world, people file bankruptcy right away. But Speaker 2: it's not a perfect world. It takes time. You know Speaker 2: the jokes. You need money to file bankruptcy, so it Speaker 2: takes time. And you know, I used to do pro Speaker 2: say answers for my clients so they could just defend Speaker 2: the case to keep you know, but they eventually get Speaker 2: tired because all the collection firms they send demands for interrogatories, Speaker 2: that demands for this, but the collect But I only Speaker 2: concern myself with the collection process is when they get Speaker 2: a judgment and now they try to act on the Speaker 2: judgment because like in Massachusetts, there's a process called supplementary process, Speaker 2: which is like debtors caught.
Okay, if you don't show Speaker 2: up and you get pulled over for speeding, they issue Speaker 2: a KPIs for your arrest, sorry and to me, that Speaker 2: is the worst because now you're tooling down the mass Speaker 2: Pike and you're the state troop is bully over. But Speaker 2: that is so far down the road in litigation that Speaker 2: if you're thinking of filing a bankruptcy, you'll have gotten Speaker 2: your discharge before that will happen. Speaker 1: Okay, Yeah, it's really interesting. So there's a lot of Speaker 1: you know, I mean, I'm going to go out on Speaker 1: a lim and say if you can, you know, if Speaker 1: you've got some debt and you can pay it, you Speaker 1: should pay it.
If you can't pay it, do you Speaker 1: just use these delayed tactics? Do you pay it as Speaker 1: soon as you get I mean, what's the best way Speaker 1: to go if you're really in trouble here? Speaker 2: You know, what you what you really have to decide Speaker 2: is if you're going to file a bankruptcy or not. Speaker 2: You know, once, once you've determined you're going to file Speaker 2: a bankruptcy, paying anything, paying minimum pay moments at least, Speaker 2: in my opinion, is a waste of time. I mean, Speaker 2: if you're an assetlest case, it's not going to make Speaker 2: a difference, you know, And I don't you know, again, Speaker 2: getting back to what I think I said earlier, is Speaker 2: it's more important to put food on the table and Speaker 2: gas in the car and pay the rent, you know.
Speaker 2: And that's to me what it comes down to. If Speaker 2: you find that. You know, I've had people come to Speaker 2: me after I pay off all my creditors, I have Speaker 2: twenty dollars a month left over. It's insane. Speaker 1: Yeah, yeah, yeah, you know. Speaker 2: They don't give you, you know, the thing a creditor Speaker 2: you pay them on time. I have so many people Speaker 2: they pride themselves and paying them on time and paying Speaker 2: them on time. You miss a payment, they up the Speaker 2: interest rate to twenty eight percent.
They don't give you Speaker 2: a gold star why box, Yeah, you have to, you know, Speaker 2: I I've reached the point where my age credit score. Speaker 2: Who cares? Speaker 1: Well? Speaker 2: I like I like the. Speaker 1: I like the way I mean you're not obviously, this Speaker 1: is your livelihood. So this isn't a small thing to you. Speaker 1: But off the street you're lightening it up for people, though, Speaker 1: which I think is important. This is a very very heavy, Speaker 1: heavy thing to think about, and we think about it Speaker 1: way too long.
From what I'm hearing from you, and Speaker 1: you know, I really love that you said bankruptcy is Speaker 1: peace of mind. I've never thought about that before bankruptcy Speaker 1: to me was a huge, you know, black mark on Speaker 1: your life. You know, so I think it's really important Speaker 1: for people to hear this message. Speaker 2: No, it's it really like I said, getting back to Speaker 2: being an indentured servant. You don't want to live that way. Speaker 2: You know, you want to be able to listen. If Speaker 2: you you want to go out to dinner one night, Speaker 2: you don't have to worry about paying Bank of American Speaker 2: unless you're using their credit card, which you know that's Speaker 2: the story for another day.
Speaker 1: Wow. Okay, well, Berry, we are close to the end here. Speaker 1: I'd love for you to just maybe mention, you know, Speaker 1: just summarize a cup of key things for people who Speaker 1: sure Actually I'd love for you to give people a Speaker 1: couple of key things to still avoid bankruptcy. No offense. Speaker 1: But if there's a couple of you know, lights flashing Speaker 1: in your life, you know, what can you do to Speaker 1: just mitigate that potentially? Speaker 2: You know, right now it's I happen to think it's Speaker 2: very difficult because there are there's no way, you know, Speaker 2: the years ago, I mean I remember credit card companies Speaker 2: would call up clients and say, I see you have Speaker 2: a line of credit.
With ten thousand dollars, why don't Speaker 2: you use that and pay us off? Okay, but that Speaker 2: doesn't exist. And for instance, you know people who have Speaker 2: mortgage areas, so they'll get refinancing, but the bank will Speaker 2: say you have to cure the areas before we'll give Speaker 2: you the financing. Does nothing for them, you know. So Speaker 2: I think the only thing nowadays is is best to Speaker 2: plan ahead, to know where your exposure is, what the Speaker 2: worst case scenario for look will look like if the Speaker 2: shit hits the fan, and from that you just have Speaker 2: to pay attention, you know, you have to.
You have Speaker 2: to set deadlines for yourself. You know. You you can Speaker 2: say I'm going to continue to throw money into the business. Speaker 2: You know eventually that runs out. You know, the four Speaker 2: one K isn't going to be there anymore, the IRA Speaker 2: or the relatives and the other thing you know, I Speaker 2: didn't even mention that though, is that, you know, if Speaker 2: you have a small business, something to do is consider Speaker 2: if if you views the friends and family to borrow Speaker 2: money for your business, to consider making them creditors in Speaker 2: the sense that they shouldn't.
Why shouldn't they be like Speaker 2: a bank. So now a good friend viewers has lent Speaker 2: your business one hundred thousand dollars, you give them a Speaker 2: security interest. So now if the shit hits the fan, Speaker 2: you could contemplate maybe a friendly foreclosure with them foreclosing Speaker 2: on your business and selling it back to newco. I Speaker 2: know that's another subject altogether, but you see what I'm Speaker 2: I just thought of that. Speaker 1: Yeah, yeah, Well that's the beauty of this is you Speaker 1: can think up you.
Speaker 2: Know, because very often, you know, you know people because Speaker 2: like I said, when people come to me and I'll say, well, Speaker 2: you have this business. Has anybody lent you any money? Speaker 2: You know, if we're at an insolvent point. The difficulty Speaker 2: about putting mortgages on is there has to be collateral Speaker 2: consideration given. And you know, for an insider it's a Speaker 2: year before filing. It's a preference, you know, Birdie made Speaker 2: off stuff. And for a non insider, which is a friend, Speaker 2: it's ninety days.
So even if you would you know, Speaker 2: if you do it when they lend you the money, Speaker 2: that's fine contemporaneous, but if you decide to make them Speaker 2: secured after the fact, you have to wait another ninety Speaker 2: days before they're perfected. Okay, that's not that I've confused everybody. Speaker 1: Well, it's interesting because people for small business do borrow Speaker 1: from friends and family, absolutely absolutely, and with that is Speaker 1: really smart. Speaker 2: Well, too often they don't realize that their friends and Speaker 2: family can be banks like anybody else, and why shouldn't Speaker 2: they be?
Speaker 1: Yeah, wow, super interesting. Okay. Well, one thing that's been Speaker 1: bothering me this whole time is whether or not I Speaker 1: pronounced your name your last name properly? Is it Levine Speaker 1: or Levine? Speaker 2: Oh, don't say Levine, It's Levine? Speaker 1: Good, all right, I did it right then. I don't Speaker 1: know why that was bugging me, but yes, And do Speaker 1: you work with people outside of Massachusetts? Can people? Speaker 2: You know, I've occasionally consulted with people outside of Massachusetts, Speaker 2: but I would look to get the local council because, Speaker 2: you know, while the things I discuss there's nothing new Speaker 2: under the sun.
You know, my uncle was talking about Speaker 2: doing this stuff in nineteen forty when he was practicing Speaker 2: law in New York. But you know, you're better off Speaker 2: having somebody local who knows the ins and outs. You Speaker 2: know that I wouldn't know. Speaker 1: Okay, And so you have your own podcast. What is Speaker 1: that called? Speaker 2: It's a bankruptcy through the looking Glass. It's the book Speaker 2: I wrote about it, and you can find my podcasts Speaker 2: on YouTube. Speaker 1: Okay, great, And then what about your book?
Speaker 2: My book is on Amazon Bankruptcy through the Looking Glass, Speaker 2: and you can there's some place you can download a Speaker 2: free copy. I have no idea where. Speaker 1: But maybe on your website. Speaker 2: That could be. Speaker 1: Too busy for that to know those things. And what Speaker 1: is the book about exactly? Speaker 2: It's about the reality of bankruptcy. Here's actually something people Speaker 2: should read because you know, because you know, because the Speaker 2: thing is, you know, the three forty one meeting, the Speaker 2: meeting of creditors.
And when I tell clients that the Speaker 2: anxiety of the three forty one meeting is a hell Speaker 2: of a lot worse than reality, they don't believe me. Speaker 2: And then they come to the three forty one meeting Speaker 2: and I'm basically dressed like this or I'm wearing my Speaker 2: T shirt that says I saw Jerry, and they want Speaker 2: to know why I'm kidtzing with the trustee. And we'll Speaker 2: make cracking jokes and I know these guys. We tell Speaker 2: stories and oh, by the way, here are the questions Speaker 2: we ask and five minutes later we're done, and they go, Speaker 2: that's it.
Yep, the ritual sacrifice I tell them about later. Speaker 2: We don't like to get into that right away. Speaker 1: You know, I this is so many things. Money are Speaker 1: so much scarier in your mind than they are in Speaker 1: real life. And I feel like you did a very Speaker 1: good job today helping people see this around this very Speaker 1: scary topic. So you know, not that it's something we Speaker 1: are looking forward to or anything, but thank you for Speaker 1: my pleasure, the myths and yeah, making it seem like Speaker 1: a different kind of option for people and possibly a Speaker 1: really good one for peace.
Speaker 2: Of mind to me. You know, if you find yourself Speaker 2: in that situation, it's the best way out because otherwise Speaker 2: it's shoveling shit against the tide. Speaker 1: Okay, yeah, thank you. We'll wrap on that. Speaker 2: That's correct. We'll take care everybody. Speaker 1: And I really appreciate your time. This was really great Speaker 1: and audience, thank you, Thank you for showing up for Speaker 1: the money and new show. We love it. When you Speaker 1: watch the show, you can listen to it on all Speaker 1: the podcast platforms on the Limit Free Life YouTube channel, Speaker 1: and please share it with a friend.
I bet you Speaker 1: know somebody who may even be contemplating bankruptcy right now. Speaker 1: That would be great to forward this to them, give Speaker 1: them some resources, let them know about Barry's book, and yeah, Speaker 1: just keep this in your arsenal financial knowledge so that Speaker 1: you have of a wide array of ideas around you. Speaker 1: Know your finances and your business, and so you can Speaker 1: feel a little more financially free just knowing more than Speaker 1: you did. So thank you so much, and we'll see Speaker 1: you next week.
About Barry Levine
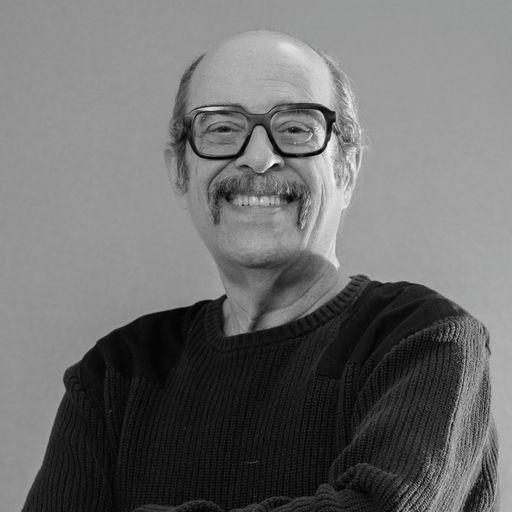
Bankruptcy Attorney and Debt Strategist for Everyday Americans in Crisis
45 years Representing people in financial difficulty1 book Author, Personal Bankruptcy Through The Looking Glass322 videos On his own bankruptcy YouTube channelBankruptcy attorney Massachusetts
The calls often come late: someone has ignored letters from the IRS, missed too many loan payments, or watched their small business slowly bleed out. They don’t open with legal questions. They ask if there’s any way out.
For almost 45 years, Barry Levine has answered that question with calm, practical guidance. A Massachusetts-based bankruptcy attorney, he works with individuals and small business owners navigating serious financial strain, people who are scared, out of options, and unsure what the next step even looks like. His work isn’t about judgement or quick fixes. It’s about helping people understand what tools are available, how the system works, and what choices they can still make.
What Barry sees again and again is that fear, not just debt, is what traps people. The legal process has structure, options, and predictable outcomes; what derails most clients is the panic that keeps them frozen in place. Barry’s role is to bring order to the chaos. With each case, he applies decades of legal experience to help clients understand what’s happening, what’s possible, and how to move forward with a strategy that restores both stability and control.
He first started practicing bankruptcy law in a hands-on Boston office while still in law school, learning case by case how to navigate both paperwork and people.
More from Barry Levine
All episodes → The Agent of WealthFinancial Crisis, Bankruptcy and Starting Over With Barry LevineOct 2026Play episode →
 School for Startups RadioOctober 5, 2026 – EdTech Find Your Grind Nick Gross and Bankruptcy Attorney Barry LevineOct 2026Play episode →
 Financial Mastery SimplifiedHow Bankruptcy Really Affects Your Credit and Home LoanSep 2026Play episode →
 Money Talk With TiffWhat Bankruptcy Actually Does with Attorney Barry LevineAug 2026Play episode →
 Wealth B-HersFear, not Debt with Barry LevineJul 2026Play episode →
 Us People PodcastThe Law We Decide To Practice - Barry Levine - Attorney At Law #314Apr 2026Play episode →
 Chrisman Commentary - Daily Mortgage News4.14.26 Fines Versus Taxes; Attorney Barry Levine on Delinquencies and Foreclosures; Agency MBS PerformanceApr 2026Play episode →
 JUSTIN AND THE [FOOD] ENTREPRENEURSEpisode 520: Barry Levine of The Law Offices of Barry R. Levine - Beverly, MA. Shielding Your Personal Assets. Avoid Bankruptcy Before It Hits. Legal Lifelines for Food Entrepreneurs. Cost Accounting.Apr 2026Play episode →
 How Much Can I Make? — Real Jobs. Real People. Real Money.Bankruptcy Lawyer Explains Chapter 7, Chapter 13 & Getting a Fresh StartMar 2026Play episode →