
November 24, 2025
Bankruptcy Without the Panic with Barry Levine
In this episode
Barry Levine talks about bankruptcy for business owners, including how debt, business structure, and repayment choices affect what happens next.
- Entrepreneurs often wait too long to face mounting debt, then have few options left.
- Chapter 11 requires monthly cash flow statements showing how the business is operating.
- A sole proprietor may have no clear separation between personal assets and business assets.
- Bankruptcy can discharge some debts while reaffirmed loans, like mortgages or car loans, continue after the case.
- Student loans may be dischargeable now if the debtor shows good faith effort and meets current guidelines.
Transcript
ShowHide
Automatic captions of the conversation. They can contain errors and do not name who is speaking.
But once COVID was over, the whole economy changed. People weren't doing things the same way. And now they find that, well, the business survived COVID, but it can survive now, and they're stuck with the SBA loan. Financial independence, freedom, financial picture, independent financially, financial future, financial freedom and wealth, financial independence, Get Your FILL, Financial Independence and Long Life. Hello, and welcome to another episode of Get Your FILL, Financial Independence and Long Life, where we explore ways to achieve those two goals, and people come on to help us, who in this case might be helping us before we get to that point where we're able to kind of refine financial independence.
But this can be an important step to getting there. So for almost 45 years, Barry Levine has answered the question. So it says, that's your intro says, answer that question. What's the question, Barry? The question generally is, when I'm facing all this debt, what do I do with it? Okay, perfect. There's no right answer and there's no wrong answer. The unfortunate thing with people, especially entrepreneurs, is they tend to hold out and not realize the handwriting is on the wall until it's too late. Then there's very little you can do.
It's a tough situation. Well, like we were chatting, the entrepreneurs are generally optimistic. I think you have to be, right? I'm an inveterate cynic, so it comes with the territory. But the most difficult thing you have in getting across to some of these people when times are tough, is that it is what it is. You have a half a million dollars worth of debt and you're making no money. What are you going to do about it? What they very often do is they'll use the equity in their house, they'll take money from their 401K and this, which is really not the best thing to do.
But who listens to people who know what they're doing? Not me. Well, as an entrepreneur, I will tell you, you have to be an optimist because otherwise you would easily and people do it all day long. Everybody has a business idea and a lot of them manage to talk themselves out of it. Well, years ago, I don't know how familiar you are with Chapter 11, but when you file a Chapter 11, the debtor has to file cash flow statements to show how they're operating in every month. Many decades ago, actually, I think that's where the new ballpark they built out in Worcester is now.
I represented a guy who was in the plastic business, and his business was like zero. His cash flow statements were just, but business was great. He was working, he wasn't making any money, but he didn't last very long. He fortunately had a bankruptcy court judge when you asked him to take a matter under advisement, it took him a year to issue an opinion, so he worked out okay. But yeah, optimism is the nature of being an entrepreneur. Like I said, I'm a cynic, so it's tough for me to understand. But what I always point to is you'll see a restaurant at a location.
There have been nine restaurants there. None of the restaurants have lasted more than a year, but the 10th guy is going to open the place up, figuring he's going to succeed. I guess it's American, I don't know. It's the location, hello. Nobody walks by, but they're going to make a business, make a fortune. Right, people are going to come out of the woodwork. Well, I mean, right, everybody thinks they have to think, you know something that nobody else knows, or you have an idea that nobody else has ever had before, right, or something, there's some differentiator that you have, because otherwise, like I said, you'd be able to easily, anyone can easily talk themselves out of being an entrepreneur, because it's easy.
It would be very easy for me. Well, listen, you know, the typical, you know, I wouldn't shouldn't say typical, but I know I set up corporations for people, and I prefer corporations to LLCs, but that's another story. But when I ask how much stock do you want, I generally authorize a thousand shares of stock and issue 100. They want 100,000 shares of stock. I said, what is it going to do? Sell it? I mean, it makes you happy. Here's a certificate, it says 100,000 shares, but it's meaningless. You know, it's only what's in the bank that matters.
Exactly. What does this thing have any value? So a question that I kind of popped into my mind when you were talking about businesses filing for bankruptcy, is there a difference between my business filing for bankruptcy and me personally filing for bankruptcy? Well, there should be if you don't operate as a sole proprietor. See, when you operate as a sole proprietor, which I remember when I was in law school, actually he was the dean at the time, he believed that people shouldn't set up corporations, you should operate as a sole proprietor.
And the unfortunate thing about that is you can't distinguish if I'm a sole proprietor and I own a house, how do you distinguish between my house and my business assets, it's one and the same. But with respect to businesses, they generally, well, there are other ways to reorganize businesses outside of a bankruptcy, but the tried and true measure is the chapter 11, or if you're a small business, what they call the sub-chapter five, small business chapter 11, both of which are pains in the asses. They're very time consuming.
I have two small business cases going on right now that don't ask. But it gives the debtors an opportunity theoretically to freeze everything in place and see how they operate without this creditor nudging them for a check and this creditor bothering them for money. The unfortunate thing is, decades ago when we used to do Chapter 11s, we used to propose a plan that made the first payment due in a year. Well, the judges quickly wised up because most Chapter 11s don't make that year. So we had to pay them something right away.
Now, if they last a year, they're doing well. I mean, Chapter 11s are very difficult. Unfortunately, there are certain things that you have to file a Chapter 11. I mean, if the IRS is coming to seize your assets, the only way you can stop that is the automatic stay that you get in a Chapter 11. If the secured creditor with respect to a business or a home foreclosure is going to foreclose, you file a bankruptcy because it stops that in its tracks, it also stops litigation. It doesn't necessarily solve the problem, but it gives the debtors time to breathe, and hopefully, they can work things out.
You've mentioned alternatives to Chapter 11, alternatives to bankruptcy. Let's talk about some of those. Let's say that because I know this has happened to people, let's say I'm a small business owner and I had great plans and expectations, and maybe it's just that my cash flow isn't good. Maybe one of my big customers isn't paying or, right? There's just something going on and I just can't keep my head above water. What are some alternatives that I could have to actually filing for bankruptcy? It goes back to, you know, you can do what's called a composition agreement, which is like cutting deals with all your creditors.
People don't really do that. There's also what's called a trust mortgage where you solicit all your creditors. You know, you give them a nice schmaltzy story about what's going on, and this business problems and this, that and the other thing. And the trust mortgagee takes a promissory note that the debtor pays and distributes to the participants in the trust mortgage. You know, that's something you may go through, may not go through what I've been doing since, well, you can't see my picture up above me when I had a lot of hair.
Yeah, but since I actually, while I was in law school, I work for a gentleman who all the collection attorneys and creditors attorneys in the Boston area hated him. They couldn't stand him. And unfortunately, what they hated about was that he did a very good job for his debtors. He kept them in business. And what we do and we've been doing and not everybody agrees with this, but in Massachusetts, there are three ways to liquidate a company. You can file a Chapter 7. In a Chapter 7, I don't recommend that for small businesses because it's intrusive.
There are things such as preferences. You may have made off, clawbacks, what they call them or whatever it was, where a trustee can recover money from the principal who's paid himself. Let's say the principal has a creative accountant and says, well, why take salary? You've lent $100,000 to the company, take it out as loan repayments. Well, if you file a bankruptcy, those loan repayments can probably be determined as preferences, and a trustee can recover them from an insider up to a year. Very often, especially in closely held corporations, the line between the corporation and the individuals in a bankruptcy gets blurry.
The other alternative is what we do very often. It's called an assignment for the benefit of creditors. Massachusetts allows companies to do a voluntary liquidation. It's basically a paper transaction. And what happens is the assignee, who's an attorney, it doesn't have to be, is under an obligation to liquidate the assets in a commercially reasonable manner. And basically the same way it happens in a chapter 11, how you determine what creditors are gonna get, the assignee appraises the assets and will sell the assets back to Newco for either the assumption of secure debt that's already existing on the corporation and a little promissory note so the creditors get more than nothing or a note for the value of the collateral.
And what happens then is notices then go out to all the creditors. And it's like, this is what happened. Have a nice day. They have a choice to was sent. Because basically if they decide to chase, they're chasing a corporation that has no assets. So what's the point? What that is the difficulty in dealing with creditors is they don't necessarily get that point. If they're no assets, they're no assets. There's nothing you can do about it. When somebody, some supplier extends $300,000 worth of credit to a business that you would never want to do anything like that to.
And then six months later, they stop getting payments. You know, who's really at fault? You can't blame the debtors. I mean, if somebody, well, I don't know if you remember when they were building up what is now the computer area in Cambridge, right along the Charles there. I can't think of the name. But landlords were offering these high-tech companies, and this was right when the high-tech companies all went down the dumper, signing fees to sign leases, giving them hundreds of thousands of dollars. They didn't do an analysis of what the, some of the, we had one guy, he owed the IRS half a million dollars.
Landlord lent him 300,000 and six months later, he went out of business. I mean, whose fault is that? I mean, I hate the phrase due diligence, but sometimes you have to look. Yeah, it seems like it makes sense. I don't know. So in those cases, the business is destroyed obviously. So there's no opportunity, you know, like in the scenario I give where the person, the cashflow is going to improve at some point, this client is eventually going to pay or whatever. So I don't know, I wasn't clear that any of those scenarios allow that person to stay in business.
With the assignment, we call it a dump buyback, for lack of a better word. But with the buyback part of it, it enables them, you know, the appeal to the suppliers and creditors is, well, if the guy went out of business, he owes you 10, 20 grand, you're never going to see a dime. You know, he's been with you for a number of years. If you allow him to go forward, you may make money back going forward. You know, so what you really do for these people is you sort of burden the cash flow, you know, their demands, they don't have any debt.
You know, maybe they have the ass and ease note or the secure debt that you can't get rid of. And then it's a matter of them making money. You know, unfortunately, I mean, what's really, I found a lot of, and I don't know if you've heard from people, is that during COVID, when the government, through their largesse, was so nice in giving people SBA loans, that what I'm finding is a lot of these SBA loan recipients, you know, it got the business through COVID. But once COVID was over, you know, the whole economy changed.
You know, people weren't doing things the same way. And now they find that, well, the business survived COVID, but it can survive now. And they're stuck with the SBA loan. And, you know, what we're doing, I've been doing a lot of is, you know, you don't have to do with respect to liquidating a company. I find for closely held businesses, the assignment is a better way, because nobody, there's no 341 meeting, there's no real, you know, it's not the same sort of, the debtor isn't put under oath, it's a paper transaction.
And if they're assets, we call in an appraiser, auctioneer, we use the Paul Sappistine company, you may have heard of them, they've been around. I get their emails every day, or whenever they have something. 75 years or something. And they do a public auction, and then you make a distribution to the creditors. I mean, it's a lot less intrusive. And you know, the unfortunate thing about it is the principles wind up filing bankruptcy too, because they generally have guaranteed the SBA or this bank or that bank. And you know, what usually goes along with the financial problems of these businesses, they either owe, you know, sales tax, meals tax, withholding tax, you know, which I tell people if you have to do that, because, you know, for businesses that are having financial problems, the easiest cash flow to dip into is the employee withholding.
You know, you're supposed to withhold it. Nobody's sitting there with a gun saying, pay it to the government. And, you know, you'll find that that's what happens is now that not only do they have all this other debt, but they have, you know, 50 or $100,000 of unpaid withholding that they're personally on the hook for as the president of the corporation. And that, unlike income tax, which can be discharged in certain circumstances in a bankruptcy, trust fund taxes, you either have to try to wait them out. They have a 10 years collection statute and you would be surprised at how it's, it's not that difficult to outweigh them.
I've had a couple of success stories, you know, cause the thing is when they have a 10 year collection statute, the IRS, as does the DOR, and the IRS, their liens are good for 10 years. They never renew their liens. So what happens if you wait out the 10 years, it becomes, you know, it will be on the title if somebody does a title exam, but under the title standards, you know, it's of no consequence because it expired. And surprisingly, even though they have very good press, the IRS, I mean, I just had a gentleman, 400,000 unpaid withholding, but 10 years was this past summer.
You know, you have to have patience. I call it lawyer time, you know, it takes forever. So they couldn't sell their house or whatever, whatever the lien is on, and they wouldn't be able to sell it. You can sell the house with the lien on it. There is a way. You have to charge it, right? Well, there is a way, and there's a process whereby you submit several appraisals to the IRS and show them that there's only gonna be so much money available for them, and they generally will release their lien upon the payment of whatever that equity is.
The folks you really don't want to deal with is the Mass Department of Revenue. They're a lot more difficult to deal with than the IRS. They suspend people's licenses if you owe them taxes, which in Massachusetts, if you haven't been able to tell, I'm from Brooklyn, and if you don't have a car in Brooklyn, who cares? You can get any place, but you live in who knows where, Drake it, and you don't have a car, where are you going to go? How do you find a job? I've had these conversations with the revenue offices, and it's like they have no answer for me.
You force these people to drive without a license because they want to make a living. Right. If they want to ever be able to pay back, they kind of have to go to work. Well, that's the basis for the offering compromise when you owe money to the IRS. You know, you may have seen those ads, settle your tax claims for 10 cents on the dollar and all this other stuff. It's not that simple, but it can be done. You know, the IRS looks at people, they tend to look at people who owe taxes like any other creditor now. You know, if there's no reason to keep it on the books, if they're never going to get paid, like I said, the 10 years will expire and then it's meaningless anyway.
So how does this impact, we hear people talk about, when you do your bankruptcy, it ruins your credit. What's the impact on people's, especially if it's a business bankruptcy? Well, the business bankruptcy, business bankruptcies are usually followed by personal bankruptcies because there was a time many decades ago where you could take out a bank loan and you didn't have to guarantee it or something like that. But those days are long gone and like every business has an American Express card account and they give the employee or whomever has the card, the card, they're personally liable on that card if the business goes down the dump.
So, you know, it's not the end of the world when you file a bankruptcy. It's not as easy as it used to be like before the banks imploded in 2008 or something like that. You know, now you will get credit card solicitations after you file because it was one of the reasons I keep Kafka on my desk, because believe it or not, creditors consider a post-discharge debtor as a good credit risk. Because they can't file bankruptcy again. They can't file again for eight years. You hit the nail on the head. So they'll give people, excuse me, they'll give them a small line of credit.
They make the payments and like everything else progresses. The other thing I suggest to post-discharge debtors, which nowadays is easier said than done, is to try to develop a relationship with a smaller bank that can look at you more as an individual than a FICA score. The thing is, back in, when I started doing this in 1980, there were games players, there were people who figured they could go. You must remember Leachmere Sales, that shows you how long I've been here. They could go to Leachmere and buy stuff and not have to pay for it and all this crap.
But over, I think for the last 30, 35 years, it's either people who lost a job, have been downsized or had medical expenses and not covered by insurance. Those are the typical. I've had people come to me and recently had a couple. He didn't have to file, but they were both very high earners. She was making about a quarter of a million dollars a year. One day, she went to work and lost her job. She became a contract worker, no benefits, working for three months or four months. When you make that money and you have the debts, and on top of that, they had two developmentally challenged children that cost them a lot of money.
What else were their credit cards for? You have credit cards, there's a reason. So she had to file a bankruptcy because she couldn't make the payments. And then to add insult to injury, the trustee's office, which is an arm of the US. Attorney, the Justice Department, tried to deny her discharge because she was a high earner. She had a lot of debt and we ultimately prevailed. She did a very good job of her own research, explaining how all the extra debt that they incurred to support their children's educational and health needs was justified under federal statute and she got a discharge.
But, you know, that's a typical, you know, most of them, it's not difficult. Most of them, they just get their discharge. But, you know, that's a typical debtor. You know, if you're making a couple of hundred thousand, you can pay a certain amount of debt. If you stop making it, what can you pay? 26% interest. Yeah. So, I know some people, their financial issues are tied to student loan debt. But, is that not dischargeable? Well, actually, things have changed, you know. Back about, oh God, probably 10 years ago when people would ask me about student loans, I'd say, walk in front of a bus.
Take the green line, walk in front of the green line. Basically, you had to die. But recently, they've issued new guidelines, and I've had two recent successes with discharging student loans in bankruptcy. They now look at whether you've made a good faith effort to deal with your student loans. So, in other words, if you've told them to pound sand and ignored them and not done anything, they're not going to give you the benefit of the doubt. But now, most of these people, they are on deferments, they're on, what do they call it, income-derived payment plans.
And if you show that you've called your loan services to tell them, you've, I've had two student loans, two debtors, that student loans were discharged. And I have two more pending, where they also look at the age of the student loans. I know my student loans were the seven-year loans that took forever to pay. But thank New York State, but I don't like to tell people what I paid for tuition when I went to law school. It makes them nauseous. I'll tell you anyway, it was $2,000. Crazy, right? You can't, I think it's like an hour now that you go through $2,000 in an hour.
Well, when I was in college, my room and board, and when I lived off campus, I think was $1,000 a year. And we had cable TV, we used to have the paper delivered. Once a week, we ate steak. But now, I mean, when I see what tuition is, both at undergraduate or law school, I mean, $80,000. Yeah. Bro, putt. I mean, makes more sense the better way to spend the money. Yeah. Because this is a thankless business. Getting back to, is it the end of the world? Oftentimes, getting back to student loans, people who go through bankruptcy will have mortgages that they continue to pay.
They'll have car loans that they continue to pay, and that all stands them in good stead. If they, what's called reaffirm the debt. And by reaffirming the debt, it means it survives the bankruptcy. So the interesting getting back to Kafka on my desk, if you don't reaffirm the debt and you continue making the payments, it's as if you've made no payments at all. According to your credit report, it will say that the debt has been discharged at a bankruptcy. Oh, wow. So that's a process, this reaffirming the debt is some kind of process you have to go through.
Well, reaffirming the debt, when you file a bankruptcy, and I know we're going all over the place, but when you file a bankruptcy, let's say you have a car loan, and you get your discharge, you discharge any potential deficiency of that car loan. You know how that comes about, if you default on the loan, they auction off the car and you're liable for what the difference is, what the car brought in and what you owe. When you go through a bankruptcy and do nothing, even if you just keep making the payments, you discharge that deficiency.
Theoretically, the problem people, this probably applies to entrepreneurs is car lenders, car dealers are so nice, they'll take somebody's car that has no equity in it, and they'll get them out of that car and put them in a newer car that even has less equity in it. Now, I find you see these kids driving $15,000 cars with $40,000 loans on them. So the thing about reaffirmation is, you wouldn't want to reaffirm that debt, because why would you want to reaffirm a $40,000 debt on a $15,000 car that may just last another year?
You want to be able to walk away from that. On the other hand, if the car is balanced, then you're looking to improve your credit, then you want to reaffirm it, because again, I mean, how I actually, it was interesting how I found out about that, is that, see, we don't know everything, that a gentleman was in a computer business, I think it was 2007 or 2008, it went down to Delta. He had a house someplace in the South Shore that was, it was like worth $300,000, it had $800,000 in mortgages. He wasn't making any money, there was no way the court would allow him to reaffirm the debt.
And he just went about making the payments. He made 10 years worth of payments, and at that point, so this is like 2018 or something, maybe, maybe earlier, the interest rates had dropped. He went to his bank, the bank he'd been making his monthly payments to for 10 years, and he wanted to reaffirm, he wanted to finance the mortgage. They tell him the debt was discharged in his bankruptcy. He says, I've made payments for 10 years, not according to your credit report. And that prompted me, I actually wrote a statute, but unfortunately, the, I wanted to, the statute was to force creditors to report the payments, whether the debt was reaffirmed or not.
Cause really, I mean, he made 10 years worth of payment, that the bank is saying he may never receive anything. Unfortunately, the state legislation here has better things to do, but I did go up and made it to some sort of conference, but didn't get passed. But that's a problem. Yeah. I mean, because you don't think about it, and you said 10 years worth of payments and nothing. But they never let him stay in the house though, so they let him stay in the house. They never tried to foreclose on it. He wound up refinding some bank to refinance, which just would be easier to have been able to go to his bank that he'd made 10 years worth of payments to than to find a new bank.
But the other thing with banks nowadays that this probably applies to your entrepreneurial class is they should look, if they're starting a business, they should look to deal with a bank that only does business in Massachusetts. Ah, interesting. Because I don't know if you've ever, you know what a bank attachment is? In Massachusetts, if I'm a creditor, I can go in, if you owe me money, I can get a bank attachment. It's called trustee process. The courts in Massachusetts over the decades, it used to happen without notice.
The term is ex parte. Basically, what would happen is the poor business, the poor schmuck businessman would be writing checks on Monday to find out they're all bouncing because his bank had been attached. His bank account had been attached. Over the years, the judges decided that doing it on an ex parte basis was not proper. Instead, they give the debtor notice, and of course, what happens is they empty out the bank account before the hearing. But over the decades, when you deal, let's say, with a fleet bank or Bank of America, they have branches all over the country.
I've seen creditors in California go in and get a bank attachment over a bank account of a company in Massachusetts at Bank of America. Usually, it has to be a bank in Massachusetts. You'd say, who cares? But it's a surprise to people. Yeah, I would think of it a very unpleasant surprise. Well, you know, I've always said my parents didn't work hard enough and I didn't do it down in Bradstreet on my in-laws before I got married. That's why I'm here. So Barry, before, I mean, like, I'm going back to the beginning of our conversation.
I know I'm popping around, but that's the way my mind works. So you said that you prefer people to, you prefer a corporation to an LLC. You'd want to just talk a little bit about that. Yeah. You know, I tell you something. It has to do with, well, there's one reason, but it has to do with cost. You know, to set up a corporation is $275. You can have the same back tax benefits if you set it up, your accountant sets it up as a sub-chapter S. And if you want to make a change, you know, the Commonwealth never used to charge people, now they charge.
But for an LLC, the setup is $500. And I think anytime you want to make a change is $500. And I don't see that it necessarily, you know, where an LLC can lead to problems, getting back to the trust fund tax situation. Very often, people who have LLCs, they report the income and expenses as a Schedule C on their personal taxes. And the LLC doesn't file its own return. See, this is stuff that entrepreneurs should look at, really. When you do that, you enable the IRS. See, I always look at the downside. Like I said, CINIC, you know, you enable the IRS if you owe withholding taxes.
They don't have to assess you personally because it's listed on your personal tax return. See, typically, the process, if I have a corporation and I haven't been paying my withholding, I've been taking it, but I haven't been paying it, the corporation is liable for the underlying tax, what theoretically has been withheld. And as the individual, I'm personally liable for what they call the trust fund tax, which is only about 60% or 70% of the corporate liability. If you do the LLC and you have that problem, you don't get the discount.
It's a dollar for dollar. Because you and the corporation are basically one. You're filing it in your... You and the LLC are the same. Only the LLC, yeah, yeah, you're one and the same, which defeats the purpose of the LLC. And even though, you know, listen, you know, the process when you owe withholding taxes is they send you a notice of intent to assess you. And for clients, I have a nice bullshit letter that I draft for them and send out that, you know, but they're not this, they're not that. I mean, it's mostly because you can, you know, if they charge the fee, we probably think something about it, but they can appeal it.
And of course, by appealing it, it keeps that determination up in the air. So they then appeal it, and eventually it's determined that they're responsible. And it becomes now, if the corporation owes 100 grand, they'll be liable for 60 or 70. You know, and then it becomes collectibility. You know, we've been talking about office and compromise, things like that. You know, when it goes to pretty much, you know, in Massachusetts, like I said, jumping all over, you're familiar with, well, it's not a good thing for your, if your entrepreneurs own real estate, they should immediately record or see if they've recorded a homestead.
In Massachusetts, which I think, in my opinion, is second to Florida as probably the best homestead in the country, you can protect up to a million dollars worth of equity in a piece of real estate. Now, the interesting thing again is, back to Kafka, that only works if you file a bankruptcy. You have the protection and not the bankruptcy, but there's no mechanism to enforce it. But when you file a bankruptcy, so now you own a house that's worth a million dollars. It has a half a million dollars worth of mortgages on it by recording the homestead, which costs 35 bucks.
It's well worth it. You can now protect that half a million dollars worth of equity from your creditors. So when you go through a bankruptcy, and this is what happens when you start businesses and then start businesses again, a trustee looks at the appraised value of the house, the mortgage statement and the homestead, and it ceases to be an issue. It's not like the kid who couldn't play basketball, but he brought the ball and if you don't let him play, he's taking the ball home. They're not looking to, I remember somebody told me about what they heard about an abuse about the bankruptcy system.
Somebody went through a bankruptcy, they owned a condo on the public garden that was worth a million too, and they got to keep it. What the news report didn't tell people is there was a million six mortgage on it. What were they going to do? Sell it for the hell of it? You have to look at that. People who are starting up in business, what they really should look at, and this is probably almost a better topic, is setting their business up so that it can withstand the shit hitting the fan. It's very easy to protect. For instance, very often entrepreneurs lend money to their companies or have family members lend money to their companies.
Well, why should family members or friends or themselves be treated any different from a bank? They can put a security interest on the assets. Take a promissory note. Now, in a worst-case scenario, let's say dad lent them 50 grand and at the time, dad lent them the money, they give dad a security interest. I call it a mortgage, same thing. On the assets of the business, well, dad's in the first position now, if the shit hits the fan. You could conceivably surrender the assets to dad. Dad sells them back to Newco and Sonny Boy is up in business and wasting more of dad's money going forward.
Hopefully, dad has a lot of money. But that's what they should be thinking of. There's a certain point, benefit to being judgment-proof. You don't want to go into a business, and now you have assets that are at risk, which is what they really should do, a personal asset analysis to see what exposure they have, and see how they can tighten it up. Can they encumber things? Have people lent them money? I mean, what you want to not do is commit fraudulent conveyances, and when I talk about fraudulent conveyances in a bankruptcy sense, it's the worst that happens is they make you undo the conveyance or it comes down to money.
Not that somebody is going to come and hold you up or something like that. It's not criminal, but if you do that sort of planning in advance, it's one thing to put a security interest on a business three years ago, it's another thing to put it on 30 days ago on a debt that was five years old. Right. That's what they should be. I had an assistant many years ago, she wanted to know why all the debtors I represented drove fancy cars. I have no idea, but you want it to be in such a situation that there's nothing they can get from you.
I mean, even if it comes to putting the house in the wife's name, I mean, you have to have a certain amount of trust to do that stuff, but if you're married, maybe you do. Married 50 years, Jewish husband, that's all. But that's the kind of planning they should be doing. In addition to creating whatever it is they're creating, the next new widget that's going to revolutionize the market, how personally they're going to withstand the shit hitting the fan. Because I think of one of my, something I said once is it's too late when the shit is already hitting the fan.
Exactly. It's like people who come to me, and if you know about foreclosures, it's a nice day, I'm going to foreclose on your house today. Let me find an auctioneer. But I have people who come to me, they'll call at nine o'clock in the morning, I have a foreclosure on my house at one o'clock this afternoon. How does that happen? I mean, you know how many notices you get? I mean, maybe there was a time, but I had more hair. But I think that the rule, you have to be aware. And I think, you know, getting back, entrepreneurship sort of, you know, everything is wonderful, but you need somebody, you know, to give you a hard dose of reality.
I mean, I just liquidated a business. They were, the tariffs killed the business. They were handling freight coming into the country. Don't ask. But husband and wife, he was the cockeyed optimist. The people they were working for, they were going to hire them. They were going to do this. They were going to do that. She didn't believe anything. And of course, I agree with her. And of course, all the promises, it was hot air. Nothing ever happened. And it's, you know, you have to not fall into that position where, you know, you want to believe so badly that it's, you know, tomorrow is going to be a fiddly day.
Tomorrow will be a better day. It doesn't happen. Well, hope for the best and plan for the worst, right? That's a good one. And no good deed goes unpunished. That's the other one. So Barry, who's the right person to talk to if you want to set your business up the right way in the beginning? I mean, people call you ahead of time and say, hey, just in case, like, is that a thing that you do? I mean, that's something I typically go through with people, to see what other assets they have. Years ago, we used to put houses into trusts and things like that.
But with the homestead being a million dollars in Massachusetts, unless you really have real estate up the wazoo for a person, I don't think it's really necessary because the equity is protected. For your personal residents. But that's not the case if you had investment real estate. Yeah. No, unless you've lived in it. But otherwise, there's investment real estate. If it's not on owner-occupied, there's no homestead, but they generally don't have any equity in them anyway. At least if anybody asks. Cool. Barry, this has been really eye-opening for me, and you've given me lots of things to think about, and I'm sure that the listeners are feeling the same way.
But what have we not covered? What is the thing you wish we would have talked about, a question you wish I would have asked, something you want to make sure people walk away with? Well, the thing is, I find that one of the things we enjoy doing is assuaging people's nerves about their financial situation because people become incapacitated by it, and when you get down to it, it's only money. And, you know, it's not hopefully their health and things like that, which are, to me, more important. You know, the credit card companies, the banks, they'll survive long after we're gone.
They won't miss a beat. And, you know, I feel that we're able to give, you know, people the peace of mind because, as I say, I'm just an old hippie who happens to practice law. And, you know, it's not the end of the world. I mean, I guess being a cynic helps, too. But what you're saying is exactly what I say all the time. If all of your problems can be solved by money, you don't have any problems. Really? I mean, you know, you reach a point, you know, I'm old already, where you find out you accumulate shit and all you wind up doing is spending time getting rid of it all.
And, you know, my wife and I, our mothers were collectors and, you know, we actually had to get rid of their shit, our shit and younger people. Nobody wants anything. What's the point? You know, where we live, the apartment we live in, where I was telling you, the young people who live there, when they move out, it's like building 19 in the back. They throw it all out. Yeah. Why bother? Yeah. Why spend the money? It's insane. It's only things. I mean- All just stuff. Get rid of it now. Enjoy going out to eat. Right.
Exactly. Go to Drift. We go there too often. Well, we have three of them down there. Yeah. There's Fine Line and then there's, what is it? Mission on the Beach in the hotel. Yeah. I haven't been to Fine Line. I'll have to try that one, but I've been to Mission. Fine Line is good and Mission on the Beach, if you go there on Wednesdays, half-price lobster rolls. Oh, there you go. That sounds like a good plan for me for a Wednesday. Well, you can go to the anchor up here in Beverly. No, that's Tuesday. Two lobsters for the price of one.
Oh, wow. See, this is what you can do when you get, you know, start to look around. Okay. Well, where can I eat for half-price? Well, you know, my wife and I, we say we're now like the early birds, you know. We're not like 430. You don't find the full meal up here. It's not like Florida, but it's closed. But you'd be surprised at how many other people go out early, too. Oh, yeah. Why not? We're not the only ones. It's actually more healthy to eat earlier, and then you can- Well, so they say, well, we don't understand how we used to first go out at 7 or 8 o'clock to eat.
Then you got to stay up till 1 o the morning. Well, Barry, thank you so much for being with us today. I think that if nothing else, the wisdom of planning for any future and setting yourself up to be a little bit more bulletproof, it's definitely worth the conversation. So how can people reach out to you and get- Well, they can email me. I can give you my email. It's barryatlevineslaw.com. My website is www.levineslaw.com, or you can call me at the office, 978-922-8440, even though I hate talking on the phone. I'm in a business where you have to talk on the phone and I really don't like it.
Well, luckily, phone calls are becoming less and less common, right? Well, yeah, yeah. I go back to the days my mother used to call every Sunday to just say hello when the rates were cheap. But again, a college benefit we had at SUNY State University in New York is Governor Rockefeller gave us free long-distance calling. Didn't have to use a Watts line. Wow, you really date yourself Barry. Oh, please. Please. You know, when I don't like, well, it's like, well, I don't know if you can hear, I have listening to the dead while we're talking.
And my usually, I didn't wear it today. I have my I saw Jerry t-shirt. And when people say, you did? And I say, yeah, 1970, but it was many decades ago, 55 years ago. Wow. Crazy, huh? No, you know, when I look at my like alumni newsletter and stuff and I see the classes from 2008, I can't connect. Well, this has been a lot of fun. And you know, if anybody has any questions, you know, the one thing I think the entrepreneurs, if you have homes, by all means, record a homestead that you can do that yourself. They have forms.
It's well worth the 35 bucks. Yeah, very easy to do. And they can check online if they think they have one. Various, the registries of deeds offer the opportunity to search. And it's fairly simple to find. That's excellent advice. Like you said, an ounce of prevention now is better than the shit hitting the fan later. Absolutely, absolutely. Have a good one. Thanks, Barry. And all the links that Barry talked about, well, actually only the link to his YouTube channel, which is excellent and has a lot of great tips. And his company will be in the show notes.
So please check him out. You can tell he's got a wealth of wisdom and he can maybe help your shit from hitting your fan. Face the mother can love. And have a wonderful day. Oh, and share this episode with any small business owner you know who could benefit from it. And we'll see you next week.
About Barry Levine
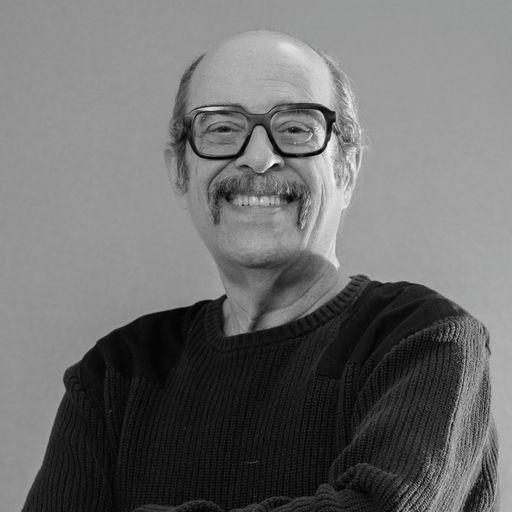
Bankruptcy Attorney and Debt Strategist for Everyday Americans in Crisis
45 years Representing people in financial difficulty1 book Author, Personal Bankruptcy Through The Looking Glass322 videos On his own bankruptcy YouTube channelBankruptcy attorney Massachusetts
The calls often come late: someone has ignored letters from the IRS, missed too many loan payments, or watched their small business slowly bleed out. They don’t open with legal questions. They ask if there’s any way out.
For almost 45 years, Barry Levine has answered that question with calm, practical guidance. A Massachusetts-based bankruptcy attorney, he works with individuals and small business owners navigating serious financial strain, people who are scared, out of options, and unsure what the next step even looks like. His work isn’t about judgement or quick fixes. It’s about helping people understand what tools are available, how the system works, and what choices they can still make.
What Barry sees again and again is that fear, not just debt, is what traps people. The legal process has structure, options, and predictable outcomes; what derails most clients is the panic that keeps them frozen in place. Barry’s role is to bring order to the chaos. With each case, he applies decades of legal experience to help clients understand what’s happening, what’s possible, and how to move forward with a strategy that restores both stability and control.
He first started practicing bankruptcy law in a hands-on Boston office while still in law school, learning case by case how to navigate both paperwork and people.
More from Barry Levine
All episodes → The Agent of WealthFinancial Crisis, Bankruptcy and Starting Over With Barry LevineOct 2026Play episode →
 School for Startups RadioOctober 5, 2026 – EdTech Find Your Grind Nick Gross and Bankruptcy Attorney Barry LevineOct 2026Play episode →
 Financial Mastery SimplifiedHow Bankruptcy Really Affects Your Credit and Home LoanSep 2026Play episode →
 Money Talk With TiffWhat Bankruptcy Actually Does with Attorney Barry LevineAug 2026Play episode →
 Wealth B-HersFear, not Debt with Barry LevineJul 2026Play episode →
 Us People PodcastThe Law We Decide To Practice - Barry Levine - Attorney At Law #314Apr 2026Play episode →
 Chrisman Commentary - Daily Mortgage News4.14.26 Fines Versus Taxes; Attorney Barry Levine on Delinquencies and Foreclosures; Agency MBS PerformanceApr 2026Play episode →
 JUSTIN AND THE [FOOD] ENTREPRENEURSEpisode 520: Barry Levine of The Law Offices of Barry R. Levine - Beverly, MA. Shielding Your Personal Assets. Avoid Bankruptcy Before It Hits. Legal Lifelines for Food Entrepreneurs. Cost Accounting.Apr 2026Play episode →
 How Much Can I Make? — Real Jobs. Real People. Real Money.Bankruptcy Lawyer Explains Chapter 7, Chapter 13 & Getting a Fresh StartMar 2026Play episode →