
September 25, 2026
Protecting Your Nest Egg in Retirement with Theodore Hicks
Sound bites
Diversification is not necessarily going to save your portfolio. Neither is bonds not necessarily.
In this episode
Theodore Hicks talks about protecting a retirement nest egg, challenging buy and hold advice, and building a more defensive approach when paychecks stop.
- Traditional buy and hold advice can fail when retirement timing lines up with a major market drop.
- Retirement changes risk tolerance because the money now has to cover bills, not just grow over time.
- Cash helps, but a defensive strategy matters too when market anxiety and sudden downturns hit.
- Diversification and bonds may not protect a portfolio as well as people expect when markets turn highly correlated.
- Education and questioning advisors matter, because investors need enough understanding to ask better questions.
Transcript
ShowHide
Automatic captions of the conversation. They can contain errors and do not name who is speaking.
Most of us are told the same thing about investing. Stay the course, ride out the dips, and trust the long term. But what happens when you no longer have decades to wait out a bad market because you're retired or about to be? That's why in this episode of the podcast, I talk with Theodore Hicks about what it really takes to protect a nest egg once the paychecks stop coming. Well, my guest today is Theodore Hicks, the founder and chief investment officer of Hixon Associates Wealth Management, anindependent registered investment advisory firm based in Kerry, North Carolina.
Ted began his financial planning and asset management career in February of 1999, just in time to spend the first 10 years of his career navigating two of the worst bare markets in the last 70 years. The.com crash and the 2008 financial crisis. Those experiences shaped his conviction that surviving the short term is often the price of admission for investing well over the long term. Ted is the author of Evidence-BasedInvesting: To Invest Well over a long term, sometimes you have to first survive the short term, in which he challenges some of the financial industry's most repeated advice, including the idea that everyone should simply buy and hold for the long term and lays out a rules-based multistrategy approach designed to manage risk when the markets turn against you.
Today, Ted and I are going to talk about why traditional buy and hold thinking can be especially dangerous for people at or near retirement. What most people getwrong about safe investments like bonds, and what it actually looks like to build a plan that protects your nest egg no matter which direction the market moves. Welcome to the show, Ted. >> Thanks, Steve. I appreciate you inviting me on. I'm looking forward to the chat. >> Yeah, it's going to be a great conversation. I've had some other uh u interviews with folks and and guests on the show that have talked about, you know, life after the paycheck stop and uh getting them to understand the the umthe mind shift uh a mindset shift that has to happen at that point uh from when you go from more saving to spending, >> right?
don't. And that's the thing. A lot of people have spent decades trusting a set it and forget it strategy, buy and hold, when it comes to saving for retirement. But that changes once you retire. What does it look like for these these people's uh to start asking harder questions of their advisor or themselves before it's too late? Well, Steve, the the reality is thatwhen the stock market doesn't care when you retire, >> the economy doesn't care when you retire. And so the the reality is when you study the history of the stock market in this country or any other country, you're going to see es and flows that everybody that's a given.
Everybody gets that. That's fine. But the the the the classic advice of just leave it alone and it'll all work out in the end, that doesn't take into consideration your timing, your time frame, nor does it take intoconsideration your psyche. So what changes when you retire? Well, I have so I've been doing this now, Steve, for about almost 30 years. And you've heard of the proverbial monkey on somebody's back. >> Yeah. Well, I've had meetings with clients where, you know, we we have a target date, we want to retire, and we go through the numbers and they're not convinced.
And six months later, we go through the numbers and they're still not convinced. And the third time, sometimes the fourth time, I mean, it'slike they they lay three or four inches taller because the monkey finally got off their back. They're relieved. I finally convinced them that the, you know, that they have enough. But I don't know what's going to happen next week. Maybe next week we're going to have a major market crisis and that's the beginning of a two-year stock market slide. Right? So there there has to be a a defensive plan because anxiety is real and we need to be able to to manage that and to some extent Steve that'sfinancial planning and I'm sure a lot of your guests have uh would would recognize that you need to be prepared for market crisises by having cash.
Yes, that's certainly true. But you also need to be prepared by having a defensive strategy. It's simple as that. >> Well, and and it's not only mindset, but sort of a uh a risk tolerance change where you can be have more afford more risk when you're saving for retirement because you don't need the money right now. You you it's going to be a longtime before you have to take it out. So, you can more uh weather out the ups and downs of the market. and in fact can greatly benefit from downs in the market because if you invest in a down market when the market recovers you can have a huge rate of return.
So that that risk changes because now you need the money you got to pay the bills. >> Sure. >> So that risk tolerance changes and that's a a big mind shift and and a different way of looking at risk isn't it? >> Well it is but I would argue that therisk tolerance doesn't necessarily change. It's your uh the your risk exposure might need to change. >> Okay. And the way that I explain this to clients over the years is u I usually make a confession. I now dodge a Dodge Ram. I drive a Dodge Ram, but I used to drive a BMW 550.
>> And if you've never driven a BMW 550, just know, Steve, that that thing has a lot of horses. >> Okay. >> There was a particular stretch of road coming from downtown Durham back to myhouse. There's this really long entrance ramp onto the interstate and it the it was like nice banked curve and I I tell you Steve I I would I'd press that car and I'd get like 80 miles an hour on that entrance ramp but only in the right conditions. One of which is there's no black and white uh police officer behind me. But in the right conditions I'm going to push that car.
I am not going to take that curve like that in my Dodge Ram. I'm also not going to take the curve like that when it's raining orif I have a headlight out or etc etc. And so my point is not knowing you, not knowing the listener, >> I'm willing to bet that you change your driving behavior based upon the conditions. >> Right. >> Right. Why would you not do the same thing with your portfolio? Now to some extent the classic advice is, well, now you're older, therefore you need to reduce your risk. Why? Maybe this is the best time in in history for you to be pushing the accelerator down.
That's fine as long asthe conditions are appropriate. The problem is most people that are managing money from a for the retail, they don't have a process for actually determining what is the prevailing risk. Is this a safe spot for us to push that car or is it a spot where no we need to back off the throttle? That's my point. >> Well, yeah, absolutely. because you're going to have and and often times it's part partly from what I understand uh u diversification within your portfolio because you if you have money in uh RothIRA that can sit longer and you can and that money can you don't have to take it out there are no required minimum distributions so that can help in recovering from bad times during retirement.
Uh but one of the one of the misconceptions as I understand it a lot of retirees assume that um uh bonds are sa the safe part of their portfolio. They're going to be fine. That's right. You know, you've shown examples in your book of long-term treasury bonds losing more than 50% of their value. Uh what doretirees get wrong about fixed income and sort of bonds as income generating investments? Yeah, bonds are certainly can be an income generation uh generating tool, but bonds the the example or the graphic that I have in my book is a graphic of a teeter totter, a child's teeter totter.
Now, >> I'm in the south, you're in the north, so maybe it's a seesaw up there. I don't know. But, you know, either way, teeter totter, seesaw, uh when you think about bonds, you have to think about thatteeter totter because on one end of the teeter totter, you've got the price of the bond and on the other end of the teeter totter, you've got the interest rates. And when one of them moves, the other is going to move uh in proportion, right? And so if the interest rate environment is going up, which it is, what's happening to the price of bonds?
Bonds are going down. And so the chart that I show in my book >> is that of the federal the Fed funds rate. >> And so since 1980s, the Fed funds ratehas been in a um downwardly biased direction. Now, there's been periods where the Federal Reserve has raised rates, of course, but generally speaking, since the 80s, we've been in a secular bull market for bonds. Interest rates generally were going down. That's not true anymore. Now, we are in an upwardly biased interest rate environment. That doesn't mean interest rates won't go back down ever.
That's not what I'm saying. But we are no longer in a bullish environment forbonds. It is more likely to be bearish. And the reality is most of the people listening to you and me, they grew up they they accumulated their wealth in a bullish environment for bonds. Well, that environment doesn't exist necessarily anymore. And so the bonds are not necessarily going to behave the same way. M >> and so that's part of the reason why we feel strongly about measuring the overall risk environment because if we are in a high-risk environment and we need to seek safety in some measure thatdoesn't mean we should go to bonds that is not necessarily true and 2022 is a perfect example right 2022 also can speak to some degree of diversification and I go through the example in my book that the majority of the stock market was down in 2022 so was the bond market and so you you think you're safe because you've got stocks and bonds.
Not necessarily, >> but I've got large cap and midcap and small cap and all this. It's not in a bare market correlation tends to go toone. What does that mean? In the bare market, when the proverbial poo hits the fan, it all tends to hit the fan because we have become more and more integrated. When I started in the business, this is my old man story, Steve. When I started in the business 30 years ago, we had some benefit of adding international exposure to the portfolio because 30 years ago, think about what you were doing 30 years ago.
Did you really care what was going on in China, >> right? >> Probably not. >> Well, today is a different differentanswer completely because the world is so interconnected, right? So correlations uh have have gotten higher and this is ultimately where I think a lot of the industry um misleads or is misinformed is maybe a better way because every the the concept of diversification stems from Harry Marowitz's work and FMA and French and some very smart individuals who make assumptions that for example correlations are constant but we know they're not.
Mhm. >> Well, yeah, but if their correlationsare constant, then this would be true. Yeah, but we know they're not. Therefore, we know your conclusion is false. >> And so, that's my the point that I'm trying to make is that some of the assumptions that the industry has been operating off of, they're not a little wrong, they're very wrong. And so, we need to measure risk differently. And how we handle risk in my opinion needs to be done differently. >> Right? So that said, what uh should bond the the role of bonds be in someone'sportfolio when it comes to long-term investment like uh retirement and using retirement?
What should they be doing with bonds? >> That's a good question. I'm going to have to um choose my words carefully because I am in a regulated industry. Uh obviously I can't give advice, you know, through a YouTube channel or a podcast or whatever, right? And bonds definitely do h they can play a role, but you cannot think of them as quote unquote safe. Now, if you're a uh the classicallong-term investor and you're going to hold that bond to maturity, for example, if you're in New Jersey and we're talking about your taxable portfolio and you're buying New Jersey municipal bonds and you're just say, "Hey, I'm going to hold this to maturity." Well, as long as you have confidence in the municipality to keep paying the the bonds, then yeah, you could argue who cares if the value the face value goes down.
But the reality is that's not how most peopleare choosing and are are handling their bonds. They're making changes to them. And a lot of folks are using bond mutual funds and things of that nature. Mhm. >> So, I'm I'm definitely biased against bonds because I'd much rather take the risk in equities and then just back off the throttle when we're not in a risk appropriate environment. >> Right. And you make a good point and I should stress to our readers out listeners out there uh that and I've said this in many shows before, youknow, this is great information that we have for you, but this is information you should take to the appropriate professional whether it be a a certified financial planner, CPA, or whatever to look into your situation.
Uh but uh that's, you know, something to ask them about. >> Yeah. And said, Steve, I would add to that and say that in my book, I talk about this that um my book is not designed to be a a recipe book, right? >> You can't read my book and then know exactly what I would do if you were if Iwas managing your money or it's not designed to do that. I don't like prophetic books unless they were written 2,000 years ago. That's a different conversation. Um but um I my the purpose of my book is to help educate somebody as to what questions should they ask, right?
And my book is also it's it's very brief. It's very easy to read. Like the number one feedback that I've gotten on Amazon is that that people are surprised how easy it is to read and that they normally don't read thesetypes of books, but they still enjoy it. >> Right? >> So I'm trying to educate you, but if you read my book, you haven't read enough, >> right? You can't read one book and become an expert. You have to read 10 different books by nine 10 different authors before you can really discern the the good advice from the bad advice.
And that's the point is you've got to question the the advisors that you're you're using. And that's part of what I'm trying to do in my book is give yousome ammunition on what questions to ask. >> Exactly. It's like all the drug commercials out there on TV. Ask your doctor if such and such is right for you. That's pretty much what we're saying here. These are ideas. These are things to think about and things to ask professionals about as to whether it's the right thing for you to do. Uh so let's talk about some misconceptions.
What would you say is the biggest misconception that you see people carry into retirement about how theirportfolio should be managed once the paychecks stop coming? I mean, like I said, it's a shift from saving to spending. >> I would argue that the biggest misconception is that you can just leave it alone and just set it and forget it and that it's all going to work out in the end. Uh I could bore you and your your readers or listeners or see I just did it too. Uh we could bore everybody with all kinds of uh very big global macroeconomic concerns that reasons why the next great depression is coming.
AndI mean, I could I could have that debate if you really want to. I my job is a lot easier if that doesn't happen, >> but I take my role as the shepherd of other people's wealth pretty seriously. If it does happen, I want to be prepared, right? >> And so that's that's the point. I would also argue that just last week I was talking to somebody. She's got like 22% of her portfolio is in gold >> and she's thinking that's a brilliant move because of all these economicuncertainties. And you know, it could work. What if it doesn't?
What if people don't own cold anymore? >> Well, yes. Right. But yeah, and so it the the question is what if you're right and what if you're wrong because you can't just in my opinion, you should not just be putting together a portfolio and assuming it's all going to work out in the end. Now, there's obviously the risk of overtrading and making too many changes to a portfolio, but there has to there should be a disciplined process ofhow to protect principle and when you should try to grow the principle. >> Yeah. You got to uh do a stop, look, and listen.
I mean, just like I tell people when they do when I do their estate plans, you know, have this looked at every five years or so. Have it looked at if you get married, get divorced, have a child, retire. There are a lot of life events and things that happen that really uh h you should be looking at your >> estate plan again or your financial plan again. Uh that you say the misconceptionis that set it and forget it. Well, it may be buy and hold to a great extent, but that that doesn't mean set it and forget it. Periodically.
>> Yeah. And the way that I talk in my book is I say buy and hold with a twist. So, it's buy and hold with an asterisk. You know, >> buy and hold as long as the trend is up. >> Right. >> Right. If the trend changes, you might want to be willing to shift because what if that is here's a classic example. I think it was January 7th, 1963. Do youremember Alan Greenspan? You know, he run the Federal Reserve. He sat sat in that seat for like 30 years. In January 7th, 1963, he made a comment. I believe he was quoted in the New York Times and said, "There's never been a time where you could be as unqualifiedly bullish as you can right now." That was January 7th, 1963.
The next trading session was January 10th. And January 10th began a 2year stock market slide, >> two years, >> and it took six and a half years to getback to break even. >> Now, I have an idea. Why don't we get that guy to run the economy for 30 years? Well, everybody makes mistakes sometimes, I guess. >> Sure. But my point is he he probably had very good reasons of saying that on January 7th or whatever. But are you willing to recognize when you're wrong, >> right? And you have to keep looking at it. >> Okay. uh that you you've talked about uh in your book about how in in in a real crisis previously diversified assets cansuddenly all start moving together, right?
>> So, you know, diversification isn't necessarily uh panacea either. What What does that mean for someone who believes they've already properly diversified for retirement? >> I would argue know that you're possibly wrong when the market changes. Again, take a look at 2022. It's the easiest example because it wasn't that long ago, >> right? >> And the only thing that was in a positive trend that year was commoditiesand energy. >> And most of the time when I sit down and look at a client or a prospective client's portfolio, they have very little to no commodities.
Some of that, by the way, is some of the big firms really put a uh a limit on that, right? And they have reasons to do that, but I would argue they're arbitrary. Uh, and very few people are holding energy unless it's an energy stock. Like they might have Exxon stock or something like that. But as a sector like a a sector energy fund or an ETF, I don't reallysee that. Why? Because it's not sexy. They don't want that. They want the AI. They want, you know, those types of things. Well, if you were diversified, but you didn't have those two asset classes, you were really hurting in 2022.
Mhm. >> And so one of the things that we will sometimes ask prospective clients and we'll say, "Mr. Mrs. client, do you want when if you hire us, do you want do you want to be diversified?" And they say, "Well, yeah, of course." And I said,"Well, with all due respect, I think you're lying." What? Well, I think if you're honest, you would like to be 100% long Nvidia about five years ago. >> Oh, well, yeah. I guess I see your point. And so my my point is diversification uh can help but it is especially in today's environment where everything is so intercorrelated and interconnected.
Diversification is not necessarily going to save your portfolio. Neither is bonds not necessarily. They might they might not>> because even though you're diversifying you what might be in different industries the uh interlocking or interconnectedness of those industries uh it's kind of like uh um what is it quantum entanglement you know one one uh industry goes this way and it causes the connected one to to go with it >> correct >> and that could be a problem >> right and then plus on top of that Steve you have this is a bad thing don't do this Okay.
But on your way home, assuming you leave work before 4:00Eastern time, >> on your way home, you could trade your portfolio at a stoplight. >> Right. >> Right now, again, bad advice. Don't do that. Right. >> My point is people have the ability to go to cash very, very easily at the at the push of a button and trading costs are zero. Now, you can argue that's not a good idea, but you can't argue that you can't do it >> and people do it. And so th that I would argue contributes to some of the volatility and you can rail against itall.
Like to me I live in Kerry, North Carolina. This is this is tobacco road basketball country. You know the ACC. Well, as far as I'm concerned, the ACC doesn't exist anymore. >> I mean I think there's a California team in the Atlantic Coast Conference. How is that possible? Right. And so I mean I can complain about that all I want but I can't change the fact that it is >> right. So yeah there's that interconnectedness. So there's really you know and you youmentioned about uh I I know one of the guests I had invests a lot in utilities because I said well gold's great until people don't want it anymore.
But people are always going to want electricity. They're always going to want natural gas. They're always going to want, you know, certain things. They're always going to not just want it, but need it. >> Right. But here, you actually brought up a great point, though. >> Just last week, I posted on my LinkedIn page that two sectors that aretraditionally considered safe are negative yearto date. >> Bonds and utilities. >> Wow. >> They're negative year-to- date. So your point is true, but the what people don't realize is there is a difference between a good company and a good stock.
>> Two different things. Now eventually they will they'll match, right? But even though you're you're correct that people are always going to want their utilities, it appears that people don't want utility stocks right now. So do youwant to ride through that? That's up to you. Yeah. So, another mind sh uh mindset shift uh as someone as uh people that are in or near retirement uh how should they be thinking differently about things like taxes and capital gains when they start taking withdrawals from their portfolio as opposed to letting it ride and being in a dividend reinvestment program.
So, generally speaking, I don't like letting the tax tail wag the investment dog. If it's a bad investment, get out of the investment.>> Okay. >> Okay. Um, however, we can't ignore the tax consequences either, >> right? >> One of our clients has a very large position and um, you know, actually is true for several clients. We if a client has a very large position in an individual stock, we're going to take that into consideration. But that low, very low basis also allows us to ride through some of the volatility because you're not going to ever get a at a loss.
I mean, the stock would have to godown 99% in order for you to be at a loss. So, we can ride through some of that. But if that's not true, then we have to factor that in. >> But the reality too, Steve, is that the majority of the people uh 70 to 80% of their wealth is tied up in their IAS and 401ks and things of that nature. And so the question is is irrelevant. >> Ultimately, the answer is a good rounded a well-rounded financial plan is going to include an investment plan that factors in the tax consequences. >> Some of it is also trimming on the wayup, >> right?
as the stock as that position is is rising, you might want to trim it on its way up because if a major market crisis comes, do you really want me to call you and say sell it all now and you pay that big tap capital gains now? No. That's why we trim on the way up. >> So controlled growth, I guess, is you know, make sure you're not uh >> you know, the faster you go up, the faster you come down, I guess. Well, the the reality is people don't want to sellit on the way up because it's doing so good. And I get it that I generally don't want to sell something if it's doing well, >> right?
>> But if it's a non-qualified position, so you're going to have a capital gain, we have to recognize that at some point we are going to need to sell it, >> right? So, I mean, I had a phone call from somebody not too long ago and they had a a fair amount of money in Nvidia and the way they spoke is that they'll never sell it. I'm like, okay, I mean, Iget it, but we can go through a long list of of former corporate giants that are no longer with us. So I >> just when you go in with that mentality I had many years ago I had some clients they both worked at Nortell networks.
You remember Nortell networks? >> Yes. >> Okay. Not many people do anymore. >> They they I argue they failed retirement both because they got bored. They didn't have something to do in retirement which is something is another topic for your show. Right.>> Right. Um but it they also refused my advice as well as the prior planners and both of us were telling them they need to do something with all that Nortell stock. >> Well, it went to zero. >> Well, hey, it's like, hey, uh at one point, you know, everybody had a Blackberry.
Oh, I'm going to hold this is a great company. I'm gonna hold on to this. And what what happened? Where are they now? Right. >> Yeah. Same thing. And that's exactly the point is that whether you're talkingabout Apple or Amazon or Nvidia or whatever, it's eventually these companies are going to go through major major corrections >> and you have to ask yourself how much am I willing to give back. Ask yourself that in advance. >> It is I'm not advocating gambling. I'm not a big fan of gambling, but uh you're in New Jersey, so if you have a friend that's going to go to Atlantic City, I would say, you know what, you might want to think about in advance, >> how much money are you willing to bet?>> How much money are you willing to lose?
And once you lose that much, >> do you have the discipline to stop? >> You need to have the discipline to stop because that's how problems start. >> Right. Exactly. Right. And a lot of what we're talking about here, I mean, IRA or whether they're traditional or Roth are great uh retirement investment vehicles, but for upper income people, you know, they're not they're not really available to them. So, they're they're reallydealing with investments and portfolios that have these tax consequences to them. >> That's true.
And so then it becomes a a question of how do you structure a portfolio to uh account for that? Uh and some of it is you have to recognize that there's the government is not going to allow you to get out of it taxree. You're going to have to pay the taxes, >> right? >> It's just how much pain do you want? Do you want pain on the downside when the market correction comes or do you wantpain on the tax bill, right? Or a little bit of both. It's just for me it's it's having a a a very intentional conversation with the client as well as the tax preparer >> so that everybody's on the same same page.
Yes, we realize that it sometimes it makes sense. We like tax deferral strategies but sometimes it makes sense to have tax acceleration strategies. >> Right. So uh you've also written about how the national debt is now standing at over 120% of uh debt to uh gross domesticproduct. How how real is the risk to an individual's retirement savings is that and what should someone approaching retirement actually do with that information? >> Uh I would say that the answer to your second question is what do you do with it is you be on guard right at the moment.
Yes, the United States economy is arguably the world's u most important economy. We are the world's reserve currency, which means most international trade is done in US dollars. But if you look at if you look underneath the thetop layers of that, more and more tra international trade is done outside of the US dollar system. >> So what does that mean? >> If we lose world reserve currency status, that is not good news economically for us, >> right? And if you do a fair amount of reading, I won't quote the authors because I don't like quoting anybody as a a prophet again unless they were in a book written 2,000 years ago.
Um, so if a lot of the world's empires have collapsed due to excessive debt,>> now our debt to GDP is not a problem so long as um we can continue to issue our own currency. Right. >> Right. But when we issue our own currency, the video that I put up on my YouTube channel today talks about inflation a little bit and inflation skyrocketed a couple of years ago. Why? Because we printed an awful lot of money after COVID, >> right? >> That's digital money printing. And when you put more money into circulation, you're going to get inflation, >> right?>> And so now we're at this problem.
We are in a different environment economically with a rising interest rate environment. We are already as a nation spending more on interest payments on our national debt than we are on defense spending. >> Right. >> Right. And if the rates are going up at some point in the notsodistant future, we are going to have to issue debt in order to make debt payments. And so I think it was um I want to say it was Hemingway and I think that's thisis where this comes from. In one of his books um the main characters asked how he went bankrupt and he said well two ways gradually and then suddenly.
>> Yeah. >> Right. And so I'm not arguing that the United States economy is going to go bankrupt. That's not what I'm arguing. But it's certainly the way it's happened historically. Mhm. >> Right. And so what if that happens? Now again, if you want to take this to the extreme, you know, go buy yourself a 100 acres of land, learn how to be a farmer,and and you know, bury some physical go. Yeah, you can take it to that extreme if you want. And I'm not suggesting that. I'm simply saying that we could easily make a case for very large economic problems at some point in the notsodistant future.
And the question is, are you going to be able to ride through that >> without making any defensive changes to your portfolio? Well, in order for you to answer that, you have to know how it's going to end. >> I don't know how long that's going tolast. And again, you talk about Allan Greenspan, a very smart individual, making this bold declaration. It took him six and a half years to be right. What does six and a half years look like to you, Mr. Client? Well, gee, by then I'm 71. >> Yep. and I'm well into retirement so I don't want to >> right again >> to recover that >> most of the time when when we are working with a client we're we yes the bulk of our pretty much all of 99% of our income comes from managing assets wedo uh we will do fee based financial planning we don't sell products uh but so we're fee only but my point is when we're working with somebody we're trying to help them to answer the question as to whether or not they can retire >> if we get them to that point and then economic calamity happens, we want them to be able to still turn in that letter of retirement notice.
I don't want them to have to change. And if six months into retirement, something happens economically and the stock market, youknow, begins to hiccup and burp and things of that nature, I don't want their anxiety to rise. So, we have to have a defensive strategy on how to mitigate that. And how do you navigate those troubled waters? That's my whole point. You cannot use the theories from the 1950s because they're wrong. >> You describe your firm's approach to all of this as multistrategy, blending rules-based, trend following, and tactical models rather than a traditional buy and hold approach.
Howdoes it actually work to protect a retireese's nest egg during a prolonged downturn since we've been talking about that? >> Yeah. So, there's there we use most of our clients have exposure to four different equity strategies. >> And the reason, Steve, why we use different strategies is because I believe that there's no such thing as an investment strategy that works 100% of the time. >> So, are we diversified? Yes. But we're diversified by strategies, not the waythat most people think about being diversified. >> So, does buy and hold work?
Well, it can work. Well, I want to participate in that when it's working, but when it's not working, I don't want it. So, when we're buying and holding, we're buying and holding. Like I said earlier, it's with a twist. If the trend is up, we want to participate. If the trend changes, I want to deviate from that. I want to I want to just sit in cash. I'm fine with cash. And so, that's some ofit. Two of our models are what are called quant models and it's just rules-based. You know, it's if this is true and this is true and this is true, well then buy that.
But if these conditions are not true, then just sit in cash and and seek shelter, right? That's quant. So we have two quant strategies. Our tactical strategies um that is more of the trend following and tactical swing trading. And the idea there is that uh we don't we want to invest in things when the price is goingup. >> Uh >> right. How do you know price is going to go up? Well, it's supply and demand. Well, if you look at a stock chart, it'll show you. Now, that doesn't guarantee that it's going to continue to go up, but we're trying to we want to own things that are in relatively strong trends and have a decent chance of continuing in that trend.
And there in that portion of the portfolio, our approach is to uh cut our losses short, but let our profits run. >> So if we buy something and it begins tomove against us, well, let's be agnostic. I don't really care what it is. I don't care that it's utilities and it's always safe or it's AI and AI is going to save the world or destroy the world depending upon who you listen to. But um point is I I don't care what the thesis is. If it's going down, something's not right. So just protect the principle, >> right? >> But if it's working, just let it work.
>> Yeah. Well, I try to with these episodestry to have our listeners leave with at least one action item, at least one thing that they can do. Uh you dedicated your book to your late father who always told you to never stop learning. What's the one lesson from your career you'd most want someone listening uh to this podcast who's looking to protect protect their nest egg, you know, to take to heart? >> Well, I appreciate the question, uh, Steve, and I would say that yeah, never stop learning, and you might want to start learning that which you that hashistorically been intimidating to you.
Again, some of the best feedback I've gotten from my book is people that tell me, "I never read books like this, but I actually enjoyed your book. >> It's very easy to understand. My book is only 130 pages, and there's a lot of charts and graphs in there to make the points very, very easy to read, >> uh, very easy to understand." And so, that's what I would tell somebody. Um, one of my favorite uh verses in scripture is Acts 17:11, which says,"The believers in Berea were more noble than the Thessalonans, for they searched scripture daily to see if what Paul said was true." Now, obviously, that's dealing with theology and things of this nature, but I would argue the principle applies here.
>> We should be listening to our estate attorney, right? But we should kind of question him, too, >> right? You should be listening to your financial planner, your portfolio manager, but you should question him, too. listen to your politician or yournews anchor, whatever. But question, you might want to question them more. Um, >> but my point is you in order to be able to ask good questions, you're going to need to educate yourself just a little bit. And that's what I certainly tried to do with my book. And at the back of my book is a reading list of other books.
So you just continue on that that journey >> uh of learning because some of what is being preached in this industry a lot of it actually is just just flies in theface of logic. >> So uh where people if they want to get your book uh how can they how can they find it? How can they get your book? >> So you can go to theorhicks.com if you would like. You can get the first you can get the introduction and the first chapter free at theorhicks.com. You can find the book on Amazon. I'm sure it's on Barnes & Noble and Walmart and wherever you buy and buy good books, it's there.
Um there's even though there's a lot of charts in my books, Iwas told I should do it I should do an audible so you can actually listen to my book as well. Uh Kindle version, it's all those versions out there. But um evidence-based investing wherever good books are sold. >> All right. And beyond your book, uh if people want to learn more from you, what kind of services do you offer? How do you help folks? >> So, the best I've tended to uh lean on LinkedIn here over the last 12 months. I try to post there a little bit more.
I'm not very active on most of the socialplatforms. I do have a YouTube channel. Hicks- Associates is is our YouTube channel where I'm trying to educate and inform but not sell. I like to say, Steve, that we are trying to expose you to new ideas, but we're not trying to impose anything on you. Mhm. And >> so LinkedIn, if you just search for Theodore Hicks, you can connect with me. And by all means, if you send a connection request, say, "Hey, I heard you on Steve's podcast." >> Great. Well, Ted, appreciate you comingon the show and helping our listeners out there to get an idea of what they need to do as they approach retirement uh to protect that nest egg so it's always there for them and always able to provide them with financial freedom well into retirement.
Thanks for having me, Steve.
About Theodore Hicks
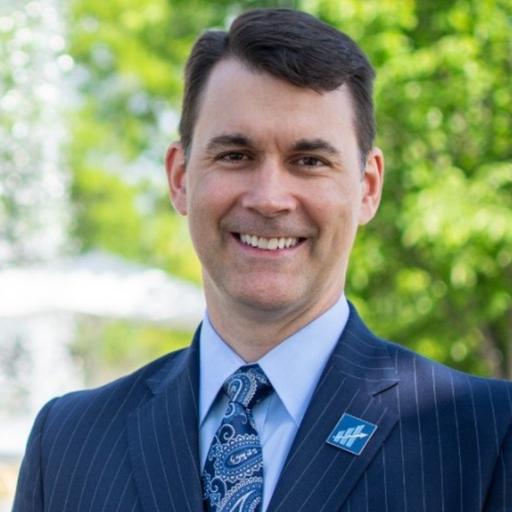
Wealth Management Author, Financial Planner and Market Strategist
20+ years Financial planning and portfolio management2 awards Winner for Evidence-Based Investing3 credentials CFP®, CKA® & CMT®MoneyShow Masters Symposium Industry speaker
Theodore Hicks is a financial planner, author and speaker whose approach to wealth management was shaped by experiencing some of the most difficult market periods of the past three decades.
He entered the profession determined to help people build thoughtful financial plans, only to begin his career during the dot-com crash and later guide clients through the global financial crisis. Despite following the established guidance promoted by major firms and academic theory, Theodore saw how quickly even a well-constructed financial plan could be undermined by severe market losses at the wrong stage of an investor’s life. That experience led him to question the industry’s default assumptions and develop a more defensive, evidence-based approach to portfolio management.
Today, Theodore helps investors navigate the point at which accumulated wealth brings greater complexity, higher stakes and less room for error. His work is particularly relevant to business owners, senior executives, professionals and retirees who have spent years building their assets but no longer want the responsibility of managing every investment decision themselves. He challenges the idea that investors must simply accept major losses, ride out every downturn and trust that markets will recover on a timetable that suits their lives.
Theodore is also the author of a highly regarded book written for both experienced investors and the next generation of financial professionals.
More from Theodore Hicks
All episodes → Serving Seniors PodcastEpisode 116: Retirement Investing for Seniors: How to Manage Risk and Protect Your WealthOct 2026Play episode →
 INVESTOLOGY: re-think investment managementSurvive the short term. Thrive over the long term. | Theodore Hicks - Evidence-Based InvestingOct 2026Play episode →
 Invest in YouRethinking Wall Street: Why Conventional Investment Advice FailsSep 2026Play episode →