Investing
Why Diversification Fails Investors When Markets Fall Together
Portfolio manager and author Theodore Hicks explains why spreading money across assets is no safety net on its own, and what a disciplined process adds.
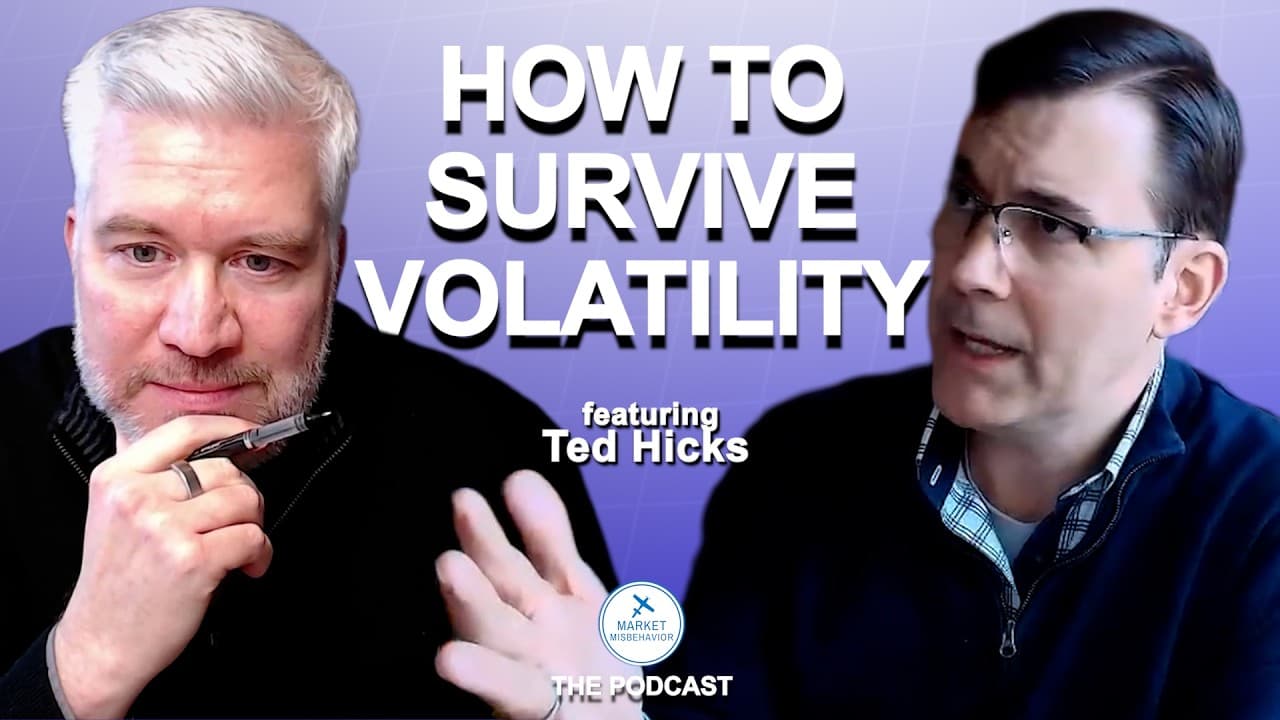
Diversification Can Fail When You Need It Most | Ted Hicks (Evidence-Based Investing)
Video from Market Misbehavior with Dave Keller, CMT.
Generated from the canonical interview transcript and validated against source data by Guests on Air.
Why does diversification fail investors when markets fall together?
Diversification depends on assets moving differently from one another. In a broad sell-off such as 2022, correlations rise toward one and almost everything falls at once, so the protection investors expect disappears. Theodore Hicks still diversifies, but by strategy and position size, and he pairs it with rules for raising cash so a portfolio can survive the short term.
Most investors are told that owning a wide mix of assets will protect them when markets turn. Theodore Hicks, a North Carolina portfolio manager, wealth manager and author, thinks that promise is repeated far more often than it is tested, and he spent a large part of his recent book explaining why.
Speaking with Dave Keller on the Market Misbehavior podcast, he pointed to 2022, a year when just about everything fell together and a mix of assets gave little shelter. His conclusion is blunt: the idea works while assets move apart, and it breaks down in exactly the conditions when people are counting on it most to protect their savings.
He does not argue for abandoning diversification. He argues for understanding the assumptions behind it, diversifying by strategy and position rather than by habit, and building a process that lets a portfolio survive the short term. The conversation below sets out how he approaches each of those three ideas.
Key takeaways
- Diversification relies on assets moving differently, and that relationship can vanish in a broad sell-off.
- In 2022 correlations moved toward one, so owning a broad mix of assets offered little protection.
- Hicks diversifies by strategy and position size, holding what works rather than owning every asset class.
- A written process, like a pilot's checklist, keeps decisions calm when markets become turbulent.
1. The assumptions behind the promise
Hicks traces much of Wall Street's standard advice back to Harry Markowitz and modern portfolio theory. He calls the original paper groundbreaking, but says most advisers only know the summary version of its conclusions. Before writing his own book, he bought and read the work itself, and came away convinced that the assumptions matter more than the headline advice built on them.
The theory works on paper because different assets have different correlations at a given point in time. The trouble, Hicks says, is that those relationships do not hold steady. In a year like 2022, correlations moved toward one and nearly everything fell together, so the mathematical benefit of spreading money around disappeared just as investors needed it.
He also takes aim at the familiar line that wealth is created through concentration and preserved through diversification. Diversification has preserved wealth at times, he accepts, but it is not guaranteed to. For an adviser responsible for other people's savings, relying on something that fails under stress is a risk he is not willing to take. He would rather know the limits of a tool before he depends on it.
2. Diversifying by strategy and position
Hicks is clear that his portfolios are still diversified. The difference is how. His firm spreads risk across several strategies, including rules-based quantitative models and tactical models, and then manages each position individually. The goal is not to own a slice of every market but to hold the ideas that are actually working at the time.
He describes himself as agnostic about what he buys, provided it is legal and moral. His tactical model does not hold a broad international fund simply to have international exposure. At the time of the interview, he held two single-country funds instead, because those markets were behaving the way he wanted. Owning something only for the sake of balance, he argues, adds little.
Clients, he notes, rarely say they are grateful to be diversified during a falling market; they look at the starting and ending balance. That is the practical test he applies. His book, Evidence-Based Investing: To Invest Well Over a Long-Term, Sometimes You Have to First Survive the Short-Term, sets out this approach for advisers and everyday savers alike.
3. A process for surviving the short term
Hicks says most people sit between day traders and true long-term investors, a group he calls sophisticated savers. Unlike a restaurant owner, a stock investor can exit a bad decision quickly, so he believes a portfolio should be managed rather than left alone. What matters is having a process that calms anxiety and holds steady through headlines and political noise.
A private pilot, he compares investing to flying through turbulence. The rule is to fly the airplane and stay ahead of it, which for an investor means knowing in advance where a position will be sold. He also uses a composite indicator he calls the VSSI, which works like a stoplight and helps him explain market conditions to clients.
He is equally skeptical of economic forecasts. In his view the stock market tends to lead the economy rather than follow it, so trying to predict recessions from economic data rarely helps. Studying market history, including the difficult years from 1965 to 1979, gives a better sense of what can happen and how a disciplined process should respond.