Investing
Question what you were taught: Theodore Hicks on investing after two crashes
A career that began 13 months before the dot-com crash taught Theodore Hicks that following the textbook is not the same as protecting a client.
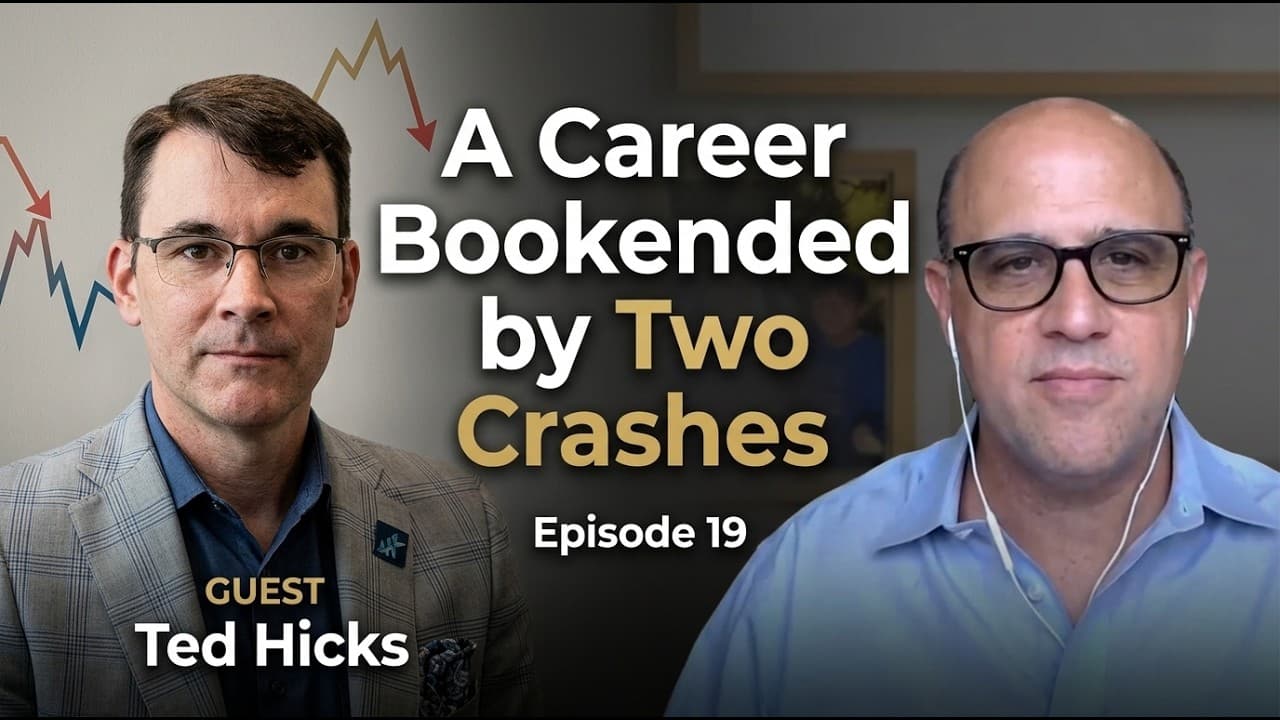
A Career Bookended by Two Crashes | Scaling Alpha Ep. 19
Video from Scaling Alpha.
Generated from the canonical interview transcript and validated against source data by Guests on Air.
What did two market crashes teach Theodore Hicks about protecting wealth?
Theodore Hicks learned that doing everything the industry teaches, from diversification to fixed allocations, did not shield clients in the dot-com crash or the 2008 crisis. He began questioning those theories, studied technical analysis, and now manages risk actively with a rules-based process, protecting wealth first because deep losses take far larger gains to recover.
Theodore Hicks joined the wealth management industry in February 1999, fresh out of NC State, and watched the market start falling 13 months later. His firm's leaders told him it was a once-in-a-career crisis and that it was good to get it over with early. He accepted that, kept his head down and carried on serving clients.
Then the 2008 global financial crisis arrived, a few months after he had bought a new minivan and a bigger house for his growing family. The message from his firm sounded almost identical. He asked himself how many once-in-a-career crises he was supposed to go through, and that question changed the direction of his career.
Speaking on the Scaling Alpha podcast, Hicks, founder and chief investment officer of Hicks & Associates Wealth Management, explained how two bear markets pushed him to question what he had been taught. The result is an evidence-based, rules-driven way of managing money that puts the protection of wealth ahead of the hunt for growth.
Key takeaways
- Doing everything the industry teaches did not protect clients in 2000 or 2008, which is why Hicks now questions it.
- Losses work against investors: a 50% decline needs a 100% gain just to get back to break even.
- Static rebalancing can mean selling winners and buying losers without asking what the evidence says now.
- Hicks puts guardrails around a portfolio first and pursues growth second, using rules instead of gut feel.
1. Two crashes that broke the textbook
Hicks says he and his colleagues were doing everything academia and the industry recommend. Clients were diversified, focused on the long term and held to an asset allocation policy. Yet in both downturns, portfolios still took heavy damage. In his words, they all still got punched in the face, despite following the rules they had been given.
That experience was when, as he puts it, the scales began to fall from his eyes. He realized that the next crisis is not a question of if but when, and that hoping each one would be the last was not a plan. What he needed was a process that would guide decisions calmly, whatever the headlines were saying.
He is open about the fact that he cannot see the future, and he jokes that he even got the timing of his own grandchild's arrival wrong. That humility is the point. Because nobody can predict the next downturn, an adviser needs rules that respond to what markets are actually doing, not theories that assume diversification will fix every problem.
2. Asking questions until a new answer appeared
After 2008, Hicks went looking for what he was missing. He already held the CFP designation, so he asked wholesalers, research teams and colleagues the same question: what else should he study? Most people pointed him toward two familiar designations, but neither felt like a genuinely new perspective on the problem he had lived through twice.
Then a CFA candidate mentioned the Chartered Market Technician program. Technical analysis, Hicks explains, tries to solve the same problem as fundamental analysis: finding assets with a good chance of rising. The difference is that a fundamental analyst says what should happen, while a technical analyst describes what is happening in prices right now.
He frames it in terms of basic economics and human nature, which do not change. Price charts are not prophetic, he says, but they are suggestive. When buyers outweigh sellers, demand outweighs supply and prices tend to rise. That idea runs through his book, Evidence-Based Investing: To Invest Well Over a Long-Term, Sometimes You Have to First Survive the Short-Term, which challenges much of the conventional wisdom he was trained on.
3. Why guardrails come before growth
Hicks calls the idea that everyone is a pure long-term investor a myth. Most people are not day traders, he says, but they still open their monthly statements and react to what they see. He believes most investors live somewhere in the middle, and technical analysis helps fill the gap between long-term theory and short-term evidence.
The math of losses drives his approach. A 5% loss needs roughly a 5.3% gain to recover, and a 10% loss needs about 11.1%. A 50% loss needs a 100% return just to break even. For someone close to retirement, a deep drawdown can delay plans, damage confidence and shrink the legacy they hoped to leave.
So his firm uses a weight-of-the-evidence system built from 14 binary indicators, two quantitative models and two tactical strategies, all managed at the model level. With near-zero trading costs and most assets inside IRAs, he sees little reason not to move into a protective position when the evidence says so. His parting advice was simple: question everything.