
February 26, 2026
Is Bankruptcy Just a Side Effect of Midlife Crisis? Interview with Barry Levine
Sound bites
The thing is, as I said to you before, it's only money. Thank God it's not their health.
In this episode
Barry Levine talks about bankruptcy as a practical reset for midlife debt, including when to act, what chapter 7 and chapter 13 mean, and how creditors pursue people.
- Financial fear and inertia keep many people from acting until lawsuits, foreclosures, or garnishments arrive.
- Proactive debt planning means looking at what assets are at risk and trying to become judgment proof.
- Chapter 7 can bring a discharge in about four months, while chapter 13 usually runs on a five year repayment plan.
- Chapter 13 can also be used to catch up on mortgage arrears while keeping current payments going.
- Small businesses may use subchapter V, a streamlined chapter 11 process designed for smaller operations.
Transcript
ShowHide
Automatic captions of the conversation. They can contain errors and do not name who is speaking.
Welcome to the Ask for the Skinny podcast with a guest. I'm proud to present Barry Levine. Levine. But that's okay. Welcome to the show, Barry. Please tell us more about yourself. What's your story? Well, you know, I always tell people I'm just an old hippie who happens to practice law. I grew up in Brooklyn. I've been living in Massachusetts for really longer than I can remember. And I've been representing debtors now, as I was explaining to Peter, December 19th will be 45 years. And you know, I pretty much anybody who has financial problems, I hope to be the guy they deal with to find a solution for it.
And I try to make the process uh easy. You know, people have a great fear of bankruptcy and the unknown and things along like that. You know, I don't tell them right away about the ritual sacrifices. I I wait for later for that. But you know, the thing is, as I said to you before, it's only money. Thank God it's not their health. So, that's who I am. So, my idea is to name this podcast how midlifers use bankruptcy as a tool. Can we talk about that and uh when we have accumulated a lot of debt in our midlife, it often feels like we are slave to this debt.
So, what is the way out? How should we prepare? How should we mentally prepare? What should we expect? Well, you know, the the thing is, you know, one of the things that provides a lot of business for me is the fact that you know, a lot of people don't have the intestinal fortitude to deal with creditors and the lawsuits and this and that. And granted, I've been doing this a long time. And a lawsuit, you know, recently I found that people I'm filing bankruptcies in the time that we up until we file bankruptcy, they'll get served a lawsuit and they'll get served a this.
And you know, they drive me crazy about it, but the reality is it's meaningless because if anything, you'll discharge the debt in your bankruptcy and instead of being just a general unsecured debt, it'll be a an unsecured debt with a judgment. They're still getting zilch. You know, but I think, as I mentioned before when we were chatting, people need to sort of be proactive. You know, you if you're a small business person or even an individual, you need to look at yourself and say, "Well, if the hits the fan, what am I at risk of losing?
You know, what exposure do I have? And once you analyze that, you try to figure out a way to make yourself judgment proof. You know, the the best way to be is judgment proof because you can take your million-dollar judgments and I don't know if people will know what I'm saying. You could wipe your toches with them. That's how that's what they're they're worthless. But you know, the problem is most people you know, I suffer from a good deal of inertia and most people suffer from the same thing, so nobody does anything.
And surprisingly, I'll have people call me up on a Friday morning and saying my house is being foreclosed upon this afternoon. And you know, it's still America. That doesn't happen. You get notices over a period of months. You know, and so where's this person been been? And and that's the problem. You know, people very often are reactive. I know I am. And you have to try and you know, it's not a fan favorite of mine. Need to be pre-proactive. You know, to look at what can hit you. You know, especially if you're in business, a small business person.
Cuz usually you sign personal guarantees. And do you have a house? Is there equity in the house? Do you have a bank account with thousands of dollars in it that may not be exempt if something happens? These are things you should be aware of. You know, ignorance and my mother always thought ignorance was bliss, but it doesn't work that way. So, how many people are filing for bankruptcy these days? We we we have Well, I the the numbers, in my opinion, and if my assistant was here, I'd call her in too because we've been together for 18 years, are staggering.
Uh since January of 2024, we have been the busiest we've ever been. And I'm talking about filing bankruptcies for you know, there was a time where if somebody would come to me with $10,000 worth of debt and they'd be in their 20s, I'd say, "Hey, maybe you don't want to file a bankruptcy. Maybe you want to do something else." But nowadays, from the 20s to to people in their 80s, and you know, the unfortunate thing about it is somebody who's in their 80s, you know, my feeling to say to them is you probably won't live long enough for them to collect the money from you.
But the anxiety of the creditor calls and the notices and the lawsuits, they go through a bankruptcy. They're on social security. What does the creditor think they're going to get from them? But that's what you have to do. I mean, it's it's running you know, and the other thing that's been happening a lot is that a lot of people during COVID here, the SBA was very kind to small businesses and they were giving a lot of businesses uh very nice loans. Probably businesses that didn't deserve it, but they got very nice loans.
And a lot of these businesses were able to survive COVID, but now buying has changed, selling has changed. They didn't survive that. And I'm finding that what we're doing is liquidating the business, not necessarily through a Chapter 11. There are other ways to do that in Massachusetts. And then filing a personal bankruptcy for the principal who has been saddled with the SBA loans. And you know, people don't seem to realize that while certain taxes may be non-dischargeable in a bankruptcy, like trust fund taxes, withholding taxes, you know, that the employer takes out but doesn't necessarily pay to the government, uh the SBA is a dischargeable debt.
And you know, that's what's what what I'm finding now. It's very busy. And it's across you know, I friendly with a lot of the trustees. It's across the board. Can we also discuss We we mentioned that in in in preparation for this podcast, there are also a lot of medical bills to pay, especially if you go into cancer treatment or stuff like that. How does that work? Is there any I I missed I missed that. There are a lot of medical bills to pay if you go into cancer treatment or similar. They they get discharged in a bankruptcy like anybody else.
You know, it's it's unfortunate. You know, there are a lot of people. I mean, as we we mentioned, to me the three things that are causing bankruptcies and been a number of years now are a person who's been downsized. You know, they were making X, now they're making X minus Y. A person who's lost their job. And somebody who has medical bills and not covered by insurance. And they'll croak you. You know, I know from my own experience, you you go in for a checkup, it costs thousands of dollars. And and you know, not everybody has coverage for that.
And the only way to get rid of that, at least I look at it, and you know, I don't you know, I do podcasts where I rant about debt settlement companies. Don't get me started about that. You know, if you're blind in your left eye and you lost your right arm, we have a special program for you. It's it's all And you get 1099s and all this other stuff. But they the medical bills, they go away like anything else. You know, it's it's the it's the easiest way to deal with them. I mean, you know, years ago, listen, nobody likes to file a bankruptcy.
And years ago, I had a very nice letter I used to send out on a word processor. I don't know if you remember those. And you know, it would tell the creditors my clients retained me to file a bankruptcy, but they'd rather pay you 10 cents on the dollar than file a bankruptcy. And the creditors' response was, "We'll take 60 cents on the dollar." And you know, I would not really go into an extended back and forth, but I say, "Listen, they can pay me a couple of grand, not pay you a dime, and be done with it." Mhm. Oh, no.
60 cents. It's like, "Okay, you'll get the docket number." And you know, that's how they deal with these things. It's it's not you know, the you have to realize, and I think I said, it's it's only money. You you know, people uh and I know it's easy for me to say, it's what I do for a living. Though I do open heart surgery in the weekends. I learned on Google, you know, I in the back alleys. It's I make a lot of money that way. The uh you know, it it's you just have to do it because otherwise, like I said, you're an indentured servant.
I mean, you know, I have people that say after they pay their credit cards, they have $200 left over. They have three kids and have the rent to pay. How far does that go? You know what meshugas is? No. Insanity in Yiddish. Ugh. That's what it is. It's meshugas. Okay. So, there are situations where there's no other way to deal with financial issues than bankruptcy. And um you said that we first have to be mentally prepared to do it cuz it it still uh let's call it it has like this um negative connotation. It it still has a stigma.
I mean, you know, I have people who you know, they tell me they'd never believe they're sitting here and doing this. I mean, like I said, I'm a I'm I'm a cynic. You have to do what you have to do. Uh you can't worry about it. The credit what Actually, you know what the credit card companies do? You know, they'll they'll have people that'll come in and they'll say, "Well, they charged the debt off." Mhm. Charging the debt off means nothing. What they What they do is it it really means they're not going to collect it from you.
But 5 years later, they'll sell it to some bottom feeder who buy a whole portfolio of their charged off credit cards for 10 cents on the dollar, and you'll get a letter from Joe Schmoe that says, "You now owe us 10 grand." Mhm. You know, and the only way that goes away, and it happens when people go bankrupt, too. You know, after they get their discharge, they'll get a letter like that. And I have a very nice letter that I send those people. But, you know, it it it it you the only way to get rid of it is to file a bankruptcy.
You know, if you manage to get a mutual discharge from a creditor by paying them something, I don't know. That's your business. If it happens, more power to you. But, very often the creditor will give you a 1099 forgiveness of debt, which could become a taxable event, whereas in bankruptcy, your debt is discharged by operation of law. There are no 1099 forgivenesses of debt involved. So, it's you know, it's you may not want to, but you must. Okay. So, we talked about stigma. With Can we Can we discuss a bit chapter 7 and chapter 11?
Sure. Who should Who should think about chapter 7 and who should go for chapter 11? Well, the the for individuals, the one thing you forgot the chapter 13. Of for individuals, it really comes down to chapter 7s and chapter 13s, which is all uh guided by household income. So, for instance, and I have a little handy-dandy chart here that uh if you're a household of four in Massachusetts, every state has a different standard based on IRS statistics. If you make over $172,000, you are a chapter 13 candidate. And the difference between the two is a chapter 7, which is what I prefer, is a straight liquidation.
If we would file, you know, your case wouldn't go on for 8 years unless there was some really interesting stuff going on. If we filed your case today, 4 months from now you get your discharge in chapter 7. Right? A chapter 13 ties people into a 5-year payment plan. And there's a little computer program that determines what your disposable income is, which is my father used to say if he had wheels, he'd be a baby carriage. It's very often the case it has nothing to do with reality. But, you know, I have if you're a high earner, you can find yourself in a chapter 13 making a a pretty sizable payment every month to your creditors, and in 5 years you get a discharge.
Mhm. You know, that to me doesn't do anything for anybody. Uh chapter 13s also used or can be used uh for people who uh have mortgage arrears. Uh in a chapter 13, provided you can make all your current mortgage payments and expenses, you can pay your mortgage arrears out of a 5 years. So, this way, you know, rather than face a foreclosure, if you have and I've had people I have a a young gentleman with a mortgage arrears of $180,000, uh you can theoretically, and I do say that truly, theoretically pay it through 5 years of the plan.
You know, of course you get to the issue with any house worth paying the $6,000 mortgage plus the four $5,000 plan payment, I don't know. It's not my house. But, you know, those are the differences. On the rare occasion an individual may have to file for a chapter 11 because they're above the statutory limit of 13s as to amounts of debt, Mhm. or they have a full-blown business that they happen to be running as a sole proprietorship for some bizarre reason. Uh but, you know, chapter 11s are just another thing altogether.
What they have now, uh rather than uh putting every small business, and I deal mostly with small businesses, they have a process that's called the subchapter V uh chapter 11, which is for small businesses. It's uh a sort of a streamlined process. Uh I'm just going through one now. Uh takes about a year. Whereas a full-blown chapter 11 can can be endless. Uh but, you know, you don't find many individuals filing chapter 11s. Uh it's it's not uh like I said, only if they're above and off that I don't know what has to do with a mortgage, the total amount of mortgage debt and total amount of unsecured debt.
But, 7 and 13 is what most individuals file. And like I said, the my preference is a 7 because, you know, you file it, and 4 months later you get your discharge. You know, there's in both of them, so uh there's what they call a section 341 meeting, called a meeting of creditors. Uh it has been decades since a creditor has actually shown up at one of these meetings. Uh in the chapter 7, when the notice goes out, uh the notice usually says that this is an assetless case. Don't call us, we'll call you. And even though the meetings take place much like we're sitting here on Zoom by Zoom, they don't even bother.
Uh and on top of that, the the chapter 7 trustees, who are all attorneys like myself, uh most of whom around these parts I know for 45 years, they get paid 65 bucks in an assetless case. They don't tend to spend a lot of time. In fact, what I tell clients is that unless you're the first case when they start, the odds are that the wait will be longer than the meeting itself. The chapter 13 also has a 341 meeting. It's a little more serious. I dress like this for both of them. Uh and uh uh sometimes I have a t-shirt that says, "I saw Jerry." Uh but, uh it the only thing she really is interested in is the plan payments because the chapter 13 uh is a self-funding office, the chapter 13 trustee who administers the 13.
So, she basically gets a 10% of what the payments are over the course of the 5 years. You know, so it you know, they do all right. But, those for for individuals, uh that's what I always recommend. For small businesses that are just looking to go out of business, uh I don't prefer I prefer not to put them through the intrusiveness of a chapter 7. And in Massachusetts, there's something called an assignment for the benefit of creditors, which lets you liquidate a business voluntarily. And the reason I do that is um in a chapter 7, corporations and LLCs don't get discharges.
The reasons individuals don't do assignments is in a chapter 7, they get a discharge, and all the debts become yesterday's news. You know, what happens for a chapter 7 corporation is if there are any assets, they get liquidated, but the corporation still exists. It has nothing, but it doesn't get a discharge of its debts. If there are any assets, they get distributed to the creditors. So, the assignment is the same thing, and there's no 341 meeting. It's basically a paper transaction, which, you know, I recommend for small businesses.
Okay, can we talk ab- a bit about uh credit uh ratings? W- What happened with our credit score? Uh Credit scores, you know, we have a little uh app that tells us um uh we pull a credit report before we file somebody's bankruptcy, and it tells us what somebody's credit score is going to be in a year, and most of them go up 100 points. You know, the it sure, it's going to impact your credit score for a few years, and it's going to make it more difficult to get a loan, a credit card, but, you know, as we mentioned, the you know, like I say, I keep Kafka on my desk for a reason.
Uh creditors look at most debtors, you know, they make a decent living. They make 40, 50, 60, some of them even more a year, uh grand a year, and post-discharge, they'll give somebody like that a credit card with a little, you know, $500 line of credit, figuring that they can't file bankruptcy again for 8 years and they'll see what happens. So, you know, that's out there. And you know, the other way to develop new credit, you know, as I mentioned is this is a long the easier said than done is to try to develop a relationship with a small bank that could look at you as an individual that, you know, there was a reason behind why you filed bankruptcy.
It wasn't because you took a cruise around the world. It's because you lost a job or got fired or something medical happened or something like that. Um rather than like a Bank of America, you know, they they don't give you the time of day. Uh the other thing that people can do, well, creditors who go through a bankruptcy who continue to have mortgages and uh car payments, that will stand in their favor provided I don't know if you want to listen to a lot of legal Uh provided they reaffirm the debt. Do you know what Do you know what happens?
And this is another reason I can This is very interesting. Uh when you go through a bankruptcy and you have a car loan or a mortgage on your house and you do nothing. You get your bankruptcy discharged and you just keep making the mortgage of the car is a better example. You keep making the car payments and 10 months later the car shits the bed, dies. You still owe 30 grand on the car. Mhm. By doing nothing and going through bankruptcy, you've discharged that debt. Okay. So, you'd not you wouldn't be on the hook for it.
The same thing if you paid the mortgage as long as you could and they foreclosed and there was a deficiency. Because you you got your discharge, that deficiency is discharged. Well, of course, there's a process to deal with that and it's called the reaffirmation of the debt. And what happens and I use it I use it mostly with real estate, not necessarily cars because cars you have to look at the value of the car against what you're agreeing to reaffirm. You know, if the car is worth 10 grand and the loan is 30 grand, well, you want to still be on the hook for it if the car dies.
Um but uh what the reaffirmation agreement is, the bank, the lender sends you this, we complete it with the debtor's income, expenses, send it back to the creditor who sends it to the court and the judge has to approve it. Mhm. And by approving it, it means that the debt survives your discharge. So, the story I'm going to tell is a client of mine back back in the aughts before the the compu- there was a big computer business crash. His business died. He had no income. We filed a bankruptcy. He had a house somewhere south of Boston that he couldn't make the mortgage payments on and the house was significantly underwater.
And so, there was no way the court would allow him to reaffirm the debt because, you know, he has no income. They'll foreclose tomorrow. He's going to What's the What purpose does the bankruptcy serve if he's on the hook for the deficiency? So, he got his discharge and I didn't hear from him probably probably 7 8 years. He calls me up. He wanted He somehow he managed to keep the house, make the mortgage payments to his bank. And mortgage rates had gone down. It must have been in the teens. And he wanted to refinance the house.
So, he went to his bank and he said, "Listen, I've been making 8 years worth of payments on this mortgage and I'd like to reaffirm I mean, I'd like to refinance it." They do a credit report. They go, "You can't. You never reaffirmed the debt. It was discharged in your bankruptcy." Mhm. "But I've been paying it for 8 years." He had to go to a different bank. Mhm. Cuz according to the bank, even though they got 10 years worth of payments, it was discharged. So, what they do with the payments? You know, and I I actually I was friendly with a legislator here and I wrote a statute but they had better things to do than pass it because I just wanted to make them have to report the payments.
Mhm. You know, what's the What's the problem with that? But that's the thing I was going to get at, you know, so if you go that payment route and it's going to you know, when you don't reaffirm it, it that's why I never do it with houses because people eventually want to get another mortgage or something like that. But cars, you know, the problem with cars nowadays, you you talk about midlife crises. You know, I've had a number of people in the the I My midlife crisis was decades ago, but they're much younger than both of us probably.
And you know, they see the fancy new car and what the car dealers do here now is so you're underwater in car A, they agree to put them into car B, which creates a more underwater loan for them. So, now they're driving a $20,000 car that has a $50,000 loan on it. And getting back to Michigan, I mean, what are we paying on? And like something like that, I would never have them reaffirm that debt. That would be insane. Mhm. You know, it's like I rarely have them reaffirm leases that are at the end of the lease time because they'll nick you for all the charges.
So, how how how should we how should we um finish this? How should we wrap up? When should people go and uh say enough is enough? I I I I I can no longer take this burden. When is the right time? know, I I I think it comes down to and you know, it comes down to shoveling against the tide. You know, if at the end of the month you barely have enough money to eat or you can't even go out to eat and I'm talking necessary not necessarily a fancy restaurant. You know, McDonald's can cost you 100 bucks today for a family of four.
You know, you have to you have to be cognizant of where your money is going and the thing is you can't be afraid of saying, "I can't pay these people anymore." You know, so what's going to happen? They'll nudge you with a phone call and now because everybody gives them their cell phone numbers and email addresses, they'll send you an email. I mean, now if you have a credit card, excuse me, and the it's very annoying. Uh and the payments the payment is due on the 12th. The 12th is a Sunday. They can't make a payment on a Sunday.
On the 13th, you get a payment that it notice an email that it's overdue. Mhm. And I'm one of those people that annoys me. It makes me feel like not paying. But you know, the thing is that's what you have to be aware of. I mean, and and the thing is, you know, perhaps and and and we should touch a little bit. I don't know how much time we have. You you can't be afraid of the collection process because it's it's geared to buy you time. The thing is, you know, creditors, you know, there was a comedian he I don't know if you remember when you used to travel in Europe, you used to be able to send correspondence or if you needed money from mom and dad to an American Express office.
He used to send his bills to an American Express office and they would just continue to go around the world. He'd never get them. But what you want to do is when the the creditor itself doesn't like to give up the debt because now they have to share it with some someone if they're getting anything. So, they will continue to send nudge you calls, emails. They'll eventually send you a letter and that letter is going to say, "If you dispute the amount, send it to us in writing in 30 days." They don't charge you to dispute the amount.
It's a credit card. You either bought the or you didn't buy the stuff. But you dispute it because it buys time. And it costs you What's the What's the stamp? 72 cents now? Used to be a nickel. Uh it you know, but it's worth sending that correspondence. Then the creditor will eventually get annoyed and send it to a collection agency. All the collection agency can do is nudge you, too. Send you letters, call you, but they'll send you that letter with that if you dispute this, send us a notice within 30 days. You send the dispute letter, it even buys more time because it has to go from the collection agency back to the creditor and then back to the collection agency back to you.
Then they'll eventually because the collection agency doesn't get paid, they'll send it to an attorney. And hopefully the attorney is in the state you live in because often it'll be in some other state and who cares? But they'll send you that same demand letter. You send them the same You change the address. E, but you send them that And now you bought time. And you know, uh But but but when is the time to quit? And say The the you know, I was going to say the only thing that concerns me from a bankruptcy point of view that needs to be acted upon quickly, a foreclosure, a wage garnishment, and a seizure by the IRS or the Mass Department of Revenue or something like that.
Creditor is suing you, let's take as much time as we want. Okay, Barry. Thank you very much for these insights. Before we finish, please tell tell us where can our listeners and viewers You can look look me up online, www.levineslaw.com. That's l e v i n e s l a w.com. Or you can email me because I do I hate talking on the phone, but I do answer emails. Barry and it's with a small b at levineslaw.com. Or you can see my podcasts on YouTube and I actually wrote a book and it's available on Amazon, Bankruptcy Through the Looking Glass.
I hear it's a good laugh. Thank you very much and I will include all the links in the description below. Thank you, Barry, for being my guest today. Stay well, everyone.
About Barry Levine
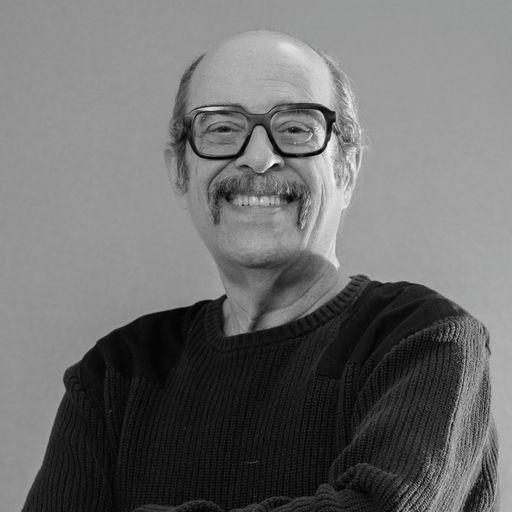
Bankruptcy Attorney and Debt Strategist for Everyday Americans in Crisis
45 years Representing people in financial difficulty1 book Author, Personal Bankruptcy Through The Looking Glass322 videos On his own bankruptcy YouTube channelBankruptcy attorney Massachusetts
The calls often come late: someone has ignored letters from the IRS, missed too many loan payments, or watched their small business slowly bleed out. They don’t open with legal questions. They ask if there’s any way out.
For almost 45 years, Barry Levine has answered that question with calm, practical guidance. A Massachusetts-based bankruptcy attorney, he works with individuals and small business owners navigating serious financial strain, people who are scared, out of options, and unsure what the next step even looks like. His work isn’t about judgement or quick fixes. It’s about helping people understand what tools are available, how the system works, and what choices they can still make.
What Barry sees again and again is that fear, not just debt, is what traps people. The legal process has structure, options, and predictable outcomes; what derails most clients is the panic that keeps them frozen in place. Barry’s role is to bring order to the chaos. With each case, he applies decades of legal experience to help clients understand what’s happening, what’s possible, and how to move forward with a strategy that restores both stability and control.
He first started practicing bankruptcy law in a hands-on Boston office while still in law school, learning case by case how to navigate both paperwork and people.
More from Barry Levine
All episodes → The Agent of WealthFinancial Crisis, Bankruptcy and Starting Over With Barry LevineOct 2026Play episode →
 School for Startups RadioOctober 5, 2026 – EdTech Find Your Grind Nick Gross and Bankruptcy Attorney Barry LevineOct 2026Play episode →
 Financial Mastery SimplifiedHow Bankruptcy Really Affects Your Credit and Home LoanSep 2026Play episode →
 Money Talk With TiffWhat Bankruptcy Actually Does with Attorney Barry LevineAug 2026Play episode →
 Wealth B-HersFear, not Debt with Barry LevineJul 2026Play episode →
 Us People PodcastThe Law We Decide To Practice - Barry Levine - Attorney At Law #314Apr 2026Play episode →
 Chrisman Commentary - Daily Mortgage News4.14.26 Fines Versus Taxes; Attorney Barry Levine on Delinquencies and Foreclosures; Agency MBS PerformanceApr 2026Play episode →
 JUSTIN AND THE [FOOD] ENTREPRENEURSEpisode 520: Barry Levine of The Law Offices of Barry R. Levine - Beverly, MA. Shielding Your Personal Assets. Avoid Bankruptcy Before It Hits. Legal Lifelines for Food Entrepreneurs. Cost Accounting.Apr 2026Play episode →
 How Much Can I Make? — Real Jobs. Real People. Real Money.Bankruptcy Lawyer Explains Chapter 7, Chapter 13 & Getting a Fresh StartMar 2026Play episode →