
January 17, 2026
Episode 85: Legal Strategies Every Senior Should Know | Barry R. Levine, Esq.
Sound bites
The problem that people have, and mostly, especially elderly people, you get notices in the mail, you get lawsuits, you know, nobody knows what it's all about, is peace of mind.
The reality is, if you're that old, you're probably not going to be alive by the time they go to collect from you.
In this episode
Barry Levine talks about how bankruptcy can help seniors handle debt, reduce fear, and regain peace of mind.
- Bankruptcy can feel like a financial reset instead of a failure, especially for seniors facing notices, lawsuits, and creditor calls.
- Most clients worry far more about the 341 meeting than the meeting itself, which is usually straightforward and informal.
- Asset exemptions can let many debtors keep important property, depending on whether federal or state exemptions apply.
- Financially vulnerable people are targets for phone scams, so money questions should be answered in writing when possible.
Chapters
Written from the transcript. Pick a chapter to play the video from that point.
Transcript
Automatic captions of the conversation. They can contain errors and do not name who is speaking.
You know, the problem that people have, and mostly, especially elderly people, you get notices in the mail, you get lawsuits, you know, nobody knows what it's all about, is peace of mind. You know, for me, I've filed bankruptcies for people in their 80s. And listen, I'm a practical guy. The reality is, if you're that old, you're probably not gonna be alive by the time they go to collect them. Hey, this is Matt Helton with One Trust Home Loans, your reverse mortgage experts, and you found the Serving Seniors Podcast, where we highlight those businesses and professionals that help seniors thrive in retirement.
Today, we have another one of those awesome, awesome people. We have Mr. Barry Levine, and Barry is a self-proclaimed old hippie that practices law. And what he specializes in, he specializes in demystifying bankruptcy. He's gonna share with us how that affects seniors and how bankruptcy could be used as a tool to help them improve retirement. Barry, how are you doing today? I'm doing okay. We spoke about it being a Monday, but I'm over it already. So there you go, sir. Well, you look awake for an old hippie, especially in the middle of the afternoon, man.
How's your day going? It's true. It's getting close to my bedtime, but I managed to take a nap, so I'm staying up late today. Thank you for being here. And thank you for staying up, Barry. Pleasure. I've enjoyed chatting with you with your energy and your passion for what you do. So, look forward to learning more about you, sir. Sure. What can I tell you about bankruptcies for althococcus, old thoughts like myself. Well, how about maybe if you could even a little back, I know people love to kind of hear the background of people as far as who you are, where you're from.
How did you get into this? Maybe bring us up to speed. I'm originally from Brooklyn, though I mentioned I've been living up here since in Massachusetts since 1977. You still can't get a good fatty corn beef sandwich around here, but it's such a nice. I always wanted to be a lawyer. I did between college and law school, I work for an insolvency bankruptcy firm in Manhattan. Then while I was in law school, I worked for a guy who specialized in representing small businesses and doing debtors work. After listening to him tell me for five years that one day, Barry, this will all be yours, and then realizing it was a crock of shit.
I went out on my own and I've been representing debtors since I had a lot more hair, and since it was before it was a growth industry. In fact, I have a case now where I'm representing a six-year creditor. It's a novelty for me. We want our money and we want it now. Represent debtors, you spend most of your time coming up with excuses. When I found recently, I've been the busiest I've been in the last two years, since January of 2024. It's been nonstop. The problem that people have, and especially elderly people, you get notices in the mail, you get lawsuits, nobody knows what it's all about, is peace of mind.
For me, I've filed bankruptcies for people in their 80s. Listen, I'm a practical guy. The reality is, if you're that old, you're probably not going to be alive by the time they go to collect from you. But you can't tell people things like that, and people like peace of mind. And bankruptcy, it's not the end of the world. It's only money. I tell people, thank God it's not your health. And the credit card companies can survive. And filing a bankruptcy gets you out. They'll nudge you with phone calls, they'll send you letters.
And especially people, listen, this is what I've been doing for a long time. You want to sue me, I could care. But people, lay people don't understand that it's sort of meaningless. It's really a game, but if somebody doesn't know what's going on, it seems like a serious thing. Somebody's suing me. Well, big deal, it doesn't get them their money. But that's what they prey on. It's the same way your listeners have probably heard stories. You know, somebody calls up somebody who's elderly and says, your grandson is in a jail someplace.
Where? And, you know, I remember my mother got a call like that. My nephew lives in Italy. He wasn't in the jail in Georgia, so she knew. But, you know, people don't know these things. You know, rule of thumb is if somebody's calling you on the phone and asking you questions about money and all this other mishigas, let them send you a letter. You know, I'm old fashioned. I'm not young. Send me a letter. It means something. Forming me is meaningless. Sending me an email is meaningless. When I got a letter with your letterhead on it and a name, well, I may not take it seriously because that's the way I am, but at least it's something in writing that you can point at.
And, you know, the worst thing you can do, and that's what they prey on, is people in a tough financial situation, giving financial information to people on the phone. And the next thing you know, they nick your credit card for X number of dollars, or they hit your bank account. And, you know, people, especially if you retire on social security, you don't have a lot of assets, you can least afford it. I mean, it's a tragedy, but that's what they take advantage of. Wow, wow, that is, that's very, that's very well said and also very sad that that's where we are.
But that's, that's, that's where we are in the world. That's where we are. So Barry, when someone comes to you, shares with their central kind of maybe take us through the process where, what's a good change? Who's filing it, what you do? And then how do you walk through the process? Generally, the first step is people have to realize there's a problem. And nowadays, because we are so willing to give out our cell phone numbers, our email addresses and things like that, when you fall behind, the rule of thumb used to be three payments behind before they started to nudge you, which in Yiddish means drive you crazy.
You know, now, if you're a day late, you'll get a call on your cell phone. You're a day late. You'll get an email. You know, in fact, when I used to, when my mother was still alive and I had gotten her own cell phone number, when she passed away, that's the number I used to give out to people. You want to call her cell phone. On Advertise Day, I never checked the messages, but they needed a number. I gave them a number, make them happy. But you know, because of that, the pressure is intense, but people don't realize that the collection process itself, and I encourage potential debtors to take advantage of it, is one, you have to realize you have a problem.
When you're having difficulties making the minimum payments or you're missing the minimum payments, well, there's a problem. The next thing you have to realize, people suffer from, for lack of a better phrase, a constipation of action. Nobody likes to do anything, right? They figure they'll ignore it, but they don't go away. But the collection process itself, when I'm a creditor and I send you a notice that says, you owe me $2,000, collection laws say, I have to give you an opportunity to dispute the balance due. And I encourage, because listen, it's best that people can handle things on their own without immediately getting an attorney involved, because it shows you're not as debt ridden as you say you are.
But those letters they send you say, if you dispute the balance due, send us a notice within 30 days. You have a computer, you have a print them, make a letter, send it out, cost you nothing. What then happens is they then have to send you every invoice on the account. You don't have a dispute. It's a credit card. You either use the credit card or you didn't use the credit card. Planning the system. Now, when the creditor gets no satisfaction, I think there's some old band that uses that song. That's favorites of mine, but I won't go there.
They then send it to a collection agency. The collection agency then by law has to send you the same notice. If you dispute this amount, let us know within 30 days. Of course, hopefully you have the same letter stored someplace. Be sure to change the address and the date, but send them that same letter. So now they have to go to the original creditor, get all the invoices, and then send them to you. You'll eventually ignore the collection agency because that's the nature of life. Then they'll send it to a lawyer. Maybe the lawyer will be in your state, maybe not.
If you live in Massachusetts and you get the man letter from a lawyer in Minnesota, who gives a... They're not here. Again, that lawyer, when they send you that letter, has to have that same language in it about the dispute. You dispute it again. You're just jerking the process around, and that will eventually they'll file a lawsuit against you. And yeah, when you deal with collection law firms, everything is automated, so it's really difficult to jerk that process around, but they'll eventually get a judgment against you.
But that can take them a year or more. And then from my perspective, and I don't know, other states have the same process, so a creditor now gets a judgment against you. And, you know, aside from wiping their tuchesis with it, meaning that you can't collect anything from it, most times, they send the deputy sheriff to your house to serve the judgment. Of course, you say, where do I get, who do I write the check out to? But no, they don't get a check. And what the next step is, it's called a suit on a judgment. In Massachusetts, if that occurs and you don't show up, the court can issue a capious for your arrest, which is why most of my clients, if we get that far without them filing a bankruptcy, they show up and say, Your Honor, I've retained an attorney to file a bankruptcy.
And the judge says, come back in six months. Bankruptcy filing short circuits all this stuff. Once my office gets retained to file a bankruptcy, you start referring your creditors to us. You get letters, you get phone calls. For lack of a better phrase, I jerk them around until we file the case. Which can be, you know, generally, you know, in a perfect world, when I quote what it cost to file a bankruptcy, people will say, who do I make the checkout to? But I'm an inveterate cynic, and if you haven't been able to tell, I'm from Brooklyn, so there's no such thing as a perfect world.
So generally, you pay us like a few hundred bucks. We're retained, you can pay us over six months. It's when we file the case. But we keep their creditors at bay. You know, if you're inclined to answer the calls, you tell them, I've retained Levine. If you get a letter, you send the letter to us. I send out a response. And most of the time, especially around these parts, most of the collection agencies, firms know me. And when I say a client is gonna file a bankruptcy, I'm not, they will file. You know, they may not file tomorrow, but generally within six months, their cases will be filed.
Okay. And what's involved though, is we prepare what are called schedules and statements of affairs. Okay. The schedules are a list of your assets and liabilities and your income and expenses. The statement of affairs is how much money you've made in the last three calendar years, do you have a safe deposit box, have you been sued, do you have a separate business that you run, nothing particularly intrusive. When all this stuff is completed, before we can file a case, a potential debtor has to take a credit counseling course.
You take this course online, it takes an hour, most people finish it in 20-25 minutes. They used to make you stare at the screen until the hour elapsed, but they don't anymore, so you can go right to the next part. They ask you some questions, take your check, and at that point, we'll have sent the client the schedules and statements of affairs to review. If everything is copathetic, they'll come in the next day, sign everything, and we upload it to the bankruptcy court. What then happens is they schedule, and most of this goes for any place where there's a bankruptcy court.
They schedule 341 meeting, which is a meeting of creditors. If we would file your case today, your meeting would be about 30 days from today, probably around the middle of February. You get a notice from us, you get a notice from the court. The meetings now take place by Zoom, so my clients come to my office. They sit behind me, we stare at my monitor. Other debtors and attorneys are on the monitor with their Chapter 7 trustee. Creditors, when they get the notice of most bankruptcy filings, most cases are acidless cases, which means the debtor gets to keep their basketball and go home and continue playing.
You know what I'm saying? So they don't show up. It's been decades since the creditor has shown up. Maybe if you owe the IRS a lot of money, they may send somebody, but by and large, the credit card companies, it's just closing of a file. The trustee who gets appointed to administer your case, they're all attorneys like myself. Around here, I know most of them are over 40 years. And in an assetless case, they get paid 65 bucks. They don't tend to spend a lot of time. Okay. It generally is what I tell clients several things.
The anxiety of the 341 meeting is a lot worse than the reality of the meeting. It's like, usually we kibitz. Like, I know the trustees, you know. I'd be dressed in, you know, cold weather or sweat, a sweater like this. And in the warmer weather, I wear my I saw Jerry T-shirt. And, you know, it's very informal. Before the meeting, we send the trustee a copy of the recently filed tax return, 60 days worth of pay stubs, praise value of the house, mortgage statements. And the 341 meeting itself, you know, the trustee identifies the debtor.
Generally, it's by asking you to read into the record the last four of your social and the last four of your driver's license. Then the trustee will ask you to, if you're wearing glasses, they'll look at the picture on your driver's license and say, this is who you are. They'll ask you to raise your right hand and swear you in. Then they'll ask you a series of questions. Most trustees, and I'm sure this is nationwide, ask the same sort of questions. They can review the schedules and statements of affairs before you file the case, which is all the documents.
Are they true and accurate statement of your assets and liabilities on the date you file the case? Are there any changes that you'd like to make? Then for people who either list real estate or don't list any real estate, they generally ask, have you ever owned any other real estate within the last four years, six years, or maybe you remember when Fred and Wilma tooled around bedrock. Whatever the answer it is, they don't have it now, that's for sure. Then the last, do you pay alimony or child support? Might you have any claims against anybody?
Actually, the only thing that works prospectively is if you come into an inheritance within the six months of the filing, you're supposed to let me know. In 45 years, it's happened once. You found one honest person. He left the kid 3,500 bucks and he got to keep it. Because one thing people have to appreciate is that most assets are exempt when you file a bank bankruptcy. You have a choice of either federal exemptions, which in certain things are more liberal than state exemptions or state exemptions. Certain states limit you to one or the other.
Offhand, I don't know. I think I have no clue. But for instance, like we spoke about Massachusetts, aside from Florida, which has probably the best homestead, you just have to move there and say, I'm living here and it covers all the equity. Why lots of rich people move there in the middle of the night. Massachusetts, probably from what I know, has the second best because it covers up to a million dollars worth of equity. If a person files a bankruptcy, which of course is a big concern, am I going to lose my house?
Is somebody going to come look at the contents? Nobody wants the house as long as you make the payments. But in Massachusetts, here's the value of the house, here's the mortgage statement or statements, and here's a copy of the homestead. Like I said, getting back to the basketball, the trustee is not going to sell your house just because he cannot. Well, it was about the kid who couldn't play, but he brought the ball every weekend. There you go. My dad's friend has a good story that says he was terrible at basketball, but because his school did not have a bus, his dad was smart enough to buy a station wagon, and that's why my dad made the basketball team is because he was the best.
Well, I always felt that if I was six foot two, I would have been, I was one of those short, shifty guards with a tough outside shot. But the only claim to fame is from Bernie King and Albert King. Yeah, I went to school with their older brother who wasn't such a great basketball player. Well, that's great. That is awesome. To piggyback on what you were saying too, and that's where we come in, and what we do is a lot of people are worried too if they file bankruptcy, they'll never be able to get another mortgage or never be able to finance real estate.
It isn't the end of the world. I mean, I will say up until 2008 when the banks had their last meltdown, I've been through a number of these in my career. It has become a little more difficult to get new financing. You have to go through more of the rectal exam kind of thing that you might have to do for a long time. But clients of mine refinance, they buy homes, they may not get the best mortgage rates, but they'll get a mortgage rate. And you'll be surprised, which is one of the reasons I keep Kafka's biography on my desk, is that post discharge, creditors look at debtors who make a decent living.
A lot of people, you know, social security, pensions, just working, make good livings. You can't file a bankruptcy again for eight years. So it gives them a small credit card with a small line of credit. Make the payments, life is grand. The other thing I try to suggest to people, which may be easier said than done, is try to develop a relationship with a small bank that can look at you as more than just a FICA score. You know, as an individual, nowadays most people file bankruptcy because they had a small business that didn't survive COVID or survived COVID with a lot of money that the government gave them and now can't survive.
So the business goes out, the individual files bankruptcy because lots of people don't realize that SBA loans can be discharged in bankruptcy. The other thing is medical debt that is not covered by insurance. And the last is people, you know, making 250,000, suddenly they lose a job or they're making $100,000. You can't keep all the balls up in the air. And, you know, I just, Trump just, I haven't seen many of the banks jumping on the bandwagon, but he suggested they lower their interest rates. I don't know if you saw that.
Yeah. Oh, yeah, yeah. And, you know, the thing is, if they were 10% and, you know, most people, I'm an entertaining guy, you know, I have a lot of fun. I joke like that, like an old Jew who tells jokes. And, but, you know, people don't want to talk to bankruptcy attorneys. And you know, when you're paying, you know, if you miss a payment, your interest rate goes from 18% to 28%. And you know, that little thing, if you make the minimum payment, that says your children's children's children will pay this debt. I mean, it's not going to happen.
Right. And, you know, they leave people, you know, because people don't seem to appreciate or realize that when all their money is going to pay their creditors, they're an indentured servant. And slavery went out in the 1860s until they freed themselves from being a slave. I mean, do you need to put food on the table for you and the kids or pay Citibank? Citibank. And, you know, the worst part about it is that so now a lot of these people will go bankrupt. They'll discharge their debts. And three or four years later, Citibank will have sent their bad credit card account to some bottom feeder who now says, hey, you now owe us the money, not realizing they've gone bankrupt or anything.
And it adds insult to injury. It's the same way people don't realize that when something is charged off, it's meaningless. That is awesome. You're doing a great job of really educating, but also getting people out of those shackles. Well, then don't get me started. You know, the one thing I haven't touched on is the debt settlement companies. You know, if you're missing your right arm and you're blind in your left eye, we have a special program for you. It's like the, I don't want to say her name. The ones who offer, settle the IRS pennies on the dollar.
It's true. I know in Massachusetts, if you have to owe a debt of taxing authority, you're better off owing the IRS than the Department of Revenue. They're much tougher to deal with, the state. You actually, if you have no money, you have to prove to them that you're judgment and collection proof. The IRS though, those things you see, you may not be able to settle for pennies on the dollar because that's all. But they look at you as how much they can collect from you. And the process, maybe you've spoken about it with people who own the IRS, it's called an offer and compromise.
If I owe the IRS $100,000 and there's no way in hell they're ever going to get that from me, here's a liquidation analysis and here's what you can hope to get from me over five years, and that forms the basis of an offer and they'll take it. That's great. Well, great, great advice. And Barry, that's why I wanted to connect with you too, is because when clients after bankruptcy, they have to rebuild their credit, work their way up to get a mortgage. But what we do on the senior lending side, if folks are 62 and older, we don't have a minimum credit score.
So our options, it's the new and improved consumer protected version of a reverse mortgage. There's no minimum credit score. We just recently helped to link up. 426 credit score. I tell you, I look at it all as you reach a certain age, people who are my age, older, and then they're thinking about filing a bankruptcy, and it's like, your credit score? Well, there's a firehouse. I mean, you'll be able to find a car. That's not, things like that aren't a problem. So you'd be surprised. But that's interesting. Yeah. No minimum credit score.
So we look more at the equity side. So the older you are, the higher percentage you can borrow, younger, vice versa. So somebody who has, they should sell the house because in Massachusetts, to bring the house up to code, you have to hook it to the sewer. And there's no sewer and without even looking deeply to put in a new septic, quarter of a million dollars. Crazy. Yeah. And she is in her late 70s and it's like, well, why don't you sell the place? Right. Well, you have to young folks spend the quarter of a million dollars on the property.
Well, I mean, the poor woman has been living there for a long time and it's like, sometimes you can flush the toilets and sometimes you can't. That's bad enough. I grew up in an apartment in Brooklyn that had one bathroom. So weird. Well, I don't know if you I had an uncle who had, he had some sort of skin condition that didn't even take baths. I don't know whether it was enough. And after my bar mitzvah, when we must have had 13, for them maybe 20 people in the apartment, it wasn't a very big apartment. My uncle Ruby had to take a bath.
It was no place for anybody to use the toilet. He was done. The good old days, right? Well, it's like people used to say to my father, because he grew up during the Depression, and they'd go to him, Saul, you remember the good old days? It's like, what was good? Wiping your ass with fruit paper? I mean, what about that? Oh, Barry, that is awesome, man. Well, you've really opened our eyes. You've opened our eyes to a lot of stuff, including Bank Lexi. But if someone wanted to learn from your wealth of knowledge, how would people get in touch with you?
What's the best way to connect with them? They can send me an email at Barry at Levine's Law, levineslaw.com. Okay. Or my website is www.levineslaw.com. I think there's a way to message me there. And then my YouTube channel, it's Barry Levine Through the Looking Glass, which is the name of my book. That's awesome. The book happens to be very good, because it's sort of, it's, as you can tell from me, it's the process is not as serious as everybody thinks it is. That's right. Yeah. I tell people about the ritual sacrifices later.
We don't need to go into that at the beginning. Maybe they can wait for that. Well, Barry, I just want to thank you for all you're doing for- My pleasure. Thank you for your cooperation in Seniors and more importantly, thank you for keeping us laughing, sir. We don't need medicine, we don't need antidepressants, we just need to giggle. You got to laugh. Yeah. We got to laugh and you take care of that. Thanks for all you do, sir. I appreciate you serving these seniors. Maybe the Jets will beat the Titans if they play them next year.
That's what they go. They've been thinking of asking me to come out of retirement and quarterbacking. We'll have some fun. Well, thank you for watching this episode. Hey, one last thing. You would remember when they used two different footballs in the AFL. Oh, that's right. That was wild, wasn't it? Well, they still use the Duke, but I actually had an official AFL football, which was more aerodynamic. It made for better passing. Yeah. Well, they were a lot more fun. They knew a lot more than we thought they did. They knew the football needs to be scored.
Absolutely. Stay well. All right. Thank you, Barry. Been a pleasure. Take care. Have a good day. Hey, this is Matt Helton with OneTrust Home Loans, home of Retirement Mortgage Solutions. And we really do appreciate you checking out the Serving Seniors Podcast today. Now, please go to the description down in the body of the podcast where you can subscribe to get future shows. Please click that notification button so you get notified when other shows drop. And also, if you can go to servingseniorspodcast.com, and we'd love to hear a comment about our show.
We have a heart to serve seniors, and we have a heart to make sure seniors don't just survive retirement, don't just get by in retirement. We want to show seniors how to thrive in retirement. So if you know of anyone that's 55 and older, that could use some extra cash flow, maybe the retirement's not going the way that they like, our retirement mortgage solutions are designed for folks, and depending on the state, they're either 55 or 62 and older, to make sure that they have that kind of retirement that they want, as long as they own a home and they're in a good equity position.
There could be some solutions that they may not have thought about, or maybe they thought of and they just didn't know how they work. That's what we do. So anyone in that age group that could use some mortgage advice, my team and I would love to be able to help them. Thanks again and look forward to seeing you on the next show. Have a great day.
About Barry Levine
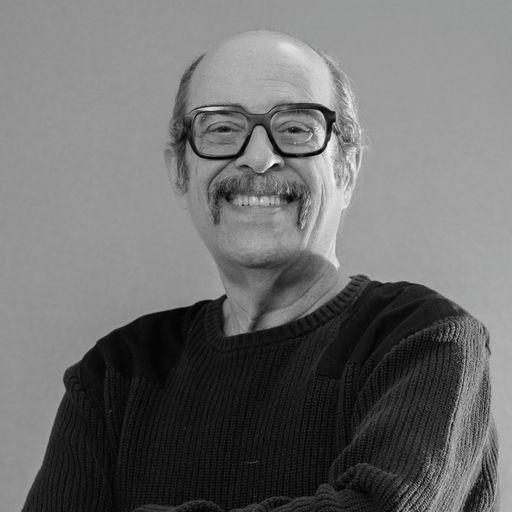
Bankruptcy Attorney and Debt Strategist for Everyday Americans in Crisis
45 years Representing people in financial difficulty1 book Author, Personal Bankruptcy Through The Looking Glass322 videos On his own bankruptcy YouTube channelBankruptcy attorney Massachusetts
The calls often come late: someone has ignored letters from the IRS, missed too many loan payments, or watched their small business slowly bleed out. They don’t open with legal questions. They ask if there’s any way out.
For almost 45 years, Barry Levine has answered that question with calm, practical guidance. A Massachusetts-based bankruptcy attorney, he works with individuals and small business owners navigating serious financial strain, people who are scared, out of options, and unsure what the next step even looks like. His work isn’t about judgement or quick fixes. It’s about helping people understand what tools are available, how the system works, and what choices they can still make.
What Barry sees again and again is that fear, not just debt, is what traps people. The legal process has structure, options, and predictable outcomes; what derails most clients is the panic that keeps them frozen in place. Barry’s role is to bring order to the chaos. With each case, he applies decades of legal experience to help clients understand what’s happening, what’s possible, and how to move forward with a strategy that restores both stability and control.
He first started practicing bankruptcy law in a hands-on Boston office while still in law school, learning case by case how to navigate both paperwork and people.
More from Barry Levine
All episodes → The Agent of WealthFinancial Crisis, Bankruptcy and Starting Over With Barry LevineOct 2026Play episode →
 School for Startups RadioOctober 5, 2026 – EdTech Find Your Grind Nick Gross and Bankruptcy Attorney Barry LevineOct 2026Play episode →
 Financial Mastery SimplifiedHow Bankruptcy Really Affects Your Credit and Home LoanSep 2026Play episode →
 Money Talk With TiffWhat Bankruptcy Actually Does with Attorney Barry LevineAug 2026Play episode →
 Wealth B-HersFear, not Debt with Barry LevineJul 2026Play episode →
 Us People PodcastThe Law We Decide To Practice - Barry Levine - Attorney At Law #314Apr 2026Play episode →
 Chrisman Commentary - Daily Mortgage News4.14.26 Fines Versus Taxes; Attorney Barry Levine on Delinquencies and Foreclosures; Agency MBS PerformanceApr 2026Play episode →
 JUSTIN AND THE [FOOD] ENTREPRENEURSEpisode 520: Barry Levine of The Law Offices of Barry R. Levine - Beverly, MA. Shielding Your Personal Assets. Avoid Bankruptcy Before It Hits. Legal Lifelines for Food Entrepreneurs. Cost Accounting.Apr 2026Play episode →
 How Much Can I Make? — Real Jobs. Real People. Real Money.Bankruptcy Lawyer Explains Chapter 7, Chapter 13 & Getting a Fresh StartMar 2026Play episode →