Growth and M&A
Why Growing 10x Through Acquisitions Can Be Easier Than 2x
David Horne explains how founders can fund, acquire, consolidate and exit their way to faster growth, and why buying a good business beats buying a cheap one.
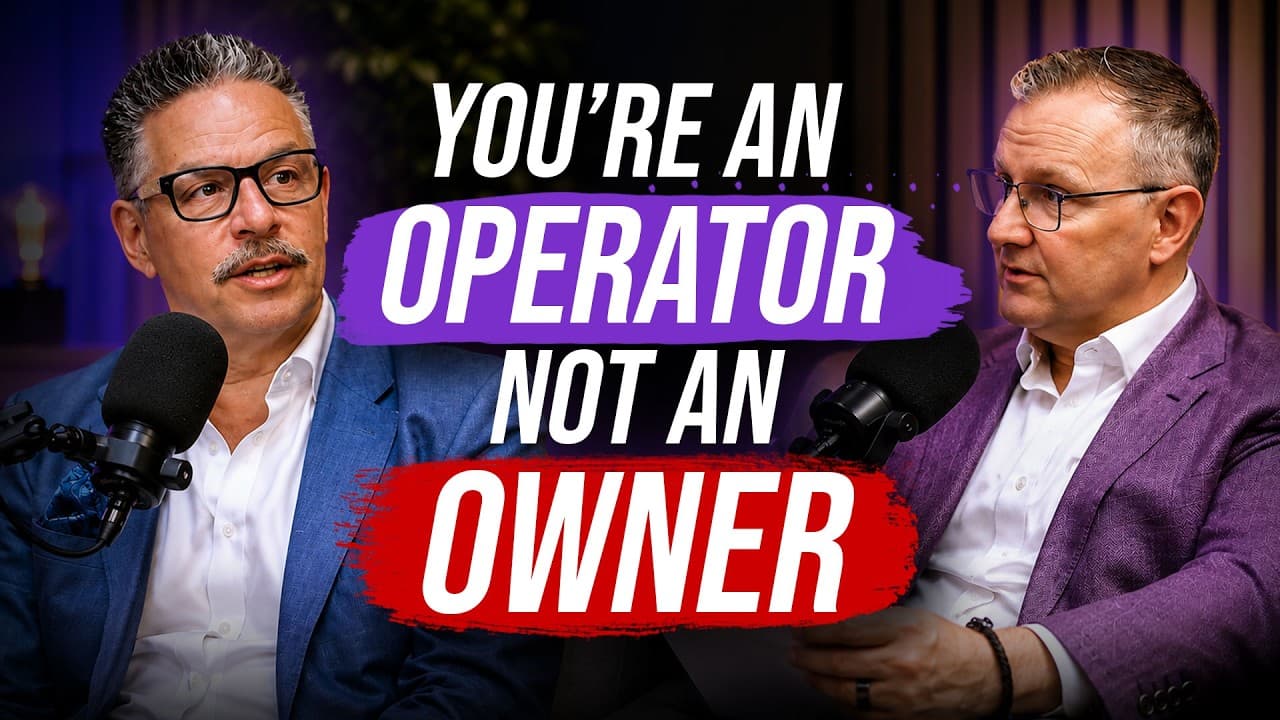
The M&A Strategist: 10x Is Easier Than 2x! How I Went From £1M To £28M - David B. Horne
Video from The Grown Up Business Podcast.
Generated from the canonical interview transcript and validated against source data by Guests on Air.
How can founders use acquisitions to grow a business ten times faster?
Founders can grow faster through acquisitions by securing funding before the deal, buying good businesses rather than cheap turnarounds, integrating people and systems with care, and preparing early for an exit. David Horne calls this sequence FACE: fund, acquire, consolidate and exit. It starts with accepting that acquisitions are open to smaller established companies, not only to large corporations.
Most founders are told that growth comes from selling more, hiring more people and waiting patiently for results. David Horne, founder of the consultancy Add Then Multiply, argues that established businesses can often grow much faster by buying other companies. On The Grown Up Business Podcast, he explains how that works in practice and where it goes wrong.
His case rests on experience. As chief financial officer of companies listed on London's Alternative Investment Market, he helped grow one business from around one million pounds in turnover to 28 million in three years. That growth came from seven private acquisitions and the takeover of another listed company, each one funded, bought and then integrated.
Horne now advises founders on the same route, and he is candid that it is a different game from running a business day to day. It needs the right funding, the right targets, a dedicated deal team and advisers who have done it before. This article sets out his method, the traps he warns about and the preparation that pays off at exit.
Key takeaways
- Acquisitions are open to established small businesses, not only to large corporations.
- Secure funding before the deal and understand the real trade offs between debt and equity.
- Buy good businesses at fair prices rather than cheap turnarounds with desperate sellers.
- Plan integration with care and start preparing for an exit about three years before a sale.
1. Why acquisitions feel out of reach for most founders
Horne says the first barrier is belief. Many entrepreneurs assume that mergers and acquisitions belong to large corporations and FTSE 100 companies. In his view, a smaller firm can use the same tools. A hairdressing business can buy salons in other towns, and a restaurant group can buy a local chain to extend its reach into new territory.
He is equally direct about who should try it. Buying a business you cannot already run well means learning an industry on someone else's retirement fund and paying for every mistake along the way. His advice is to master one business first, or to buy a small one, grow it for a few years and then pursue larger deals.
Horne prefers quality over bargains. He cites Warren Buffett's view that it is far better to buy a wonderful company at a fair price than a fair company at a wonderful price. Deals sold as no money down are often businesses whose owners are desperate to leave, and turnarounds, he says from his own experience, are brutally hard work.
2. How the FACE method sequences a growth deal
His framework is called FACE, which stands for fund, acquire, consolidate and exit. Funding comes first. He describes debt, which has to be repaid with interest and often carries covenants, and equity, where founders sell a stake in the company. Fintech lenders move quickly but are expensive, and they usually want a personal guarantee from the founder.
He challenges founders who refuse to give up any shares. In a worked example, a founder who keeps 57 percent of a company worth 50 million ends up far better off than one who owns all of a company worth three million. Raising money also forces a clear strategy, because investors will test the numbers and pick holes in a weak plan.
Targets can be competitors, complementary firms, suppliers or businesses in new locations. Horne recommends approaching owners directly by phone, letter, email or LinkedIn, and building a genuine human connection. Many sellers care deeply about their staff, so a buyer who shows a strong values fit can win a deal even when another bidder offers more money.
3. Where deals succeed or fail after the signing
Consolidation is where Horne says most of the risk sits. Bringing two teams together, especially former rivals, needs a clear plan. One tactic he has used since his listed company days is to bring strong managers from the acquired business into the wider leadership team, which reassures their colleagues and adds a fresh perspective on the combined group.
He also urges founders to build a proper deal team rather than loading acquisition work onto people already running the core business. As a chief financial officer, he spent around 80 percent of his time on deals while strong finance staff handled daily operations. Outside the business, he says founders need an accountant and a lawyer with real acquisition experience.
The final stage is the exit. Horne says preparing a company properly for sale takes about three years, with growing financials, clean contracts, documented processes and protected intellectual property. Done well, that groundwork can lift a valuation from five times earnings to eight times, which could turn a sale worth 10 million into one worth 18 million.